📺 Watch the Full Video Analysis
This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-10-29 20:39 JST)
📄 Primary Source
Bank of England
https://www.bankofengland.co.uk/statistics/money-and-credit/2026/september-2026
📊 A deep dive into the Bank of England’s Money and Credit release for September, published October 29.
💷 Net lending to the private sector (M4Lex) rose to £17.0bn, while the net flow of sterling money (M4ex) slowed to £3.9bn.
📈 Corporate bank borrowing jumped to £10.6bn and remortgage approvals climbed to 42,600.
⚠️ House purchase approvals (53,400) stayed below their 6-month average, and M4ex annual growth eased to 4.0%.
💡 A balanced read of strength and softness, with a caution on revised prior-month data.
Next release: November 30 (October data).
The Ultimate Summary:貸出は強く、広義のお金は鈍化
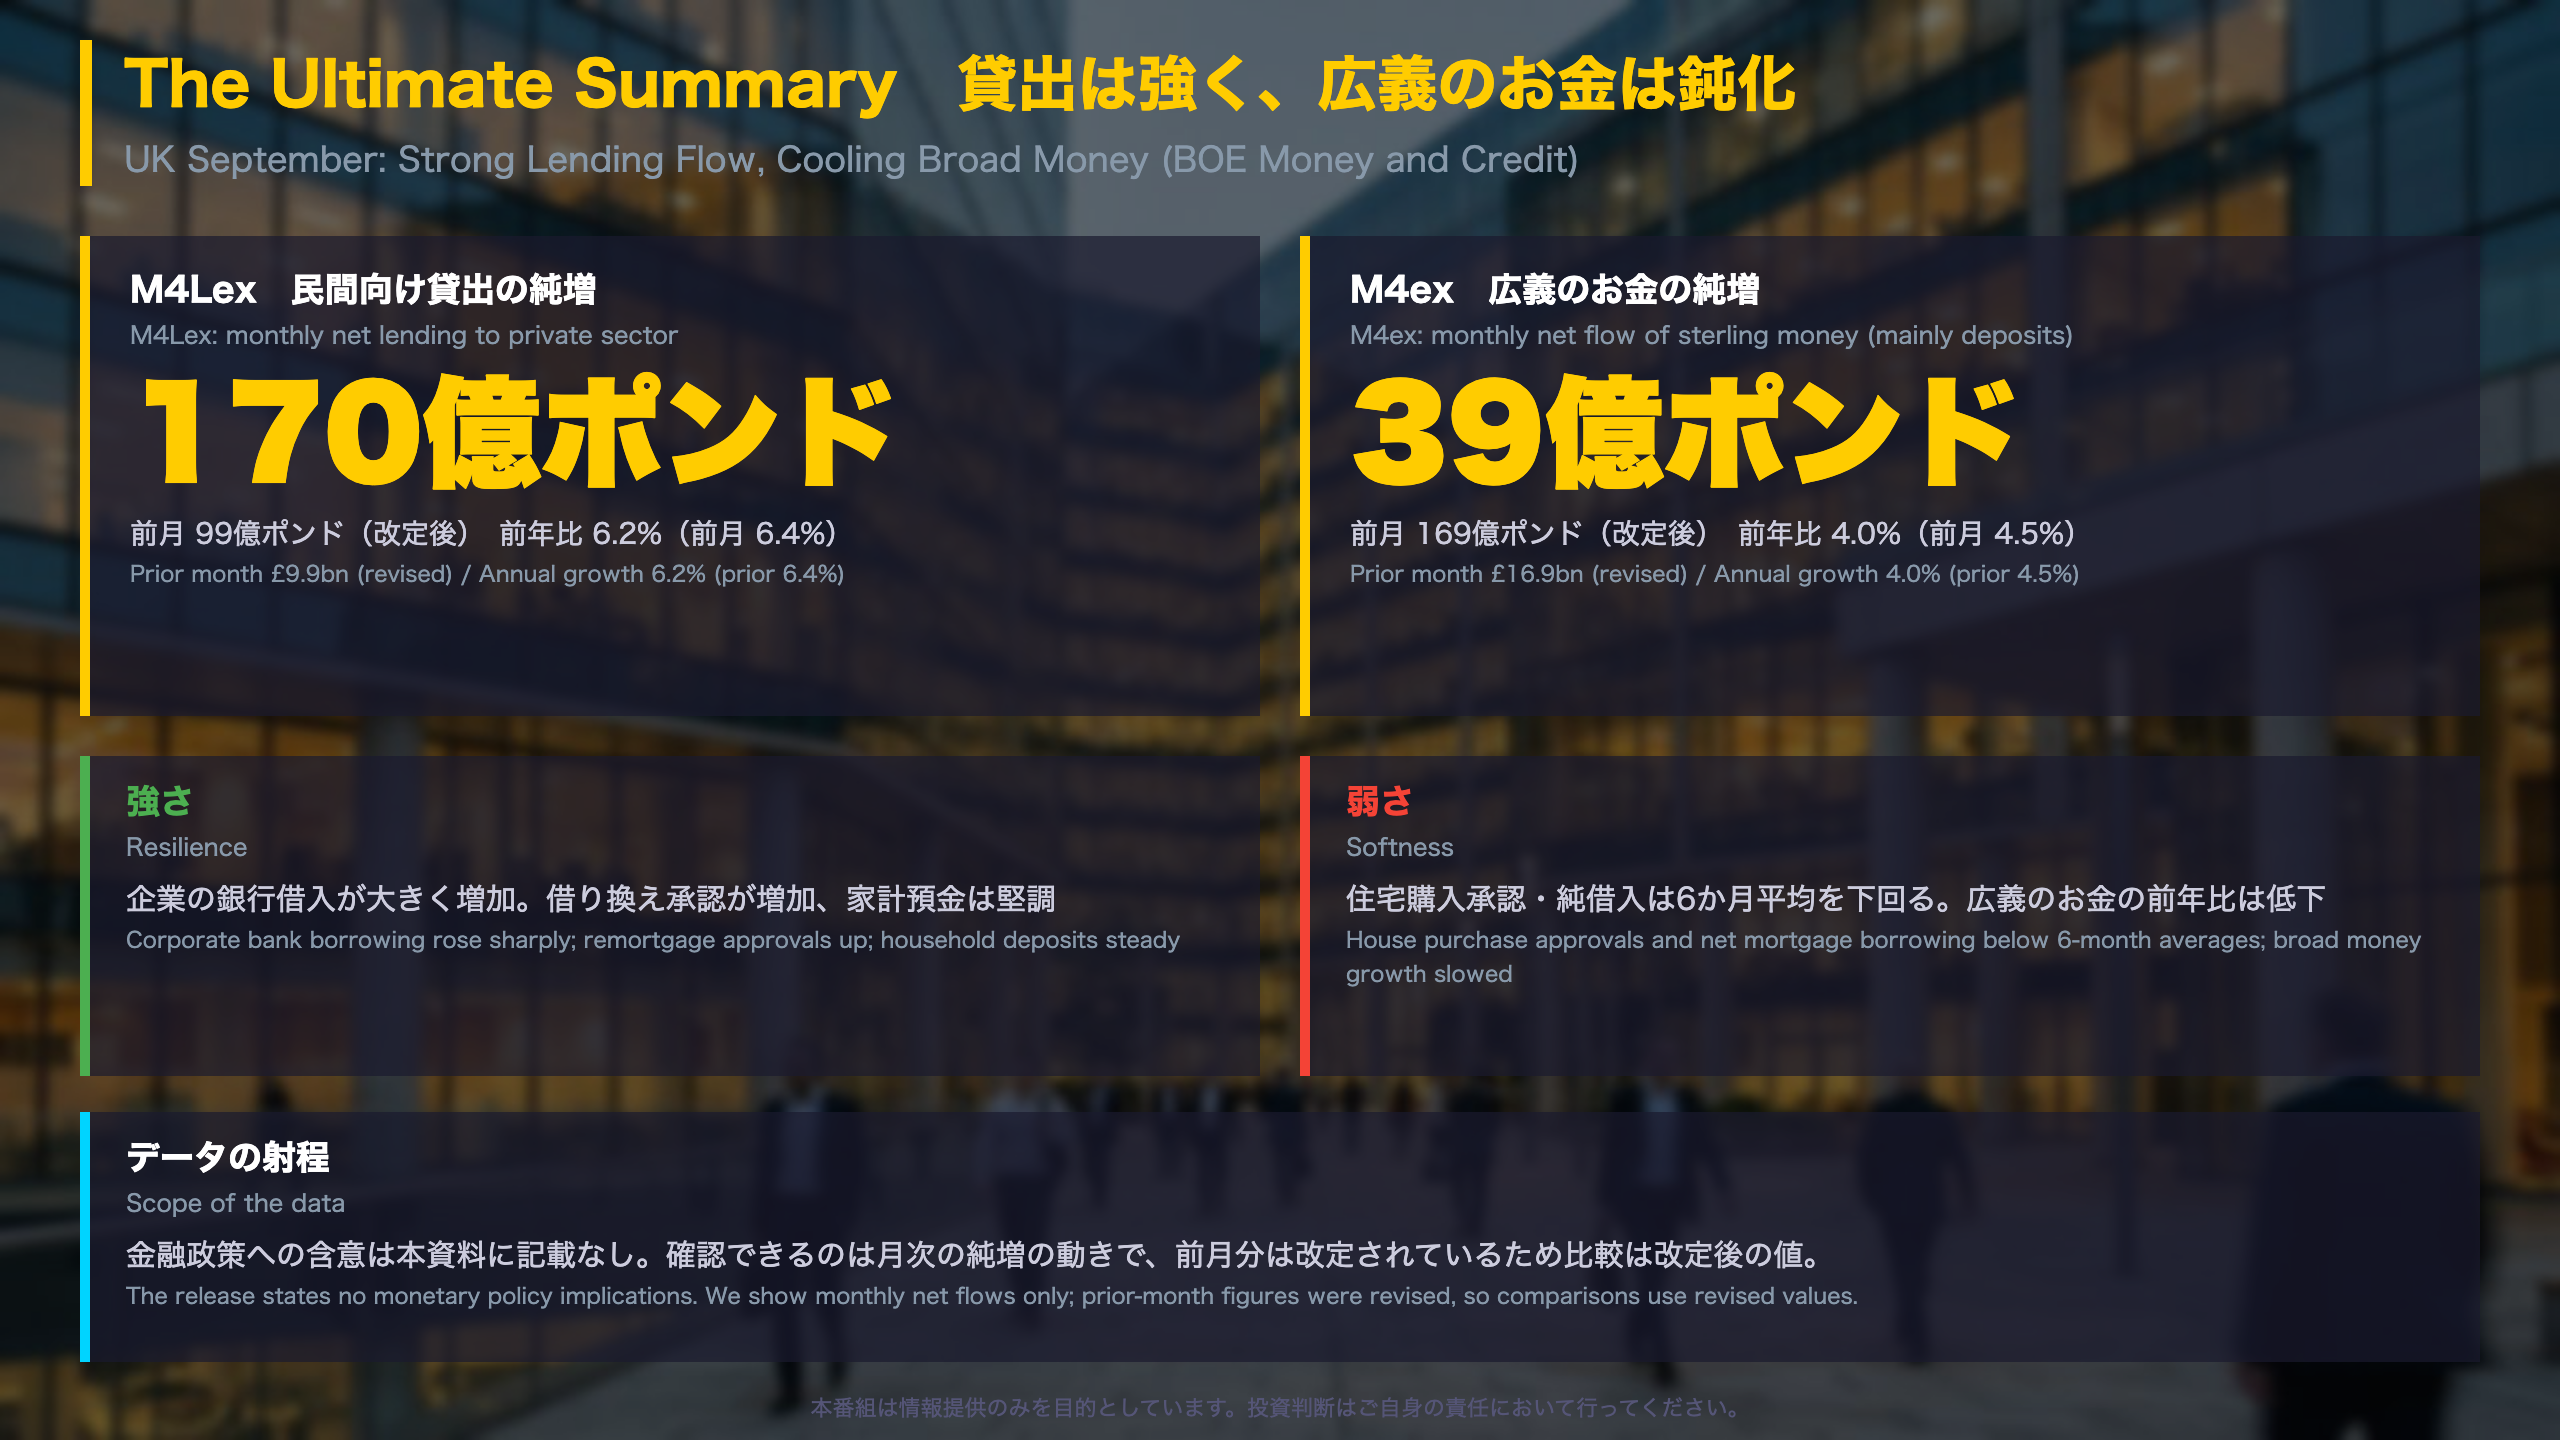
UK Money and Credit, September 2026: What the Split Means
Who publishes this? The Bank of England (BOE) releases its Money and Credit statistics monthly, and its policy committees use them to follow borrowing and deposits across households and businesses. The release carries no policy guidance of its own.
Two measures, two stories. M4Lex is the net monthly flow of sterling lending to UK private-sector companies and households. M4ex is the net flow of sterling money, largely deposits, excluding intermediate financial firms. The nearest US analogues are the Fed’s bank-credit and M2 series, though the UK headline figures are monthly flows rather than levels.
| Measure | Sep | Aug (revised) |
|---|---|---|
| M4Lex flow | £17.0bn | £9.9bn |
| M4ex flow | £3.9bn | £16.9bn |
| M4Lex annual growth | 6.2% | 6.4% |
| M4ex annual growth | 4.0% | 4.5% |
Independent read. Monthly flows are noisy and heavily revised: August M4Lex was first published at £3.9bn and now stands at £9.9bn. Annual growth rates move far less, and both edged lower. A fair reading is that credit demand was solid in the month, while the annual pace of money and lending growth was little changed to slightly softer.
Why it is watched. Credit and deposit trends help show the health of household and corporate balance sheets. This release does not state a view on interest rates or the pound. The next print covers October and is due November 30.
企業の資金調達:銀行借入が大幅増、全体は小幅
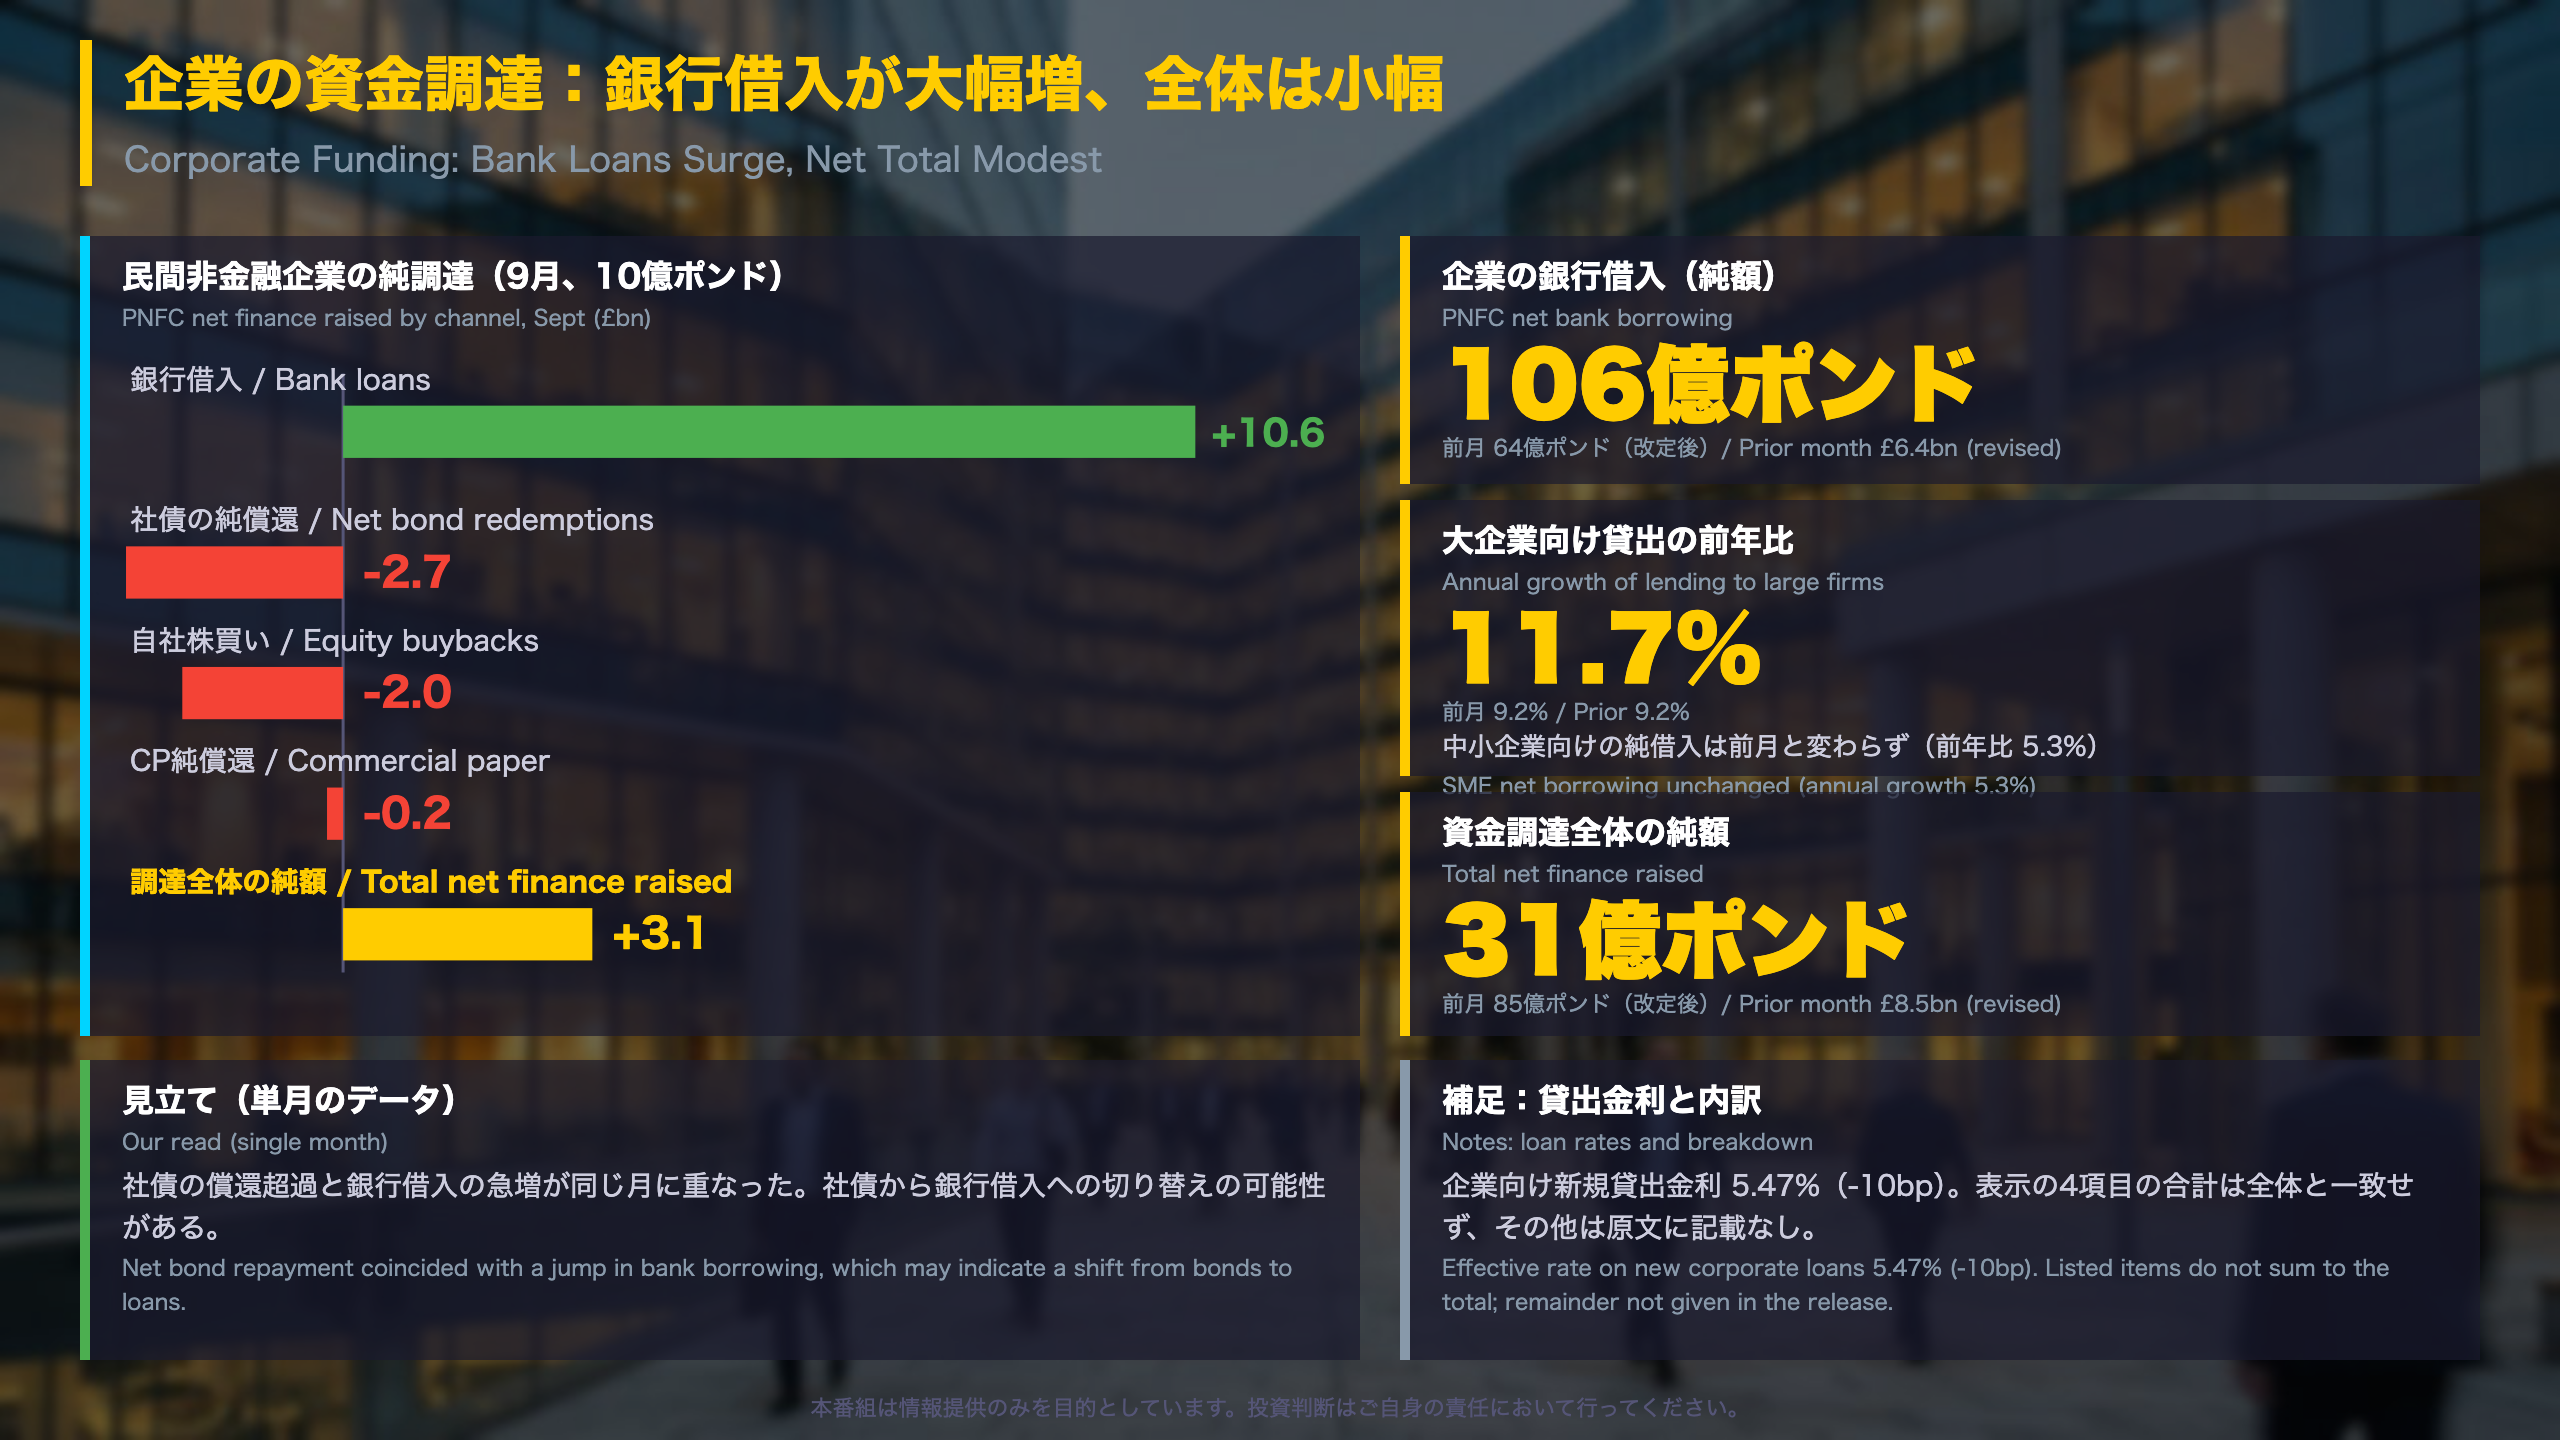
UK Corporate Funding in September: Bank Loans Up, Bonds Repaid
Terminology. PNFCs are private non-financial corporations, meaning companies outside banking and finance. The Bank of England’s Money and Credit release tracks how they raise funds through bank loans, bonds, commercial paper and equity.
What happened. PNFCs drew a net £10.6bn from banks, up from £6.4bn in August (revised). Large firms led: their annual loan growth rose to 11.7% from 9.2%, while small and medium-sized firms borrowed a net £1.0bn, unchanged, with annual growth of 5.3%.
Why the total looks small. Net finance raised across all channels was only £3.1bn, versus £8.5bn in August. Net bond redemptions of £2.7bn and net equity buybacks of £2.0bn were among the offsets. The listed items do not sum to the total, and the release gives no detail on the remaining roughly £2.6bn (our arithmetic).
International comparison. In the US, large companies lean more heavily on corporate bond markets than UK firms typically do, so a month in which bond repayment coincides with bank borrowing is worth tracking. Here it is a single observation.
Independent analysis. Two readings fit the data: a swap from bonds to bank loans, or genuinely stronger funding demand among large firms. Falling effective rates on new corporate loans (5.47%, down 10bp) are consistent with either. Corporate deposits also rose £8.9bn, so some borrowing may simply have been held as cash. The release does not state purposes.
Next release: November 30, covering October.
家計:住宅購入は弱め、借り換えは急増
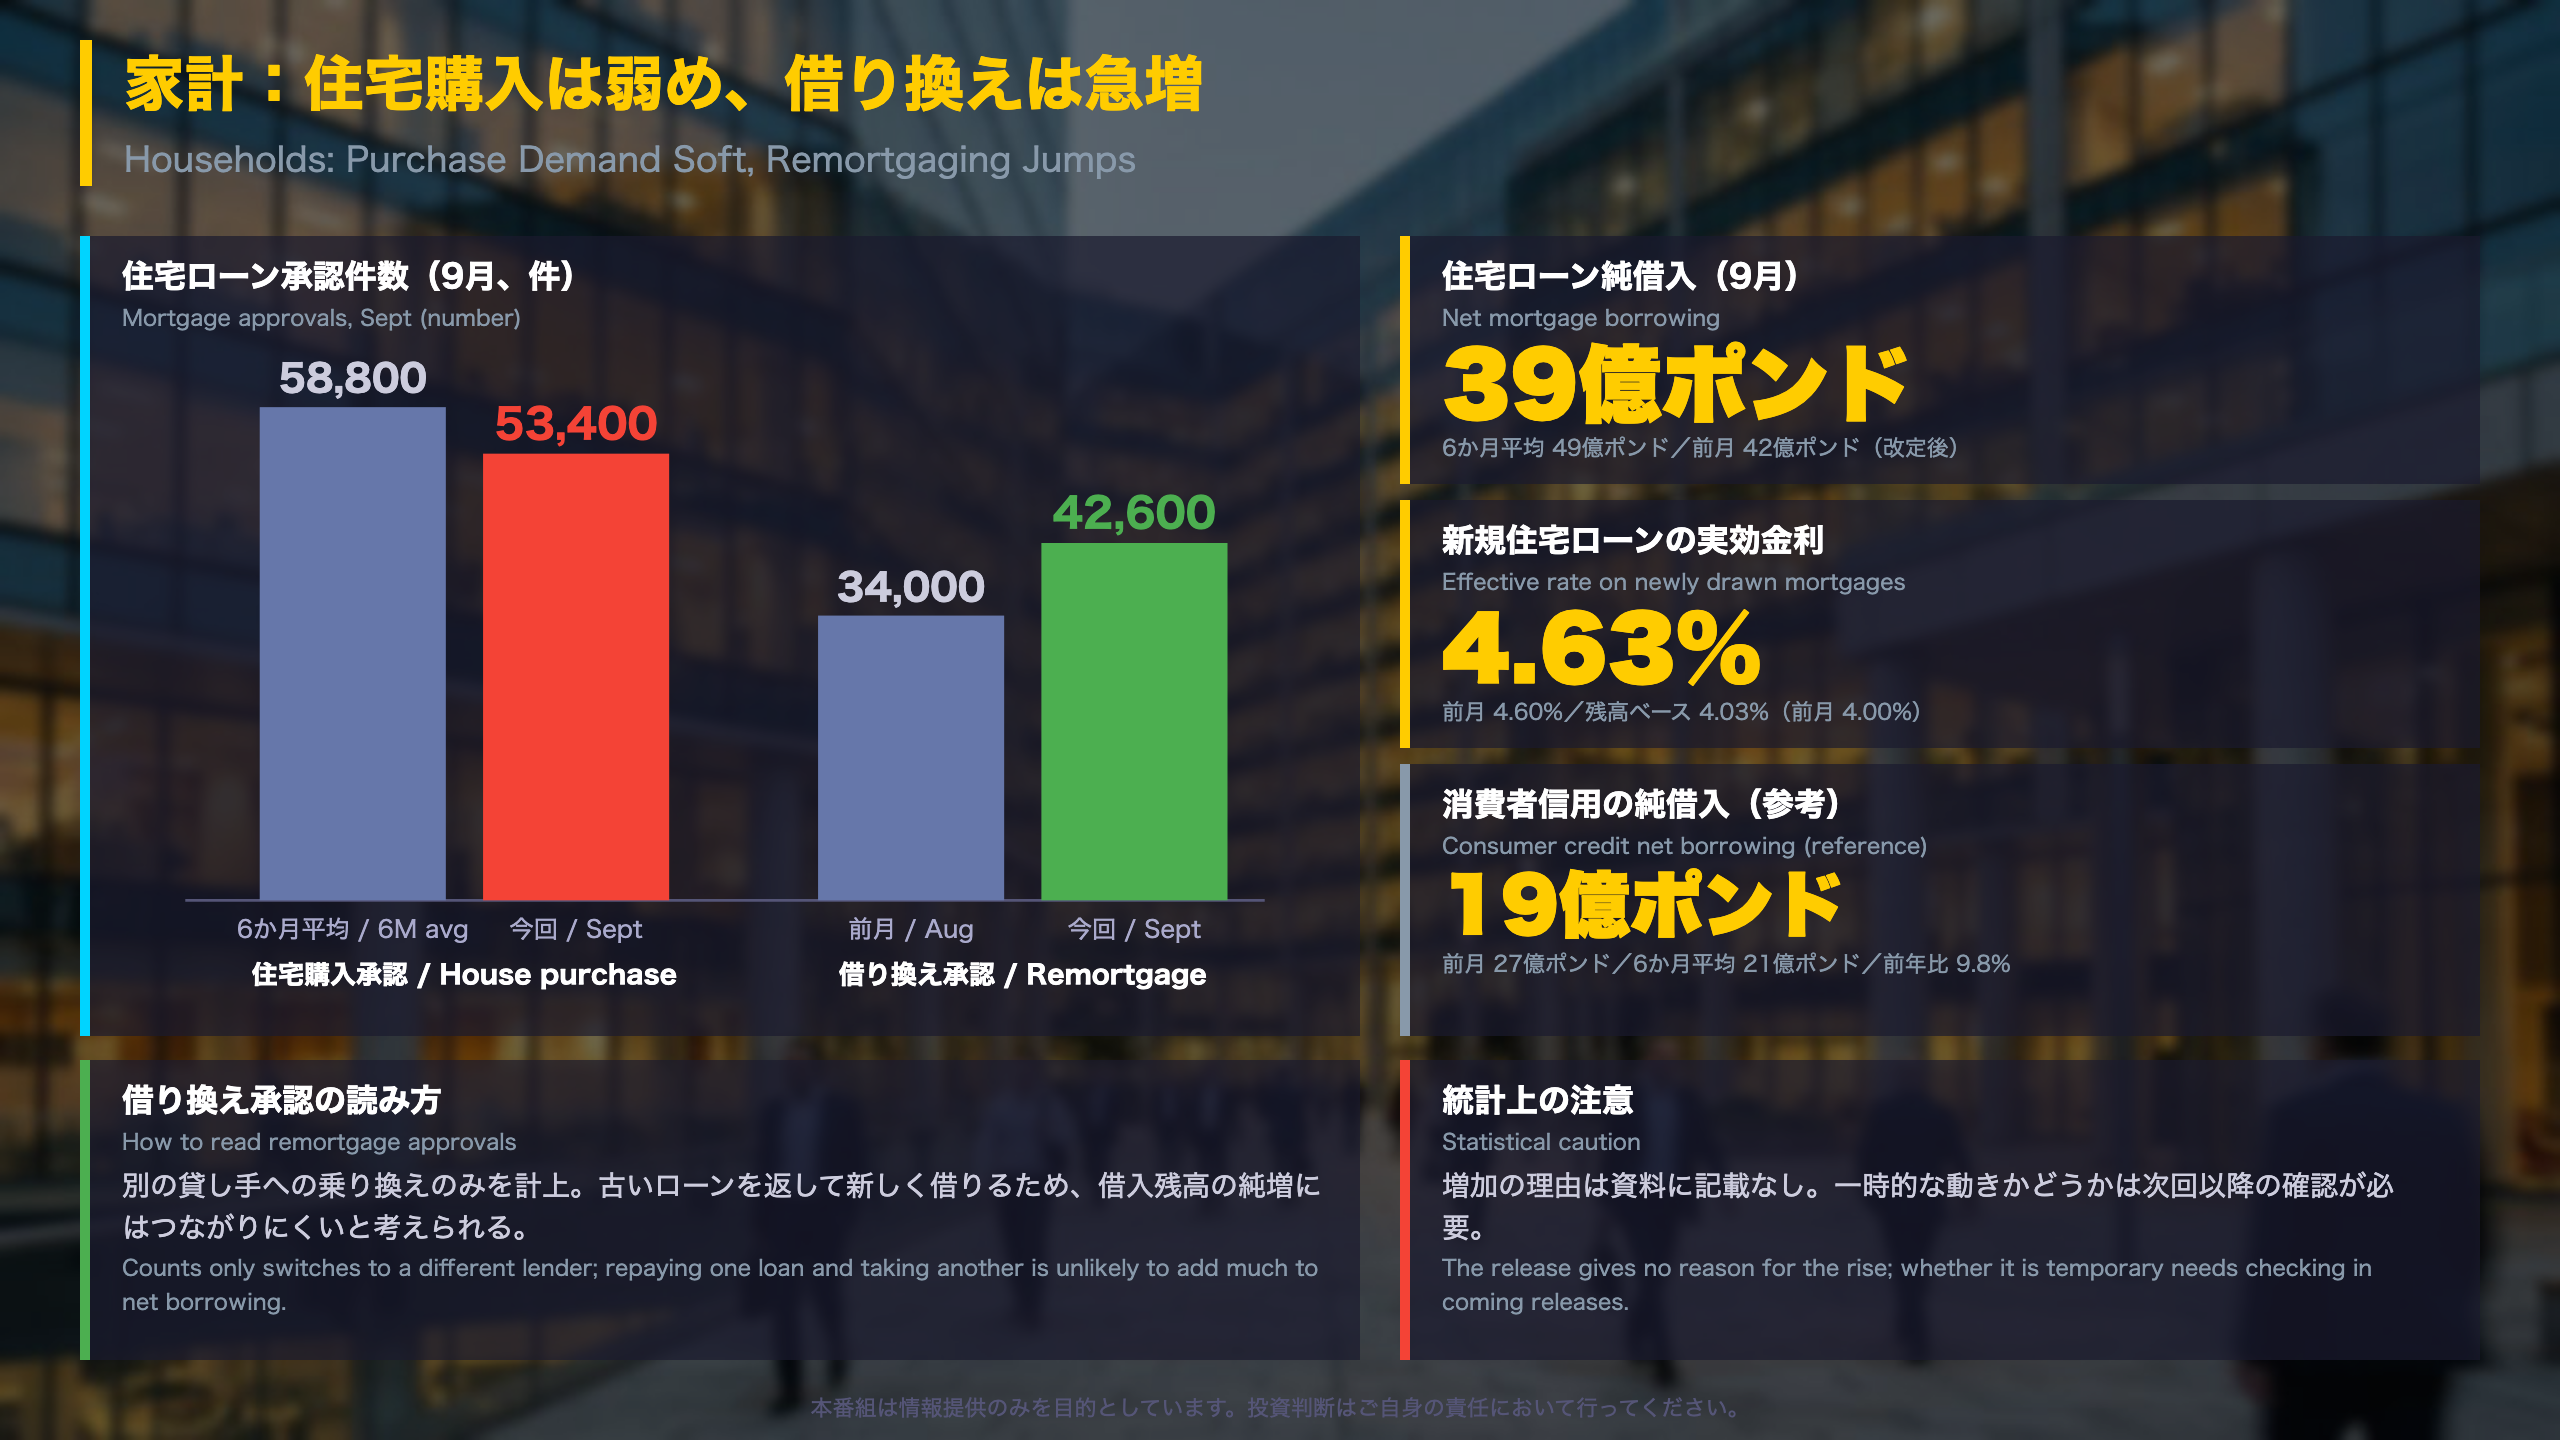
UK Households in September: Weak Purchase Approvals, Surging Remortgages
What these numbers are. The Bank of England counts mortgage approvals net of cancellations as a lead indicator of future borrowing. They play a role similar to the US mortgage purchase applications data, but the UK series is a count of approved loans, not applications.
| Indicator | Sep | Comparison |
|---|---|---|
| House purchase approvals | 53,400 | Aug 54,800; 6-mo avg ~58,800 |
| Remortgage approvals | 42,600 | Aug 34,000 |
| Net mortgage borrowing | £3.9bn | Aug £4.2bn; 6-mo avg £4.9bn |
| Effective rate, new mortgages | 4.63% | Aug 4.60% |
Why remortgaging is not new lending. The remortgage series only captures switches to a different lender. Borrowers repay one loan and take another, so the jump of roughly 25% (our arithmetic) need not lift net borrowing. Many UK mortgages carry fixed terms that expire periodically, which makes remortgaging a recurring activity, though the release gives no reason for this month’s rise.
Balanced view. Positives: remortgage activity is brisk, and consumer credit growth was 9.8% annually, up slightly. Negatives: purchase approvals sit about 9% below their six-month average, mortgage growth eased to 3.4% from 3.6%, and consumer credit net borrowing fell to £1.9bn from £2.7bn.
Rates. Effective overdraft rates rose 52bp to 20.79%, while personal loan rates fell to 9.85%. The picture is mixed. The release offers no forecasts; the next data arrive November 30.
質疑で深める:貸出と預金のずれ、預金の中身、金利
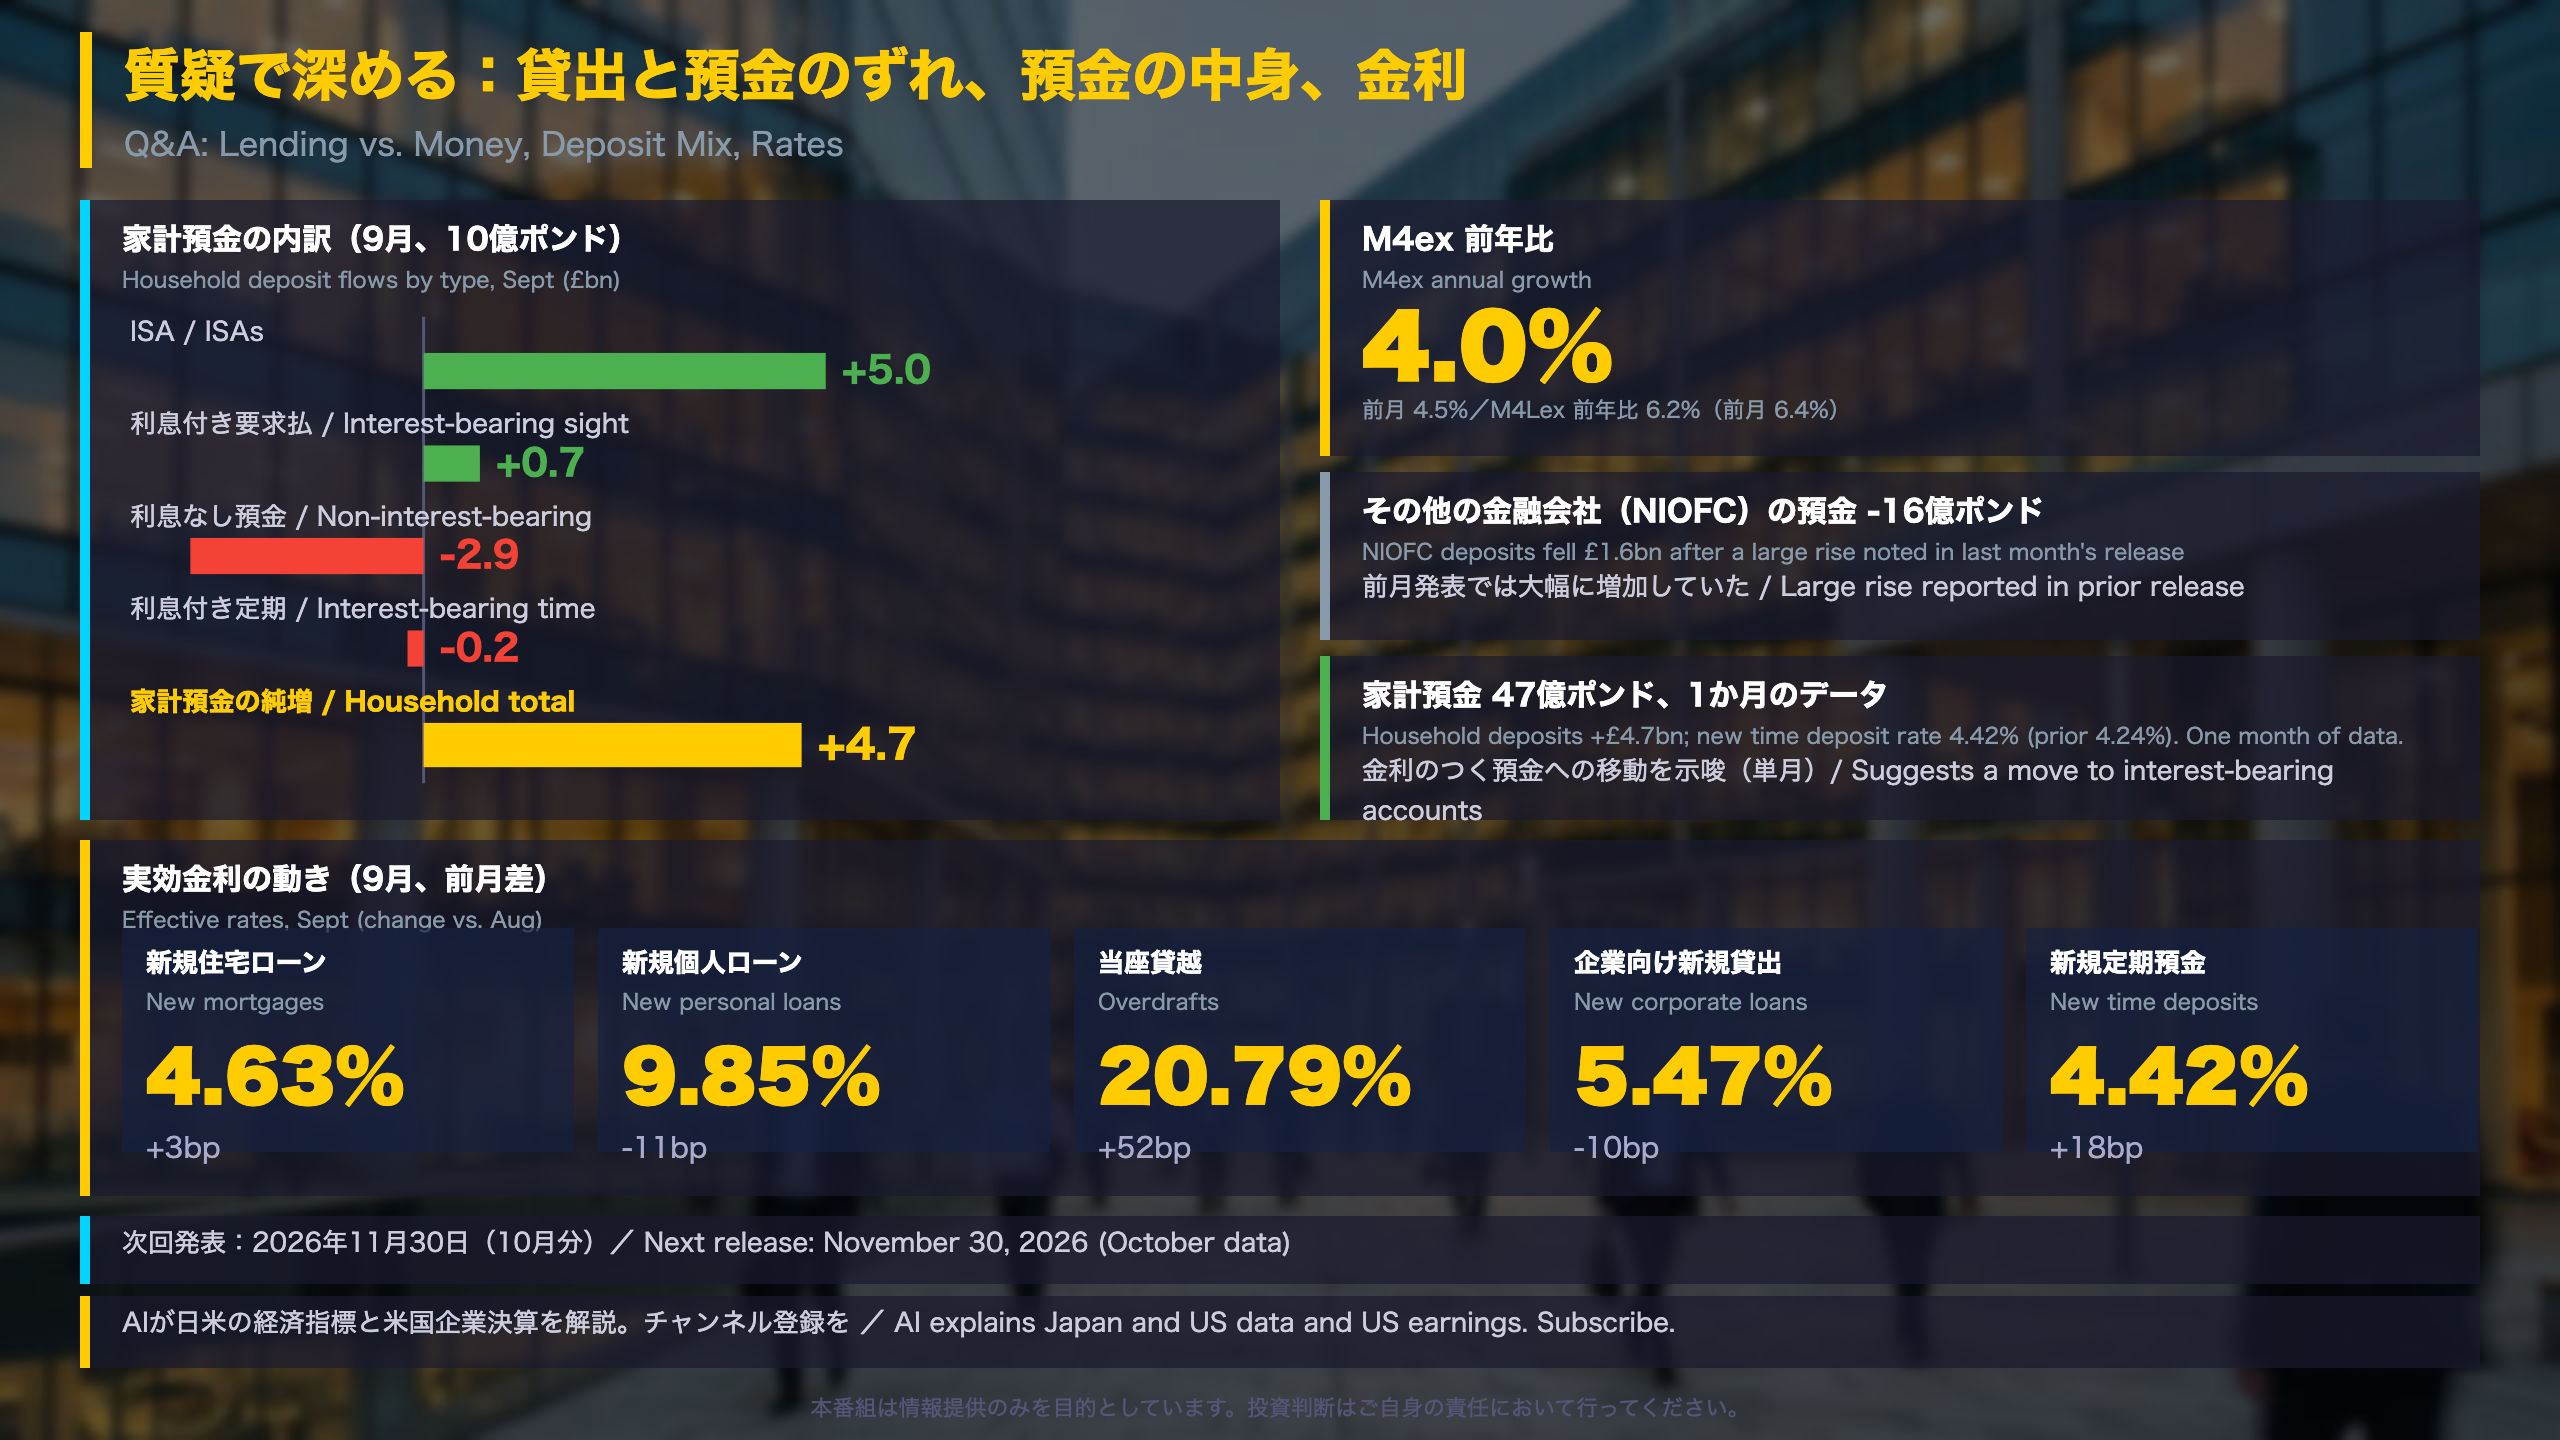
Deposit Mix and Effective Rates: Stable Size, Shifting Composition
Terms. ISAs are tax-advantaged UK savings accounts. Sight deposits are accessible on demand; time deposits are locked for a term. NIOFCs are non-intermediate other financial corporations, such as asset managers and similar non-bank financial firms.
Household deposits. Households added a net £4.7bn in September (August: £4.9bn). ISAs took in £5.0bn and interest-bearing sight accounts £0.7bn, while £2.9bn left non-interest-bearing accounts and £0.2bn left time accounts. These four items sum to £2.6bn, not £4.7bn, and the release does not detail the rest (our arithmetic).
Rates. The effective rate on new time deposits rose to 4.42% from 4.24%. On the lending side the picture is mixed: new mortgages 4.63% (+3bp), personal loans 9.85% (down 11bp), overdrafts 20.79% (+52bp), new corporate loans 5.47% (down 10bp).
International comparison. The shift toward interest-bearing balances echoes what US data show in money market funds and savings products when yields are attractive, though UK ISAs add a tax angle.
Independent analysis. M4ex annual growth fell to 4.0% from 4.5%, partly reflecting other financial firms trimming deposits (-£1.6bn) after a large inflow reported last month. That makes the headline slowdown look more like noise around a steady household trend than a broad deterioration, though one month cannot settle it.
The release carries no policy guidance. The next release, covering October, is on November 30.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.