This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-10-31 18:00 JST)
📊 D.R. Horton (DHI), the largest US homebuilder, reported fiscal Q4 (Jul-Sep 2026) results.
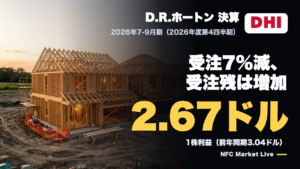
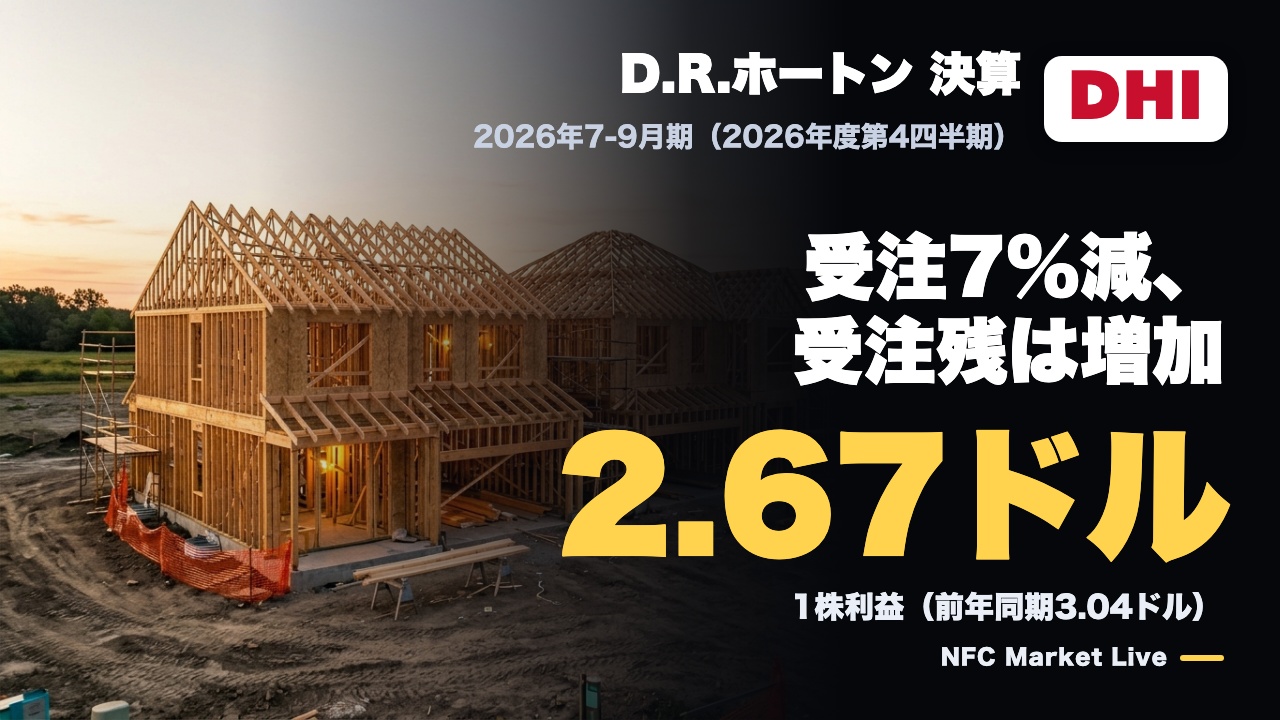
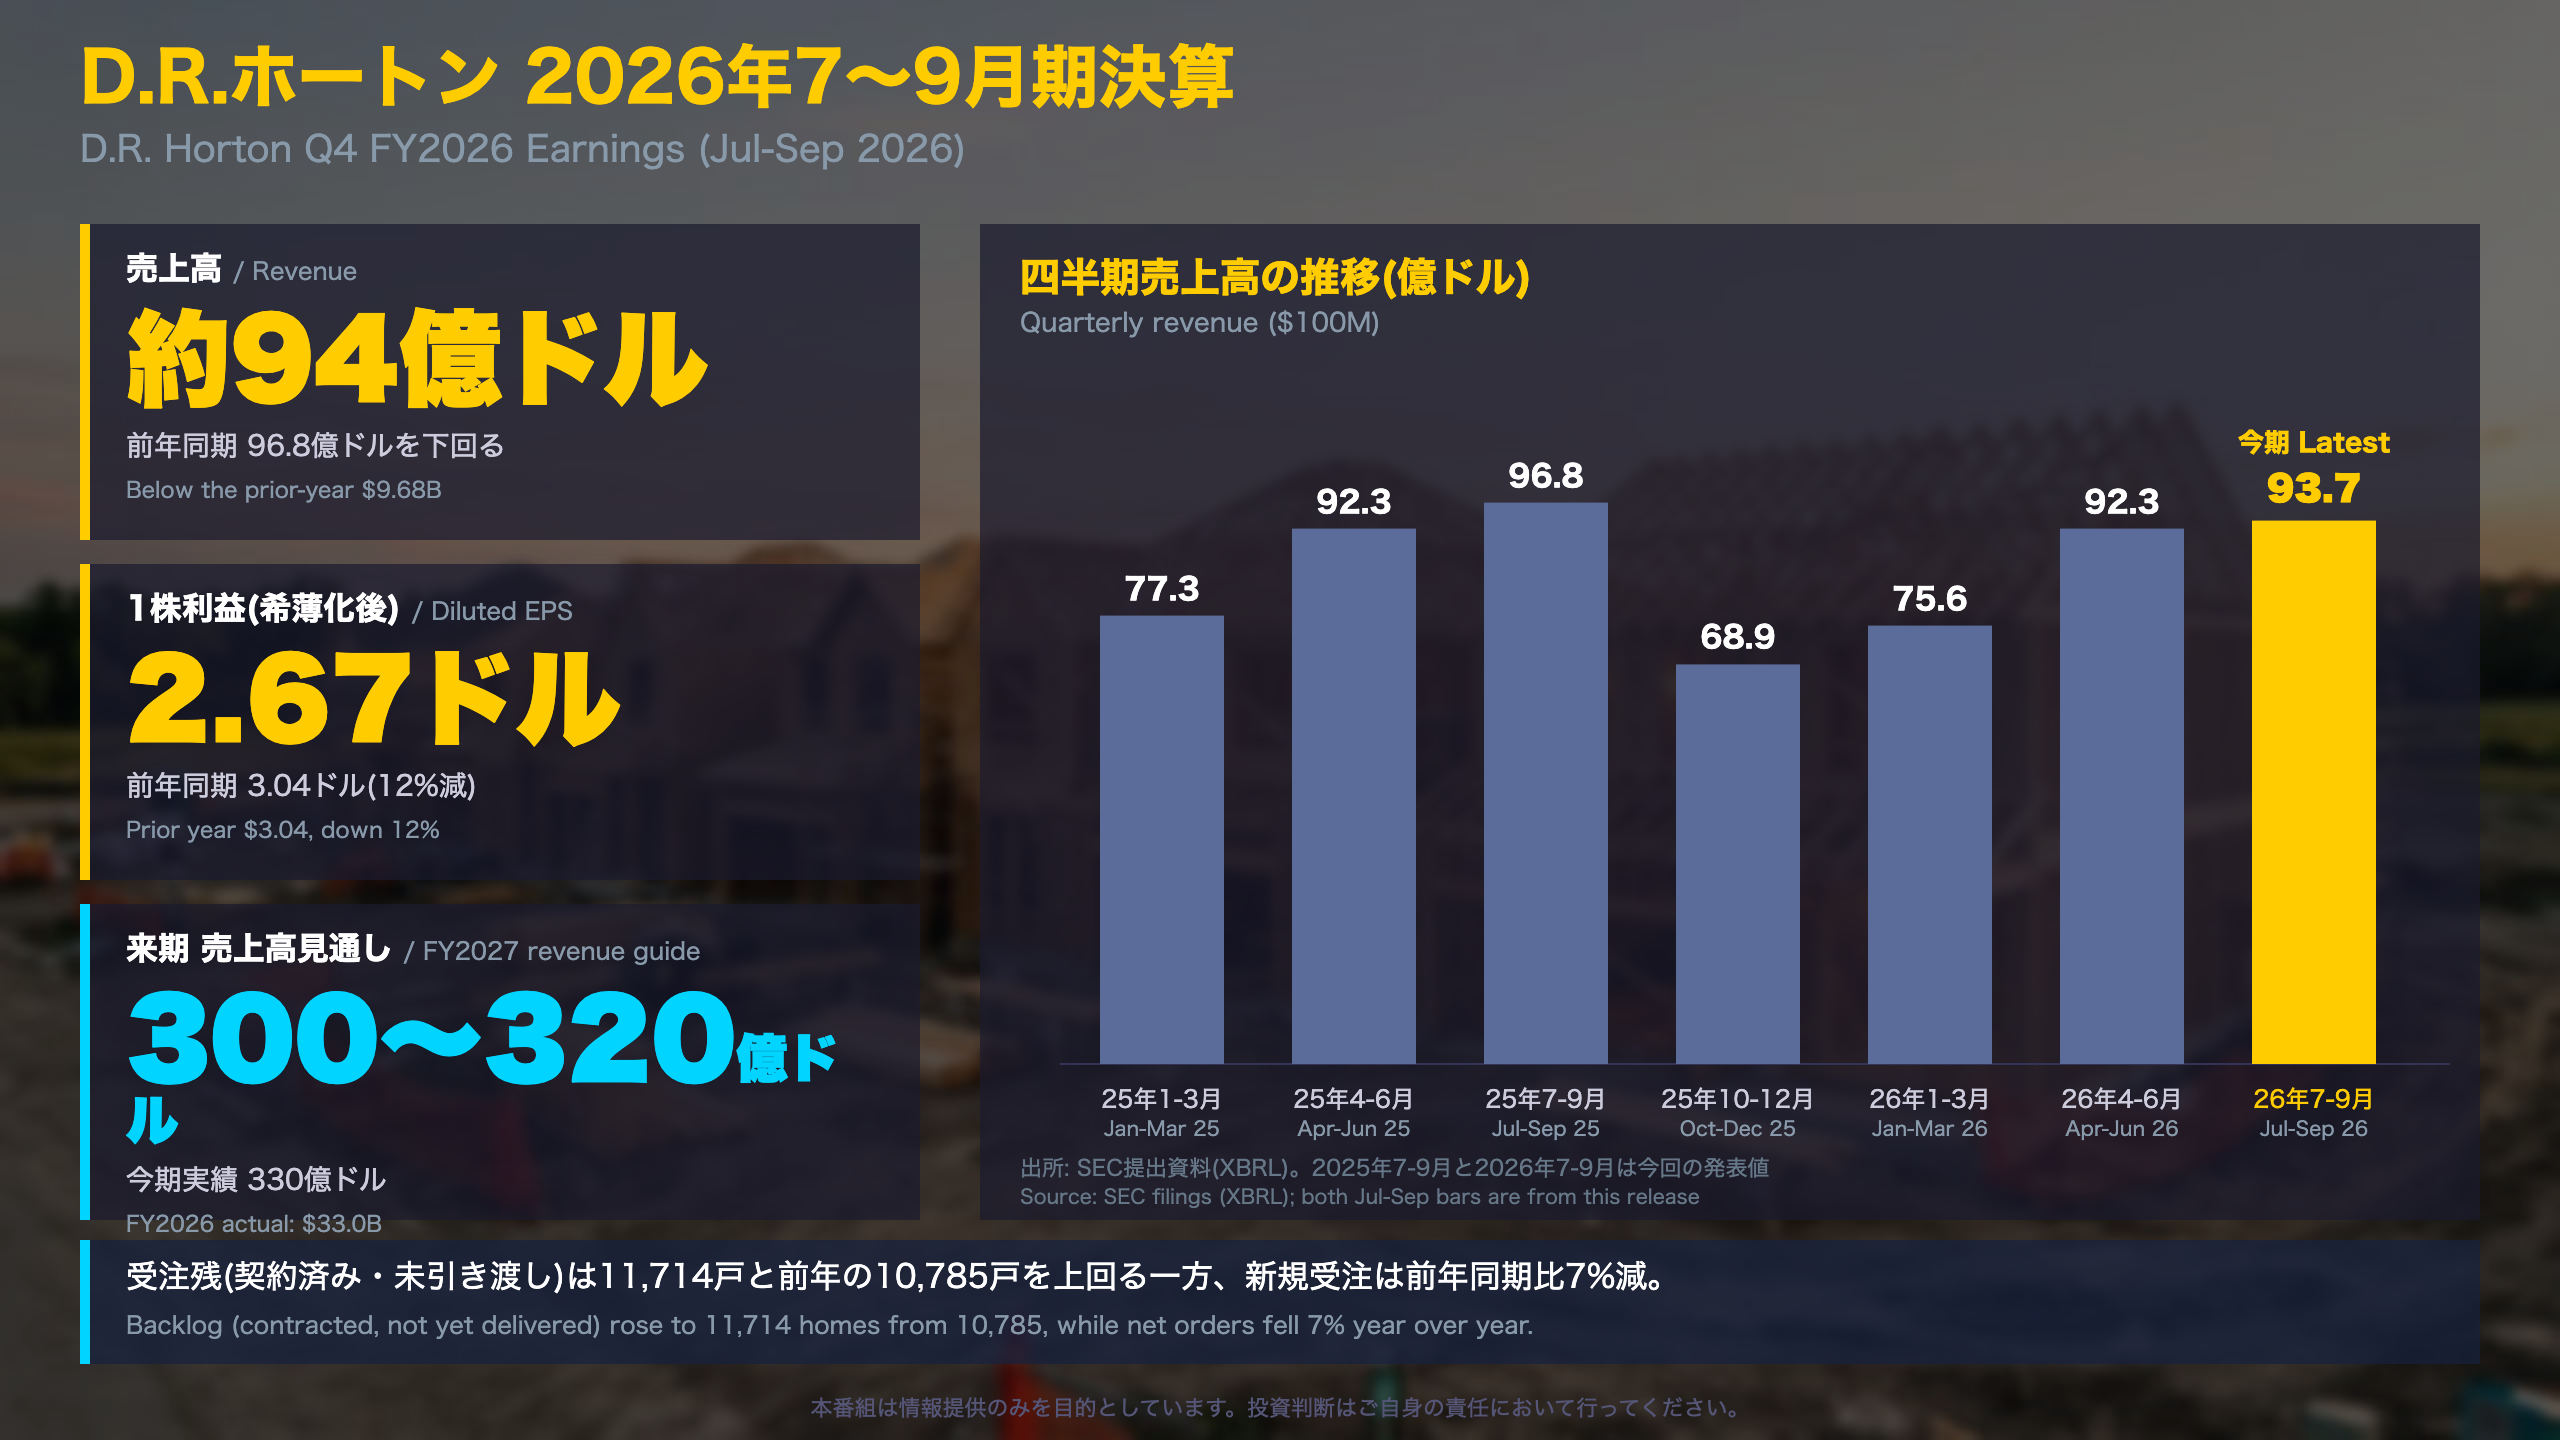
📉 Revenue was about $9.4B and diluted EPS $2.67 versus $3.04 a year earlier. Net orders fell 7% and the cancellation rate rose to 23%.
📈 The backlog rose to 11,714 homes, debt to total capital is 20.8%, and the quarterly dividend was raised 11% to $0.50.
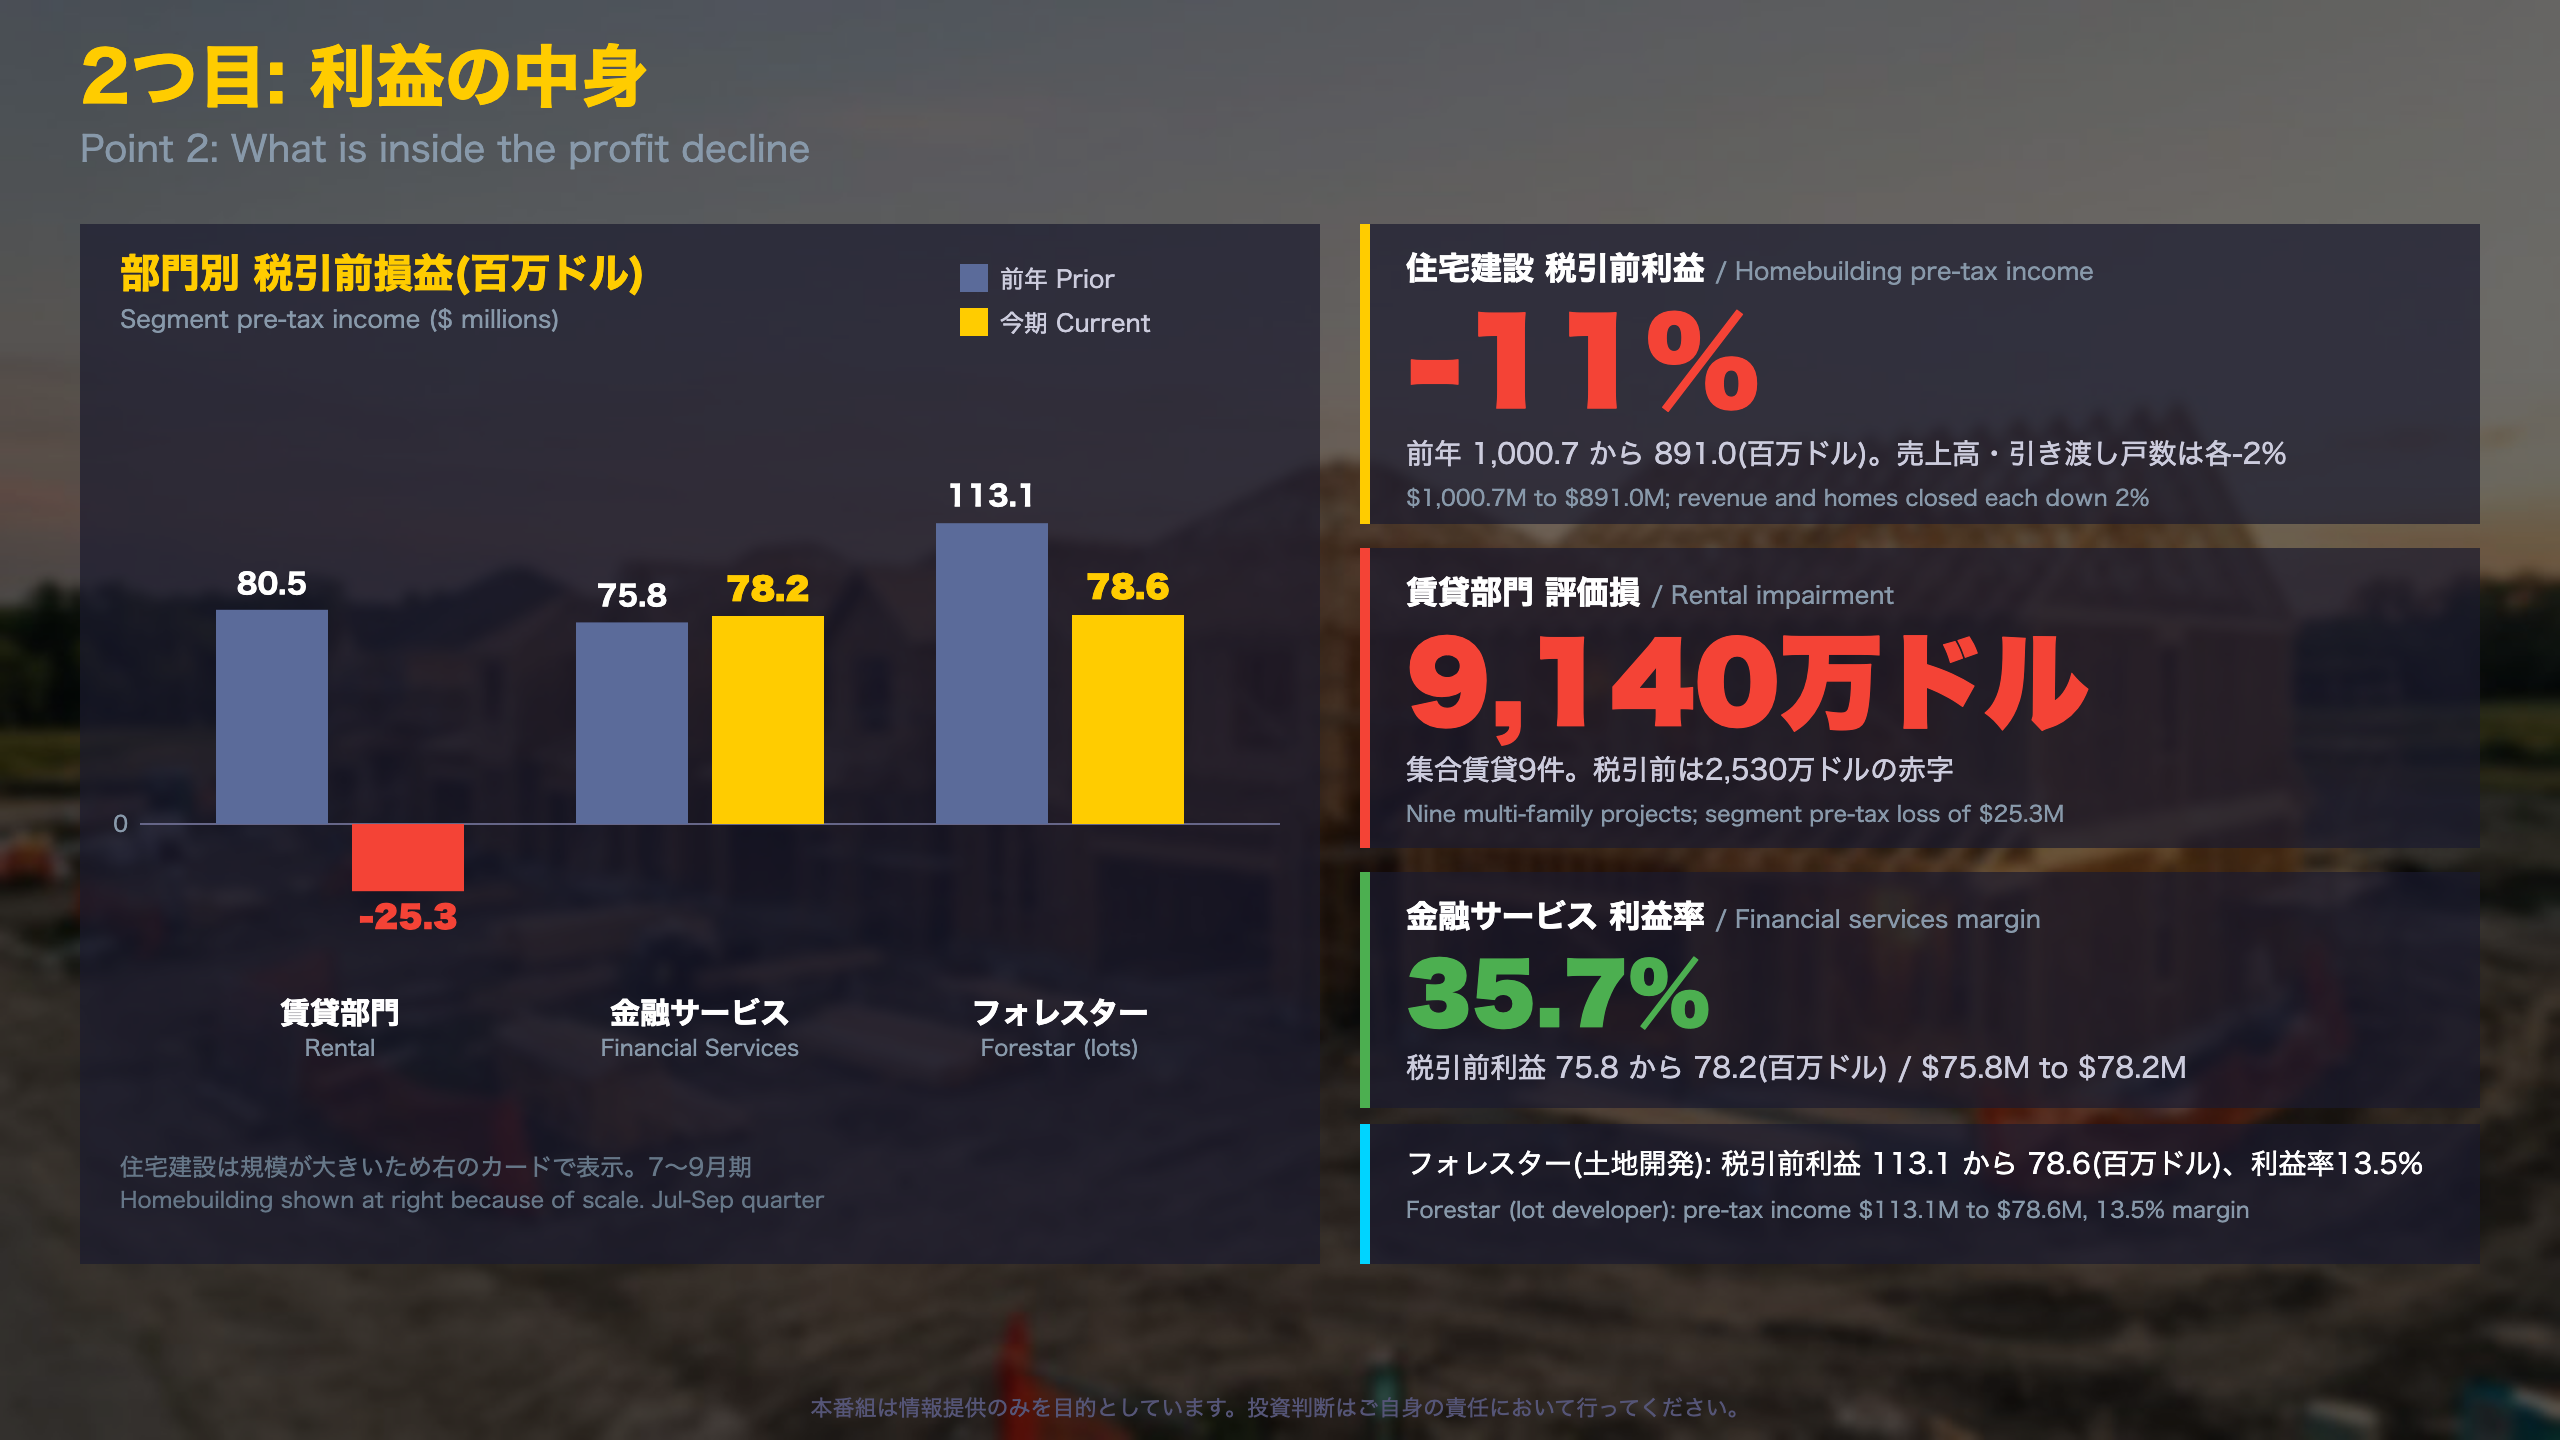
⚠️ A $91.4M impairment on nine multi-family rental projects pushed the rental segment to a pre-tax loss.
💡 FY2027 revenue guidance is $30-32B. Next report: January 19, 2027.
決算サマリー:需要の逆風と守りの強さ
What happened
D.R. Horton (NYSE: DHI), the largest US homebuilder by volume, reported fiscal fourth-quarter results (July-September 2026) on October 29. Diluted EPS was $2.67 versus $3.04 a year earlier. Revenue was $9.37 billion versus $9.68 billion, and net income attributable to the company fell 18% to $741.8 million. For the full fiscal year, EPS was $10.11 (down 13%) on revenue of $33.0 billion.
Context for readers outside the US
The fiscal year ends September 30, so this is the company’s year-end report. Unlike government releases such as housing starts or new home sales, this is company-level data: it shows what one very large builder actually sold, closed and earned. It is a useful cross-check against Census Bureau and industry surveys, but it reflects one company’s mix of markets and price points (typically $200,000 to $700,000 per home).
Two sides of the quarter
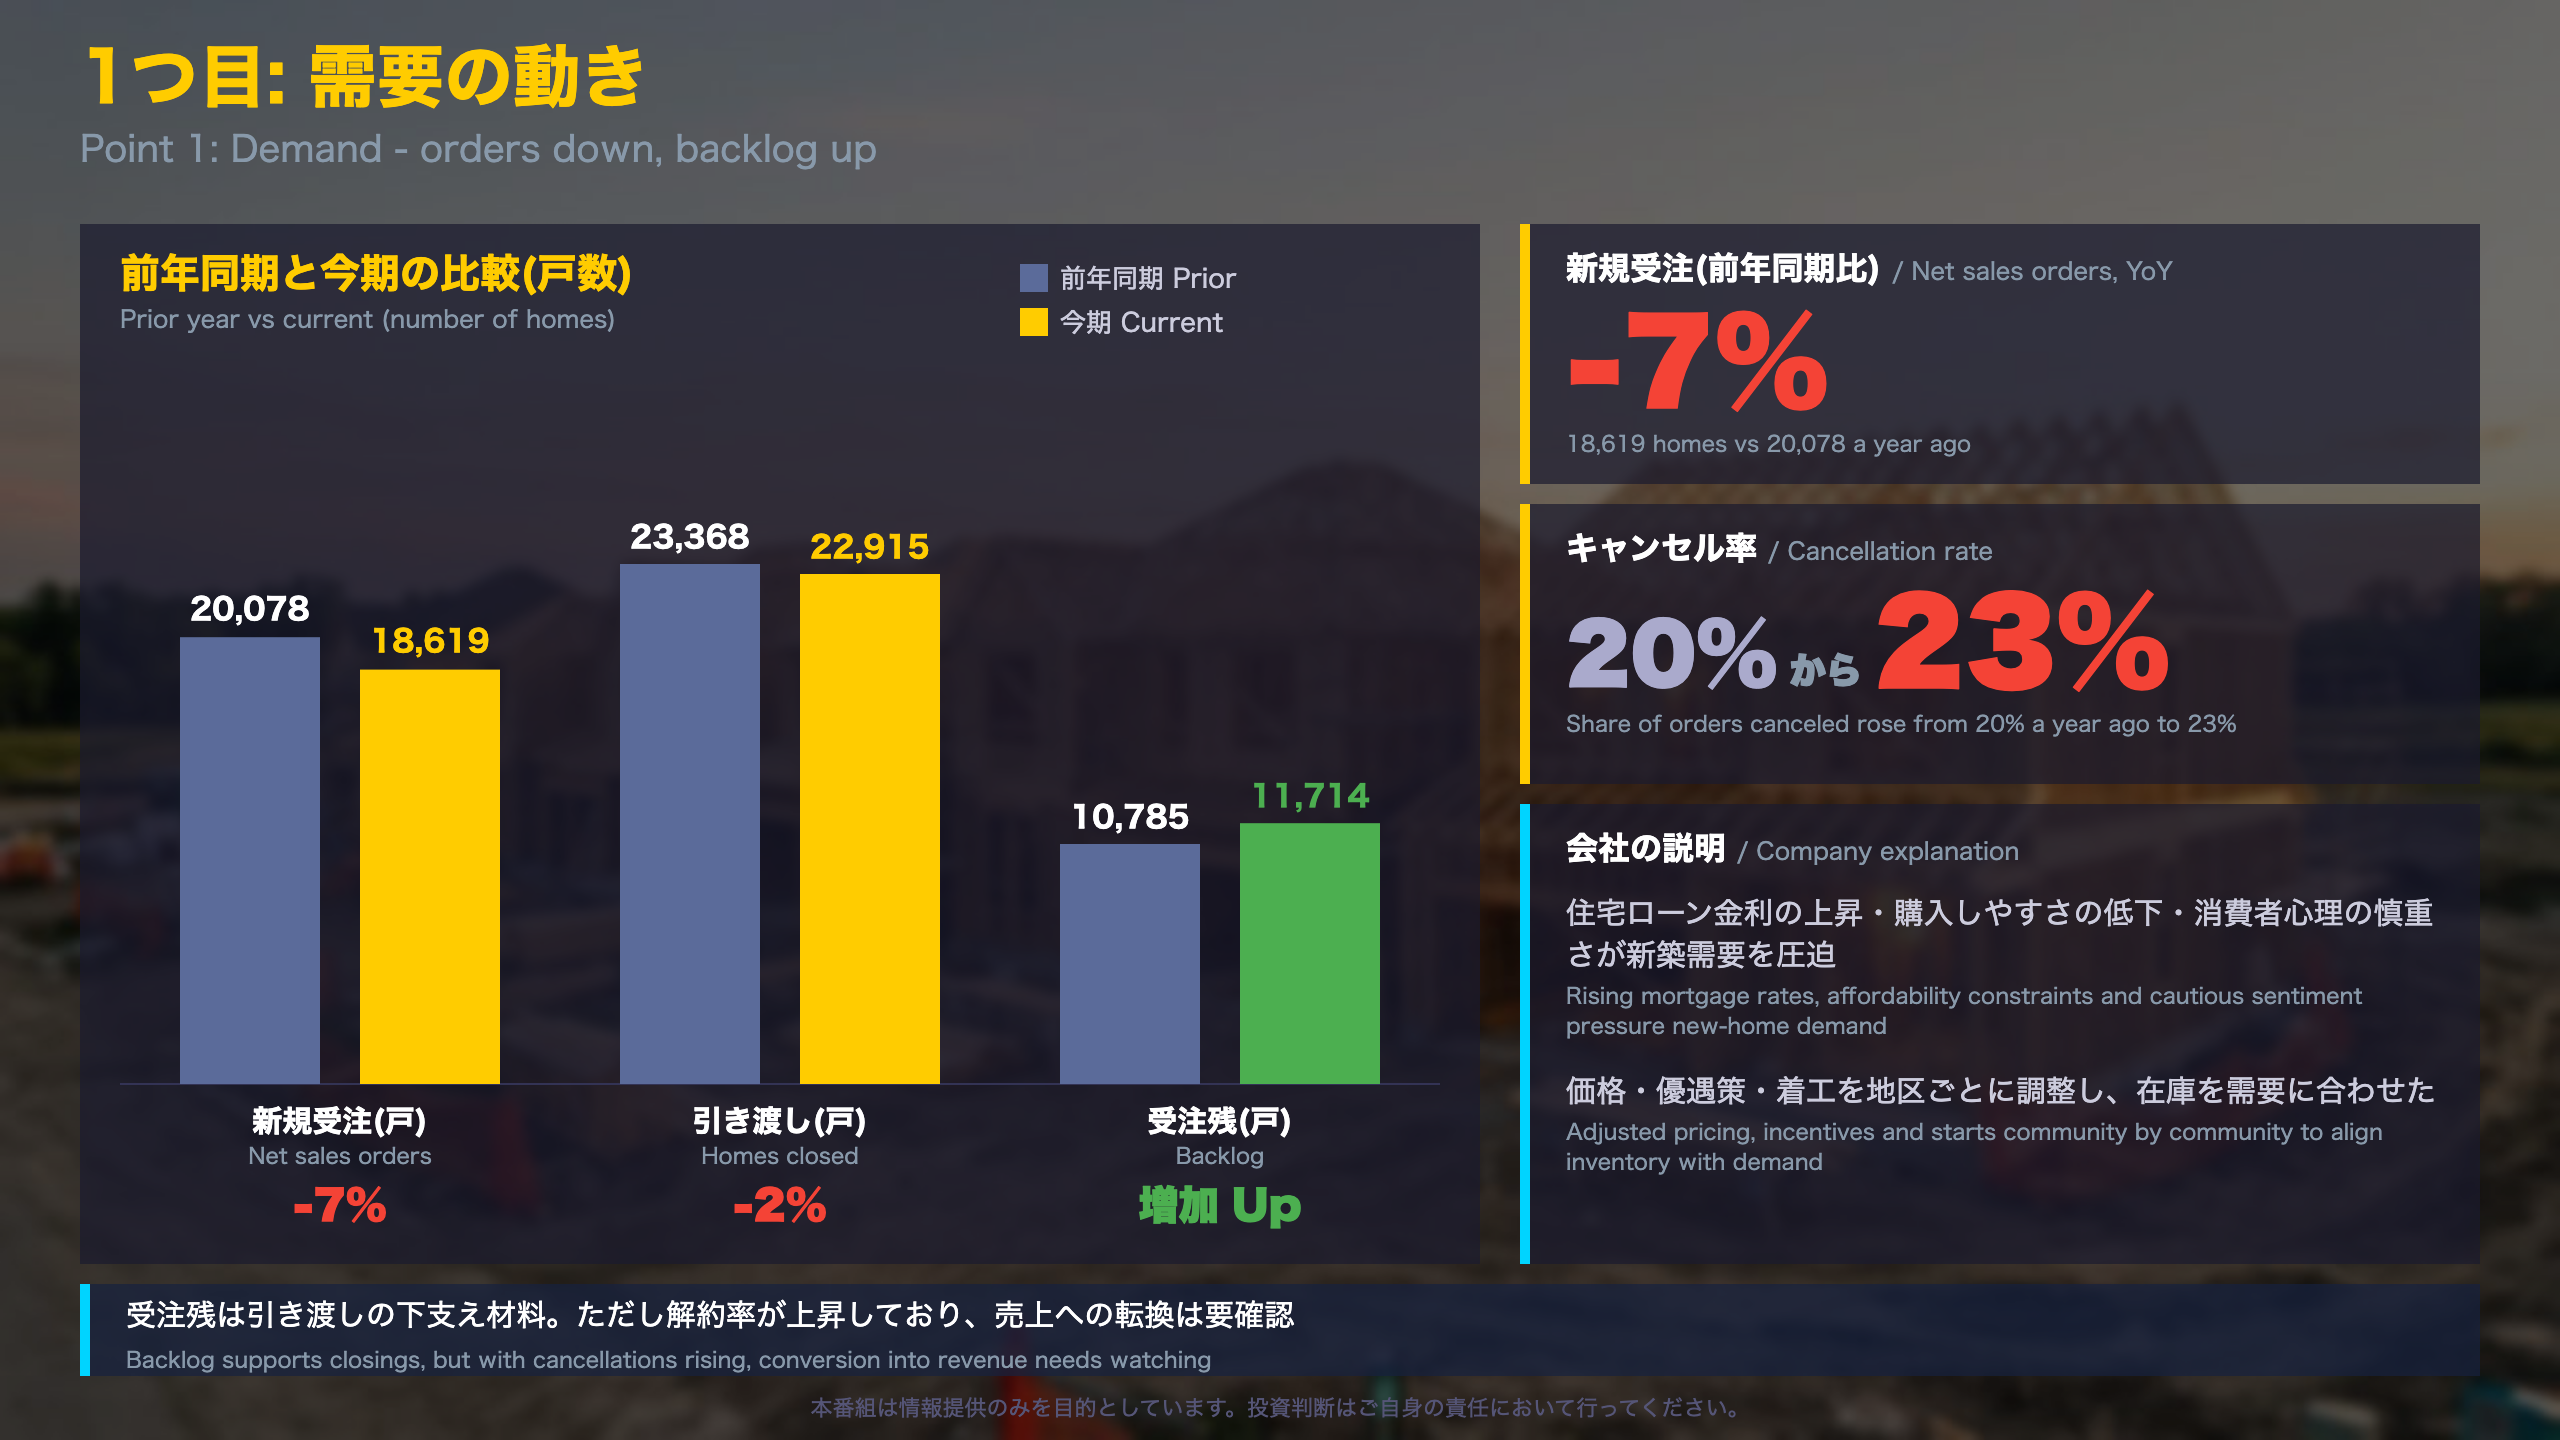
- Headwinds: Net orders fell 7% and the cancellation rate rose to 23% from 20%. The chairman cited rising mortgage rates, affordability constraints and cautious consumer sentiment.
- Resilience: Backlog rose to 11,714 homes from 10,785, debt to total capital is 20.8%, full-year operating cash flow was $3.5 billion, and $4.1 billion was returned to shareholders.
What to watch
The company will report its first fiscal 2027 quarter on January 19, 2027. Order trends, cancellations and the level of sales incentives are the data points that will show whether the demand pressure described in this release is easing or persisting. This article does not forecast prices or markets; it summarizes the release.
需要の動き:受注減と受注残
Demand: orders down, backlog up
The backlog is the key concept here. D.R. Horton recognizes a sale when a home closes, but customers sign contracts earlier. Contracts signed but not yet delivered form the backlog, which is a bridge between orders (a leading indicator) and closings (reported revenue). Japanese readers may think of it as similar to orders on hand in machinery statistics.
The numbers
- Net sales orders: 18,619 homes, down 7% from 20,078; value $6.6 billion, down 9%.
- Cancellation rate: 23% versus 20% a year ago.
- Backlog at September 30: 11,714 homes ($4.46 billion) versus 10,785 ($4.12 billion).
- Homes in inventory: 28,200 (29,600 a year earlier), of which 17,700 unsold and 8,800 completed but unsold.
Regional picture
Orders fell most in the Northwest, Southwest and South Central regions, while the North was roughly flat. Backlog rose in five of six regions, with the North up from 2,111 to 2,576 homes.
Reading the data
The company’s explanation is explicit: rising mortgage rates, affordability constraints and cautious consumer sentiment pressured new-home demand, and it adjusted incentives, pricing and starts community by community. It expects incentives to remain elevated in fiscal 2027.
For comparison, US government data (Census new home sales, NAHB sentiment) capture the whole market, whereas this release shows a single national builder. Full-year orders rose 2% to 84,995 homes, so the fourth-quarter decline should not be read as a full-year trend. The open question is conversion: with cancellations higher, how much of the larger backlog turns into closings will be visible in upcoming quarters.
利益の中身:減益の内訳
Inside the profit decline
The consolidated pre-tax margin was 10.8% in the quarter. To see why profit fell more than volume, it helps to look at the segment structure, which is unusual compared with a typical US homebuilder: D.R. Horton owns a mortgage and title business, a majority stake in a lot developer (Forestar), and a rental operation.
| Segment (Jul-Sep, $M) | Pre-tax income | Prior year |
|---|---|---|
| Homebuilding | 891.0 | 1,000.7 |
| Rental | -25.3 | 80.5 |
| Forestar | 78.6 | 113.1 |
| Financial services | 78.2 | 75.8 |
Key points
- Homebuilding: revenue and closings each fell 2%, pre-tax income fell 11%, with a 10.6% margin. SG&A rose to $989.0 million from $970.9 million on a consolidated basis.
- Rental: the company stated that results include $91.4 million of inventory impairment charges related to nine multi-family rental projects. Excluding that charge is not possible from the release alone, and the release does not say whether further charges will follow.
- Financial services: a 35.7% pre-tax margin, a steady contributor, but small relative to homebuilding profit.
- Forestar: sold 5,004 lots and earned a 13.5% margin; 68% of fiscal 2026 closings were on lots developed by Forestar or third parties.
Why it matters
An impairment is an accounting write-down of assets whose carrying value exceeds recoverable value, so it signals pressure on that business line, not a cash outflow in the quarter. Readers comparing with Japanese developers should note that US builders typically hold less land on balance sheet and rely more on lot options. The full-year rental segment remained profitable at $18.2 million, so one quarter should not define the whole business.
質疑:来期見通しと株主還元
FY2027 guidance in context
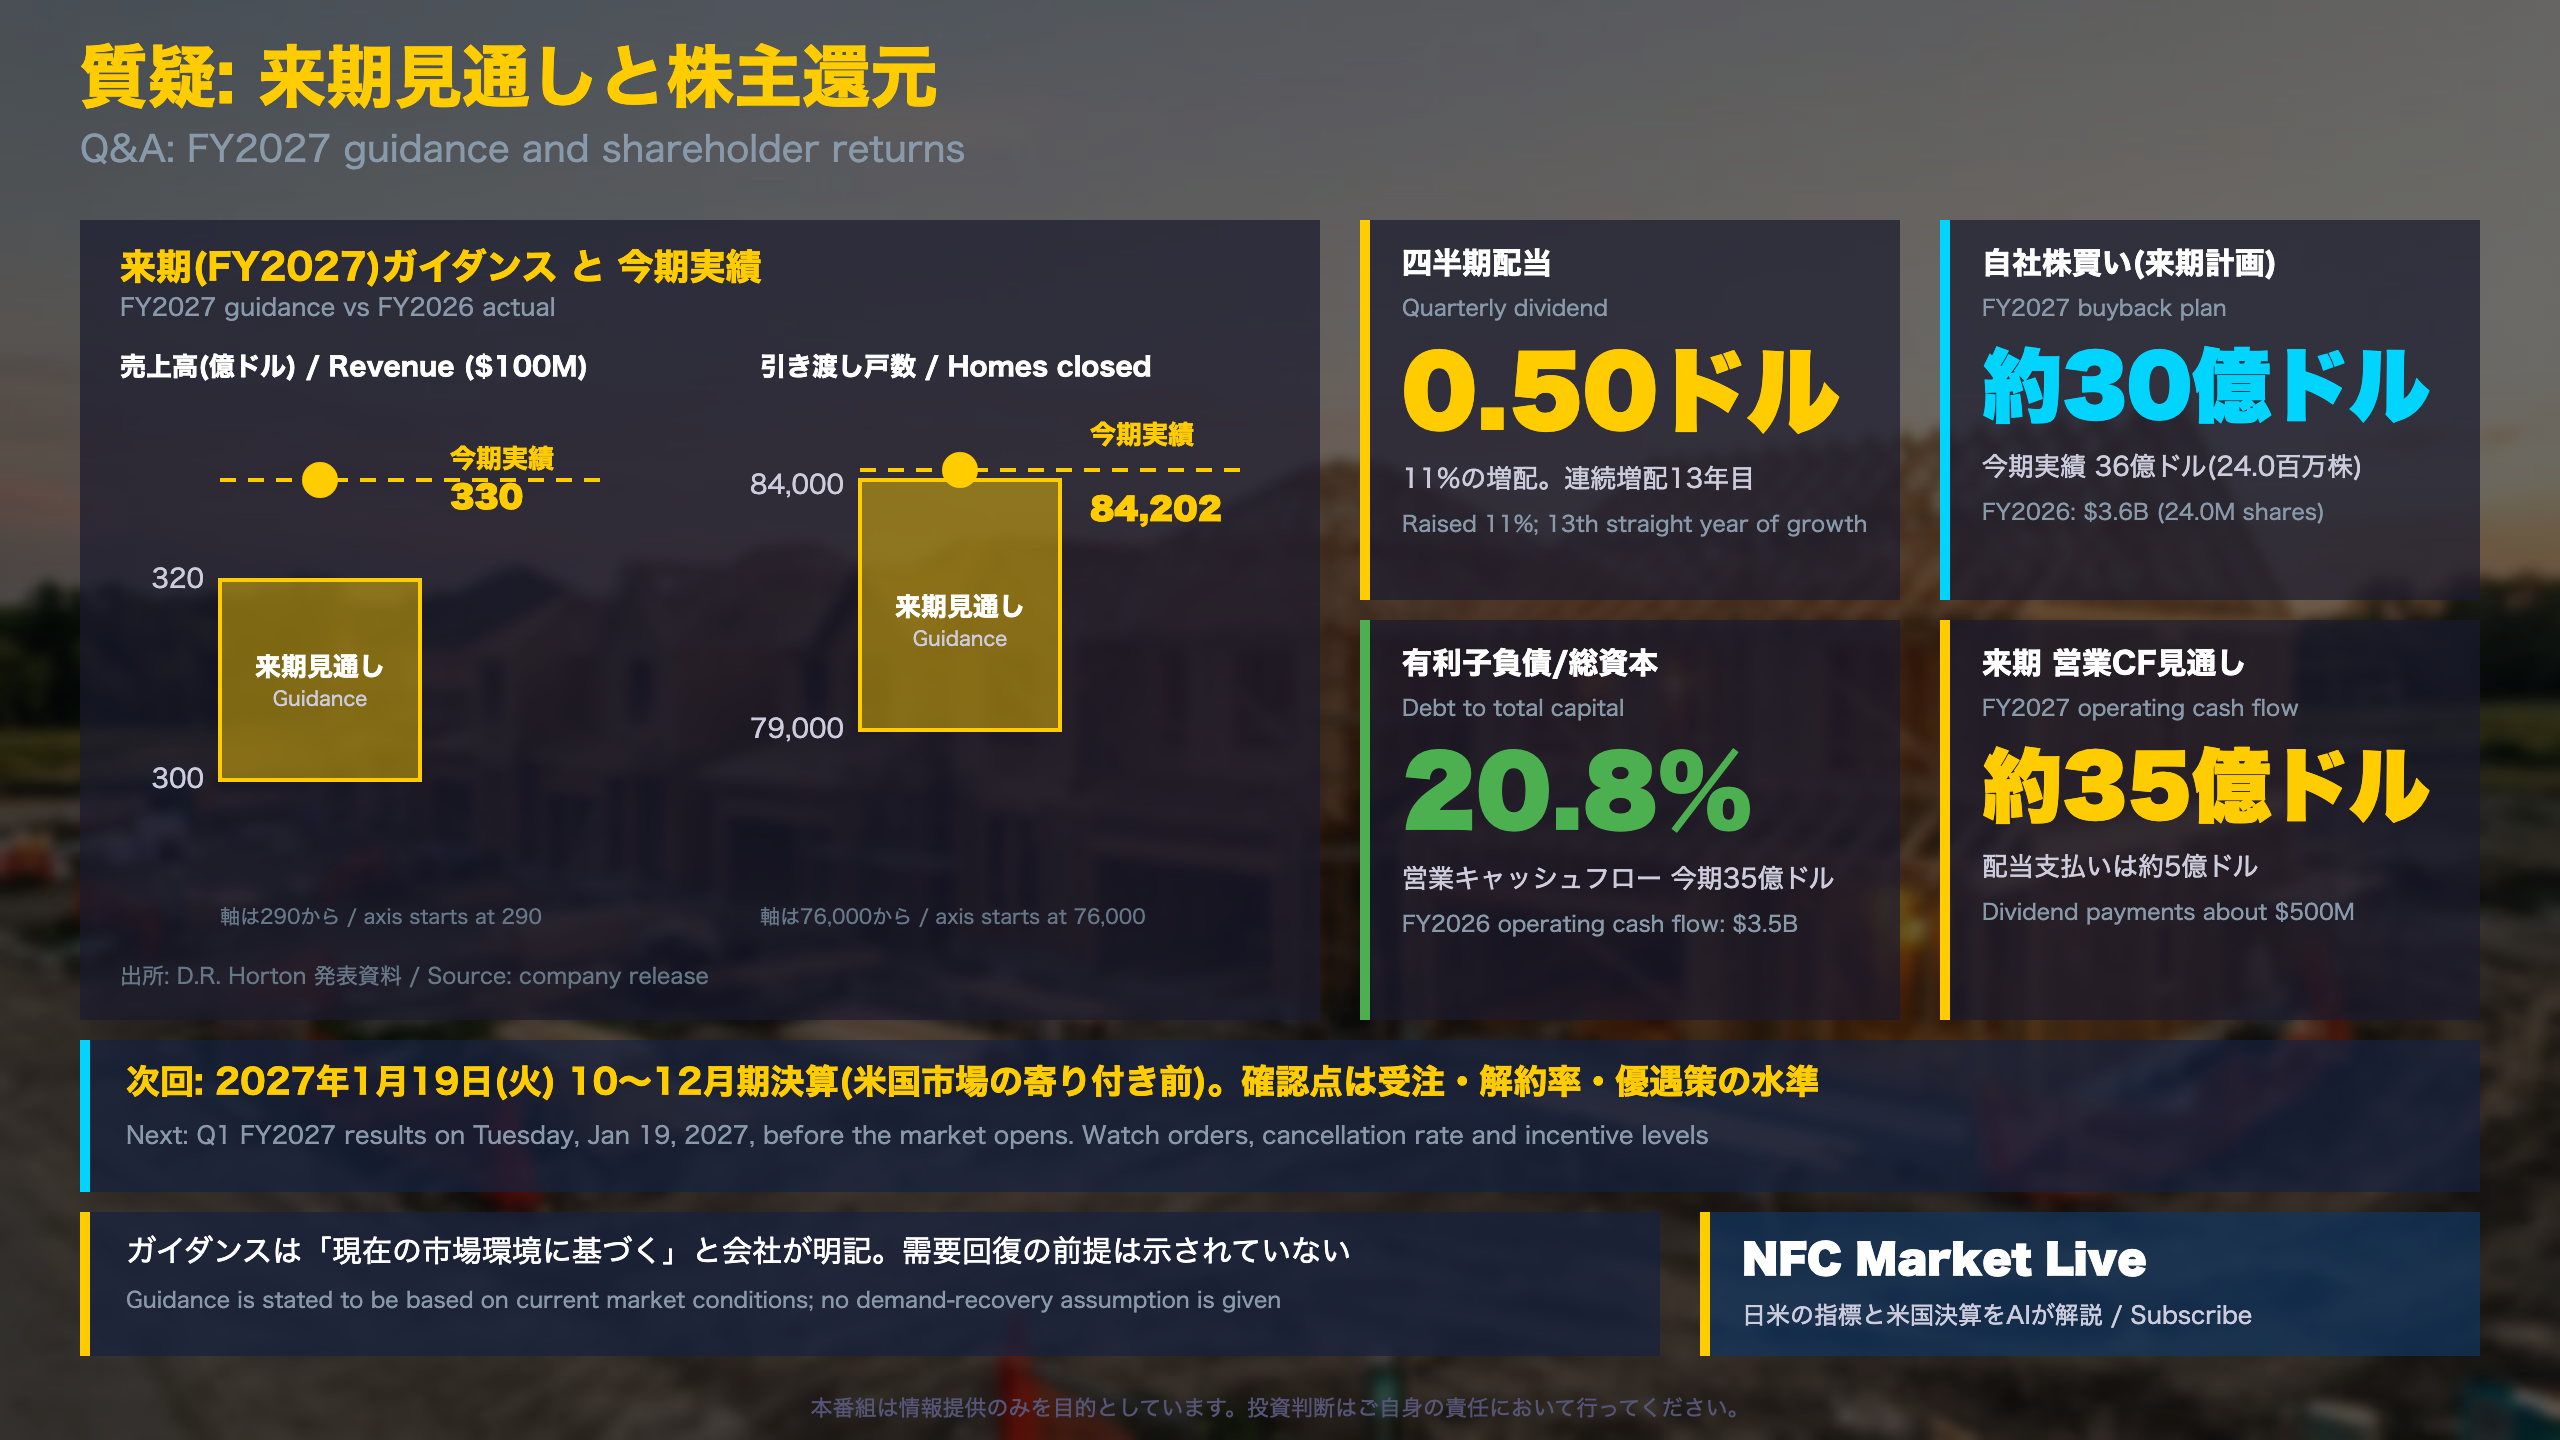
This was D.R. Horton’s first guidance for fiscal 2027 (October 2026-September 2027). The company said it is based on current market conditions and that incentives are expected to remain elevated.
| Item | FY2027 guidance | FY2026 actual |
|---|---|---|
| Consolidated revenue | $30.0-32.0B | $33.0B |
| Homes closed | 79,000-84,000 | 84,202 |
| Tax rate | about 25.5% | not stated |
| Operating cash flow | about $3.5B | $3.5B |
| Share repurchases | about $3.0B | $3.6B |
| Dividends | about $500M | $513M |
Balance sheet and capital return
Total liquidity was $7.2 billion, debt to total capital 20.8%, and the company repaid $600 million of 1.3% senior notes in October 2026 with no other senior note maturities in fiscal 2027. It repurchased 24.0 million shares in the year (shares outstanding down 8% to 271.4 million) with $4.7 billion of authorization remaining. The quarterly dividend rises 11% to $0.50 per share, the thirteenth consecutive year of dividend growth.
Two readings
- Cautious: the upper end of the closings range only matches this year’s level, and revenue guidance sits below the FY2026 total.
- Resilient: backlog is above last year, leverage is low, and the dividend and buyback plans continue.
For readers used to Japanese corporate disclosure, note that US companies often give annual guidance at the year-end release and update it quarterly; the company said it will add first-quarter guidance on today’s call. This analysis does not forecast the stock or the housing market.
Calendar
Q1 FY2027: Jan 19, 2027; Q2: Apr 20; Q3: Jul 22; Q4 and full year: Oct 26, all before the market opens.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.