This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-11-11 06:25 JST)
📊 Firefly Aerospace (FLY) Q3 2026 results explained.
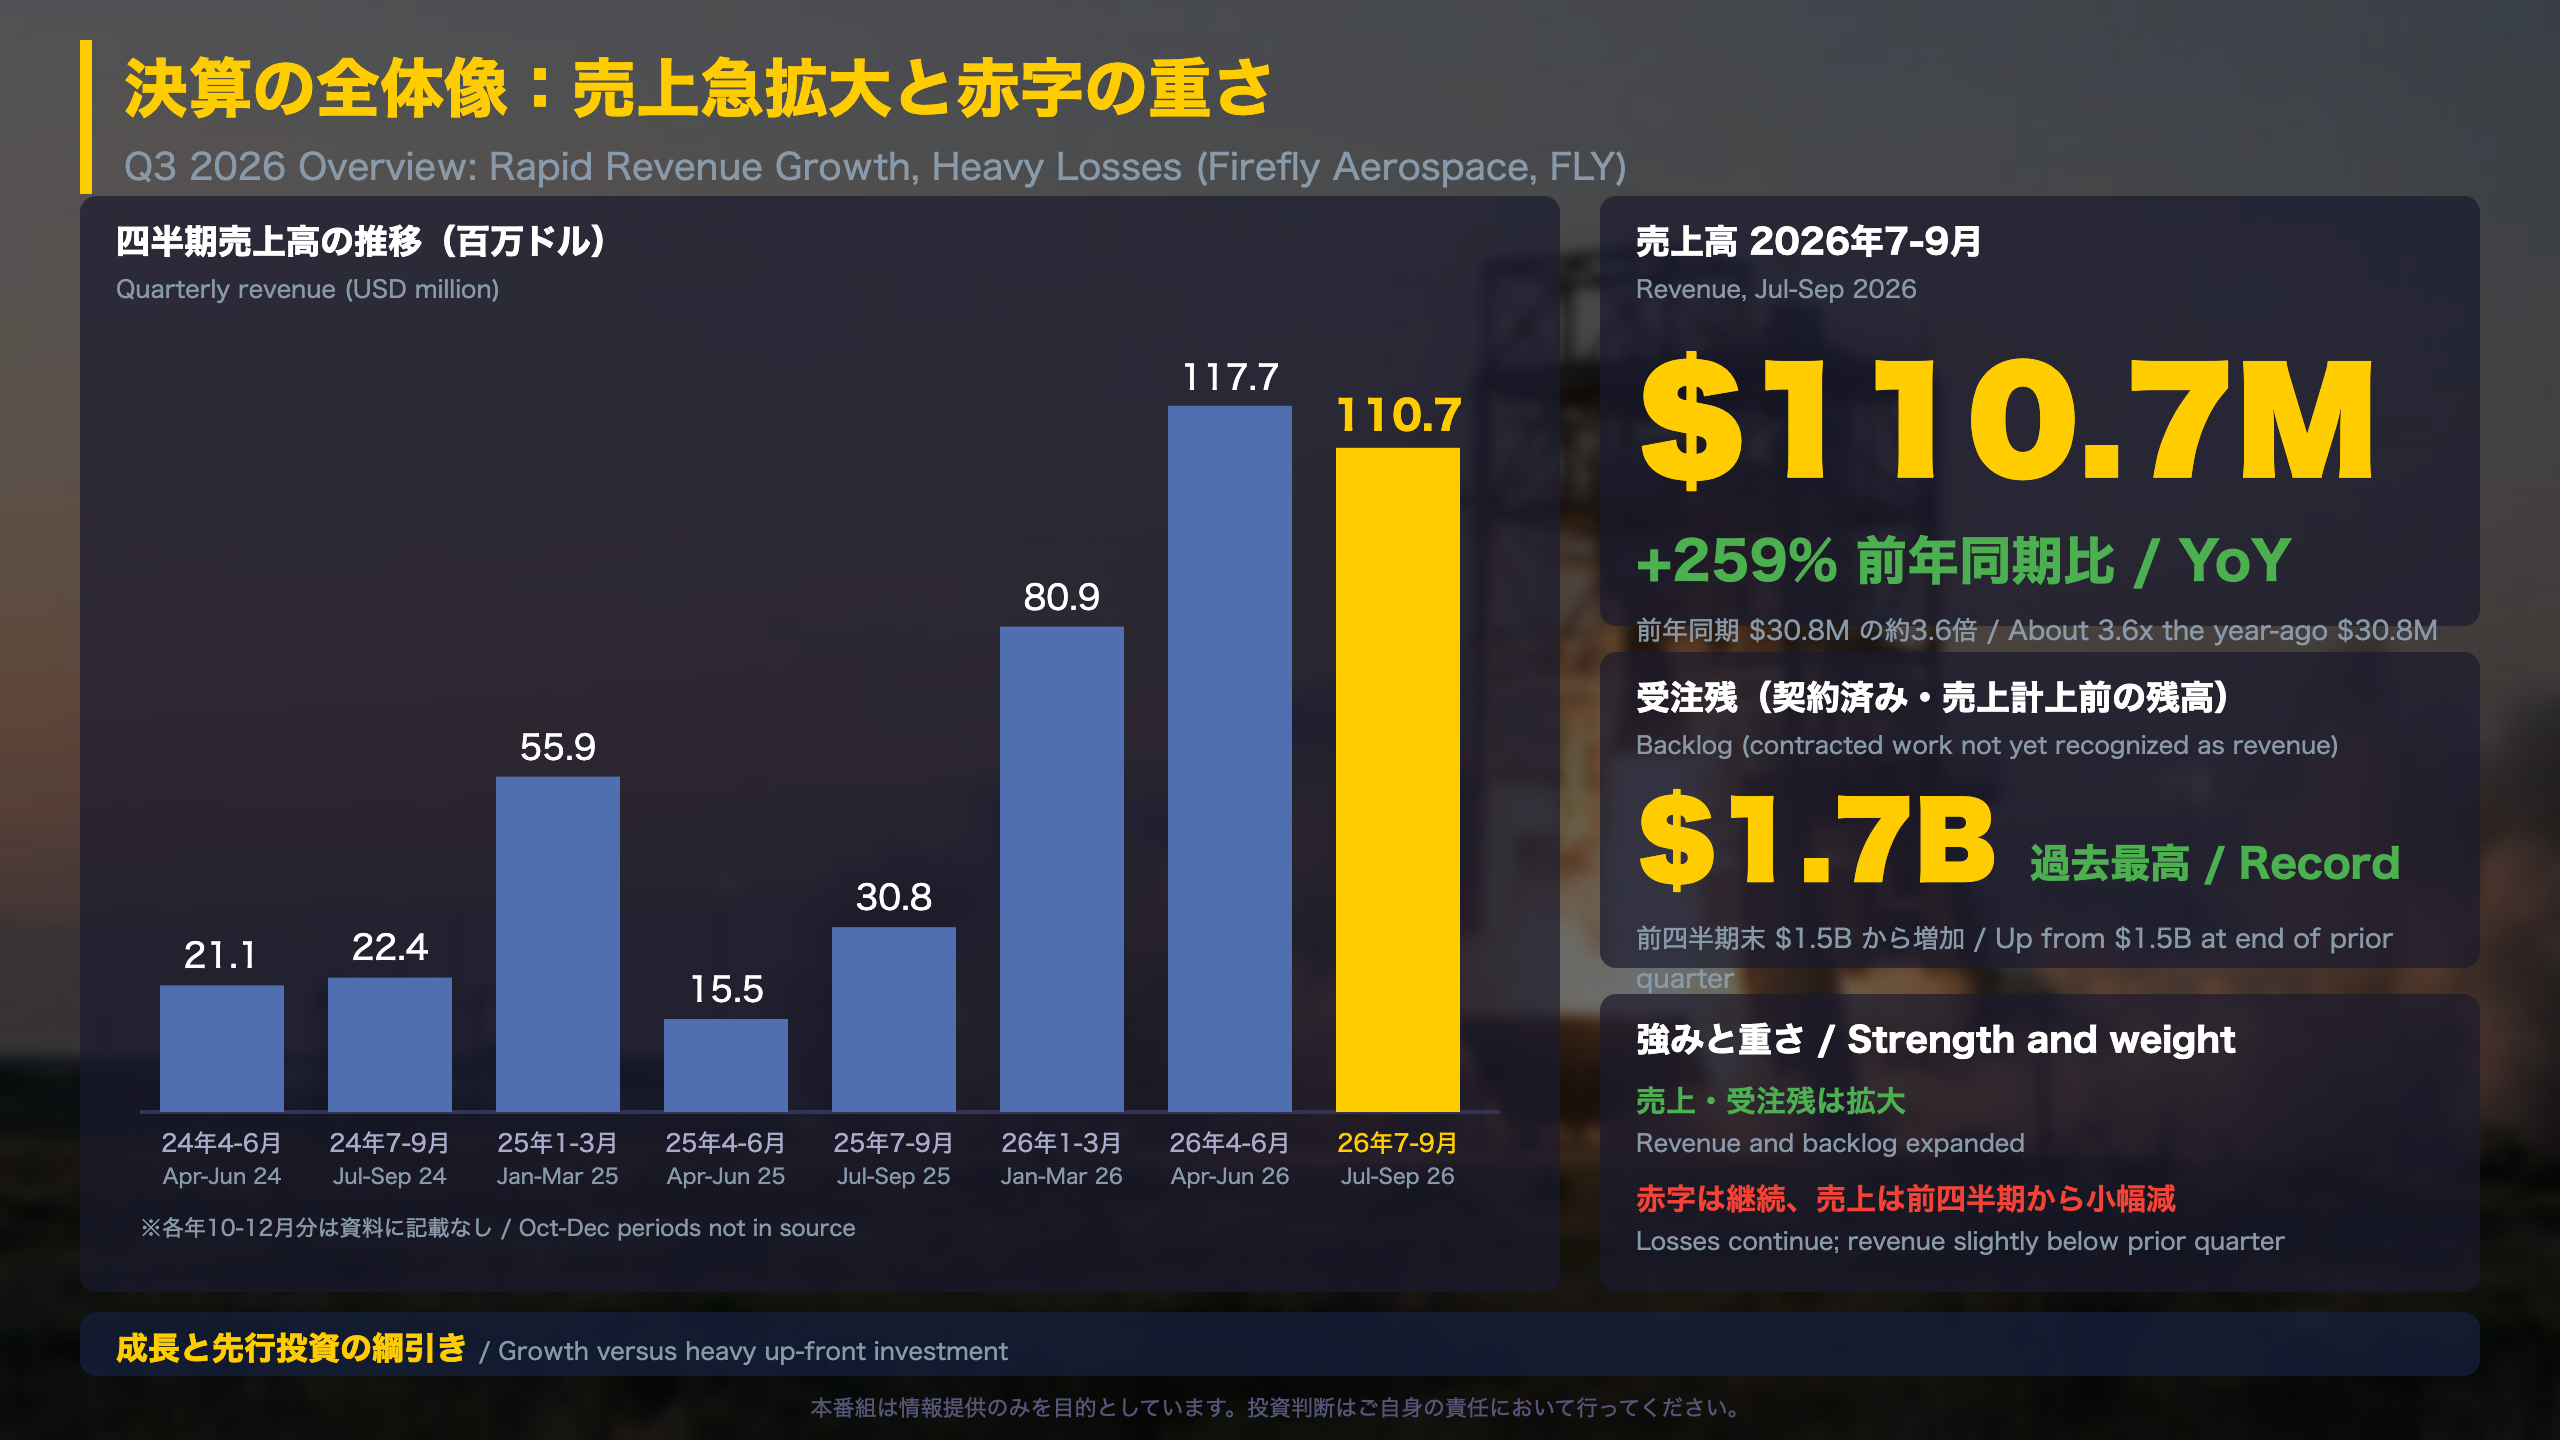
📈 Revenue was $110.7M, up 259% year over year, and backlog hit a record $1.7B.
📉 Operating loss was $101.6M and free cash flow was -$85.3M.
💡 Net loss narrowed mainly because last year’s warrant valuation and debt extinguishment losses did not recur. Cash and short-term investments total about $535M.
⚠️ Full-year revenue guidance is $440M-$450M, so Q4 revenue is the next checkpoint.
決算の全体像:売上急拡大と赤字の重さ
Firefly Aerospace Q3 2026: Growth at Scale, Losses Still Heavy
Who is Firefly? Firefly Aerospace (Nasdaq: FLY) is a Texas-based space and defense technology company. Its businesses span launch (the Alpha rocket, with Eclipse in development), lunar landers (Blue Ghost), orbital vehicles (Elytra) and national-security software through SciTec. The results come from an SEC filing, so figures follow US GAAP, with non-GAAP reconciliations provided.
Headline numbers (quarter ended Sept 30, 2026)
– Revenue: $110.7M vs $30.8M a year earlier (+259%)
– Gross profit: $25.3M (gross margin about 23% vs about 28%)
– Operating loss: $101.6M, about 92% of revenue vs about 202% a year ago
– GAAP EPS: -$0.56 (non-GAAP -$0.45)
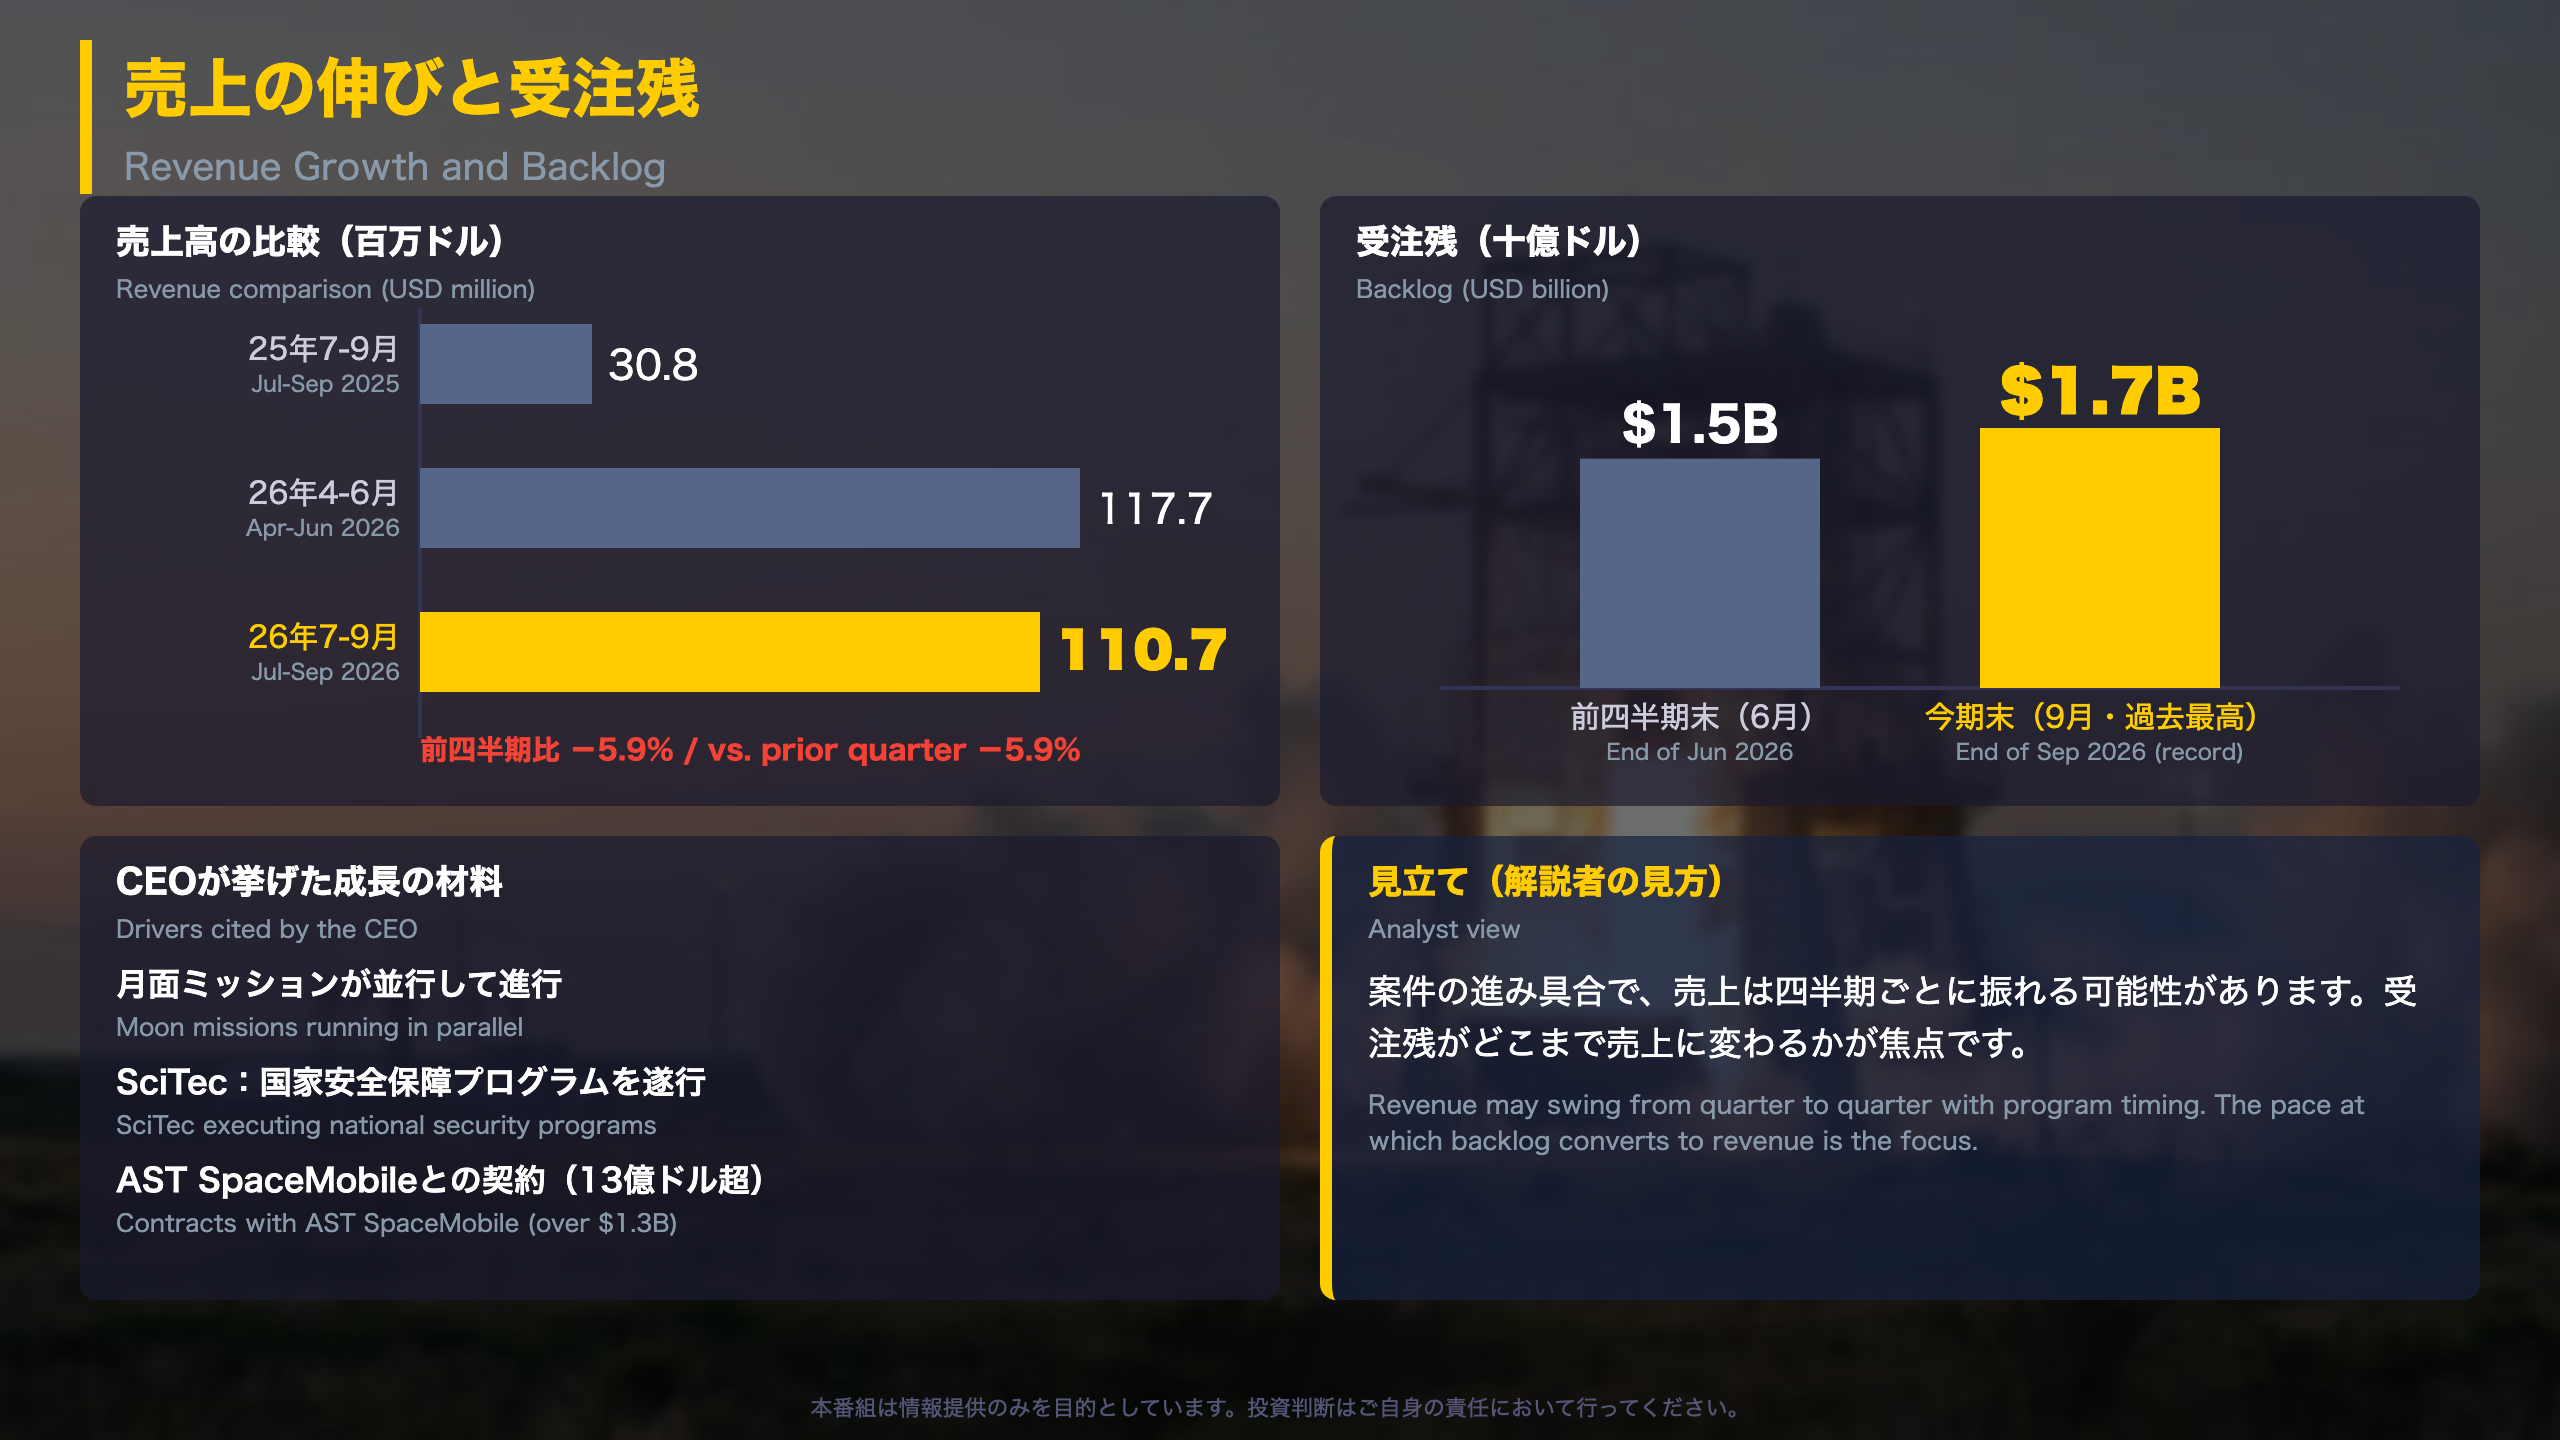
– Backlog: a record $1.7B, from $1.5B in the prior quarter
Why GAAP net loss looks better. The year-ago quarter carried a $42.2M warrant fair-value loss and a $30.4M debt extinguishment loss; neither recurred. Weighted shares also rose from 93.8M to 168.4M, which mechanically lowers per-share losses.
What investors may weigh. Positives: scaled-up revenue, a record backlog, and a loss that is shrinking relative to sales. Cautions: revenue edged down about 6% from the prior quarter’s $117.7M, and the absolute operating loss widened. The release gives no consensus comparison, and this note does not use one.
売上の伸びと受注残
Backlog and Contract Wins: What Sits Behind $1.7B
Backlog is the value of contracted work that has not yet been recognized as revenue. Firefly ended September at a record $1.7B, up from $1.5B at the end of June.
Contracts cited by the company
– Lockheed Martin: extension of a multi-launch agreement for up to 25 Alpha launches through 2031 (Block II configuration)
– SSC Space: two commercial Alpha launches from Esrange, Sweden, Firefly’s first European launch contracts
– U.S. Space Force: a $94M Ground-Based Radar Digitization award, plus onboarding to the $981M NITE-STAR IDIQ vehicle
– NASA JPL: a $13M subcontract for the SkyFall aeroshell, Firefly’s first Mars award
– Recent highlights: contracts above $1.3B with AST SpaceMobile (licensed IP, engine delivery, engineering support)
Reading the labels carefully. An IDIQ (indefinite-delivery, indefinite-quantity) contract, or a vendor slot in NASA’s CLPS 2 program, is a ticket to compete for task orders, not guaranteed revenue. The release does not say how much of the backlog is firm.
Revenue cadence. Quarterly revenue ran $80.9M (Jan-Mar), $117.7M (Apr-Jun) and $110.7M (Jul-Sep), a dip of about 6% sequentially. Nine-month revenue of $309.2M is roughly 3x the year-ago $102.2M.
Two readings. Constructive: backlog rose and the customer base is broad across NASA, the Space Force and commercial buyers, including Japan’s Synspective (up to 10 launches through 2030). Cautious: revenue timing depends on program milestones, so quarterly figures can be uneven.
赤字の中身と手元資金
Reading the Loss: GAAP vs Non-GAAP, and Liquidity
Non-GAAP figures strip out items such as stock-based compensation, amortization of acquired intangibles and transaction costs. The company supplies reconciliations to GAAP, and warns they are not a substitute for GAAP.
What changed in the loss (Q3 2026 vs Q3 2025)
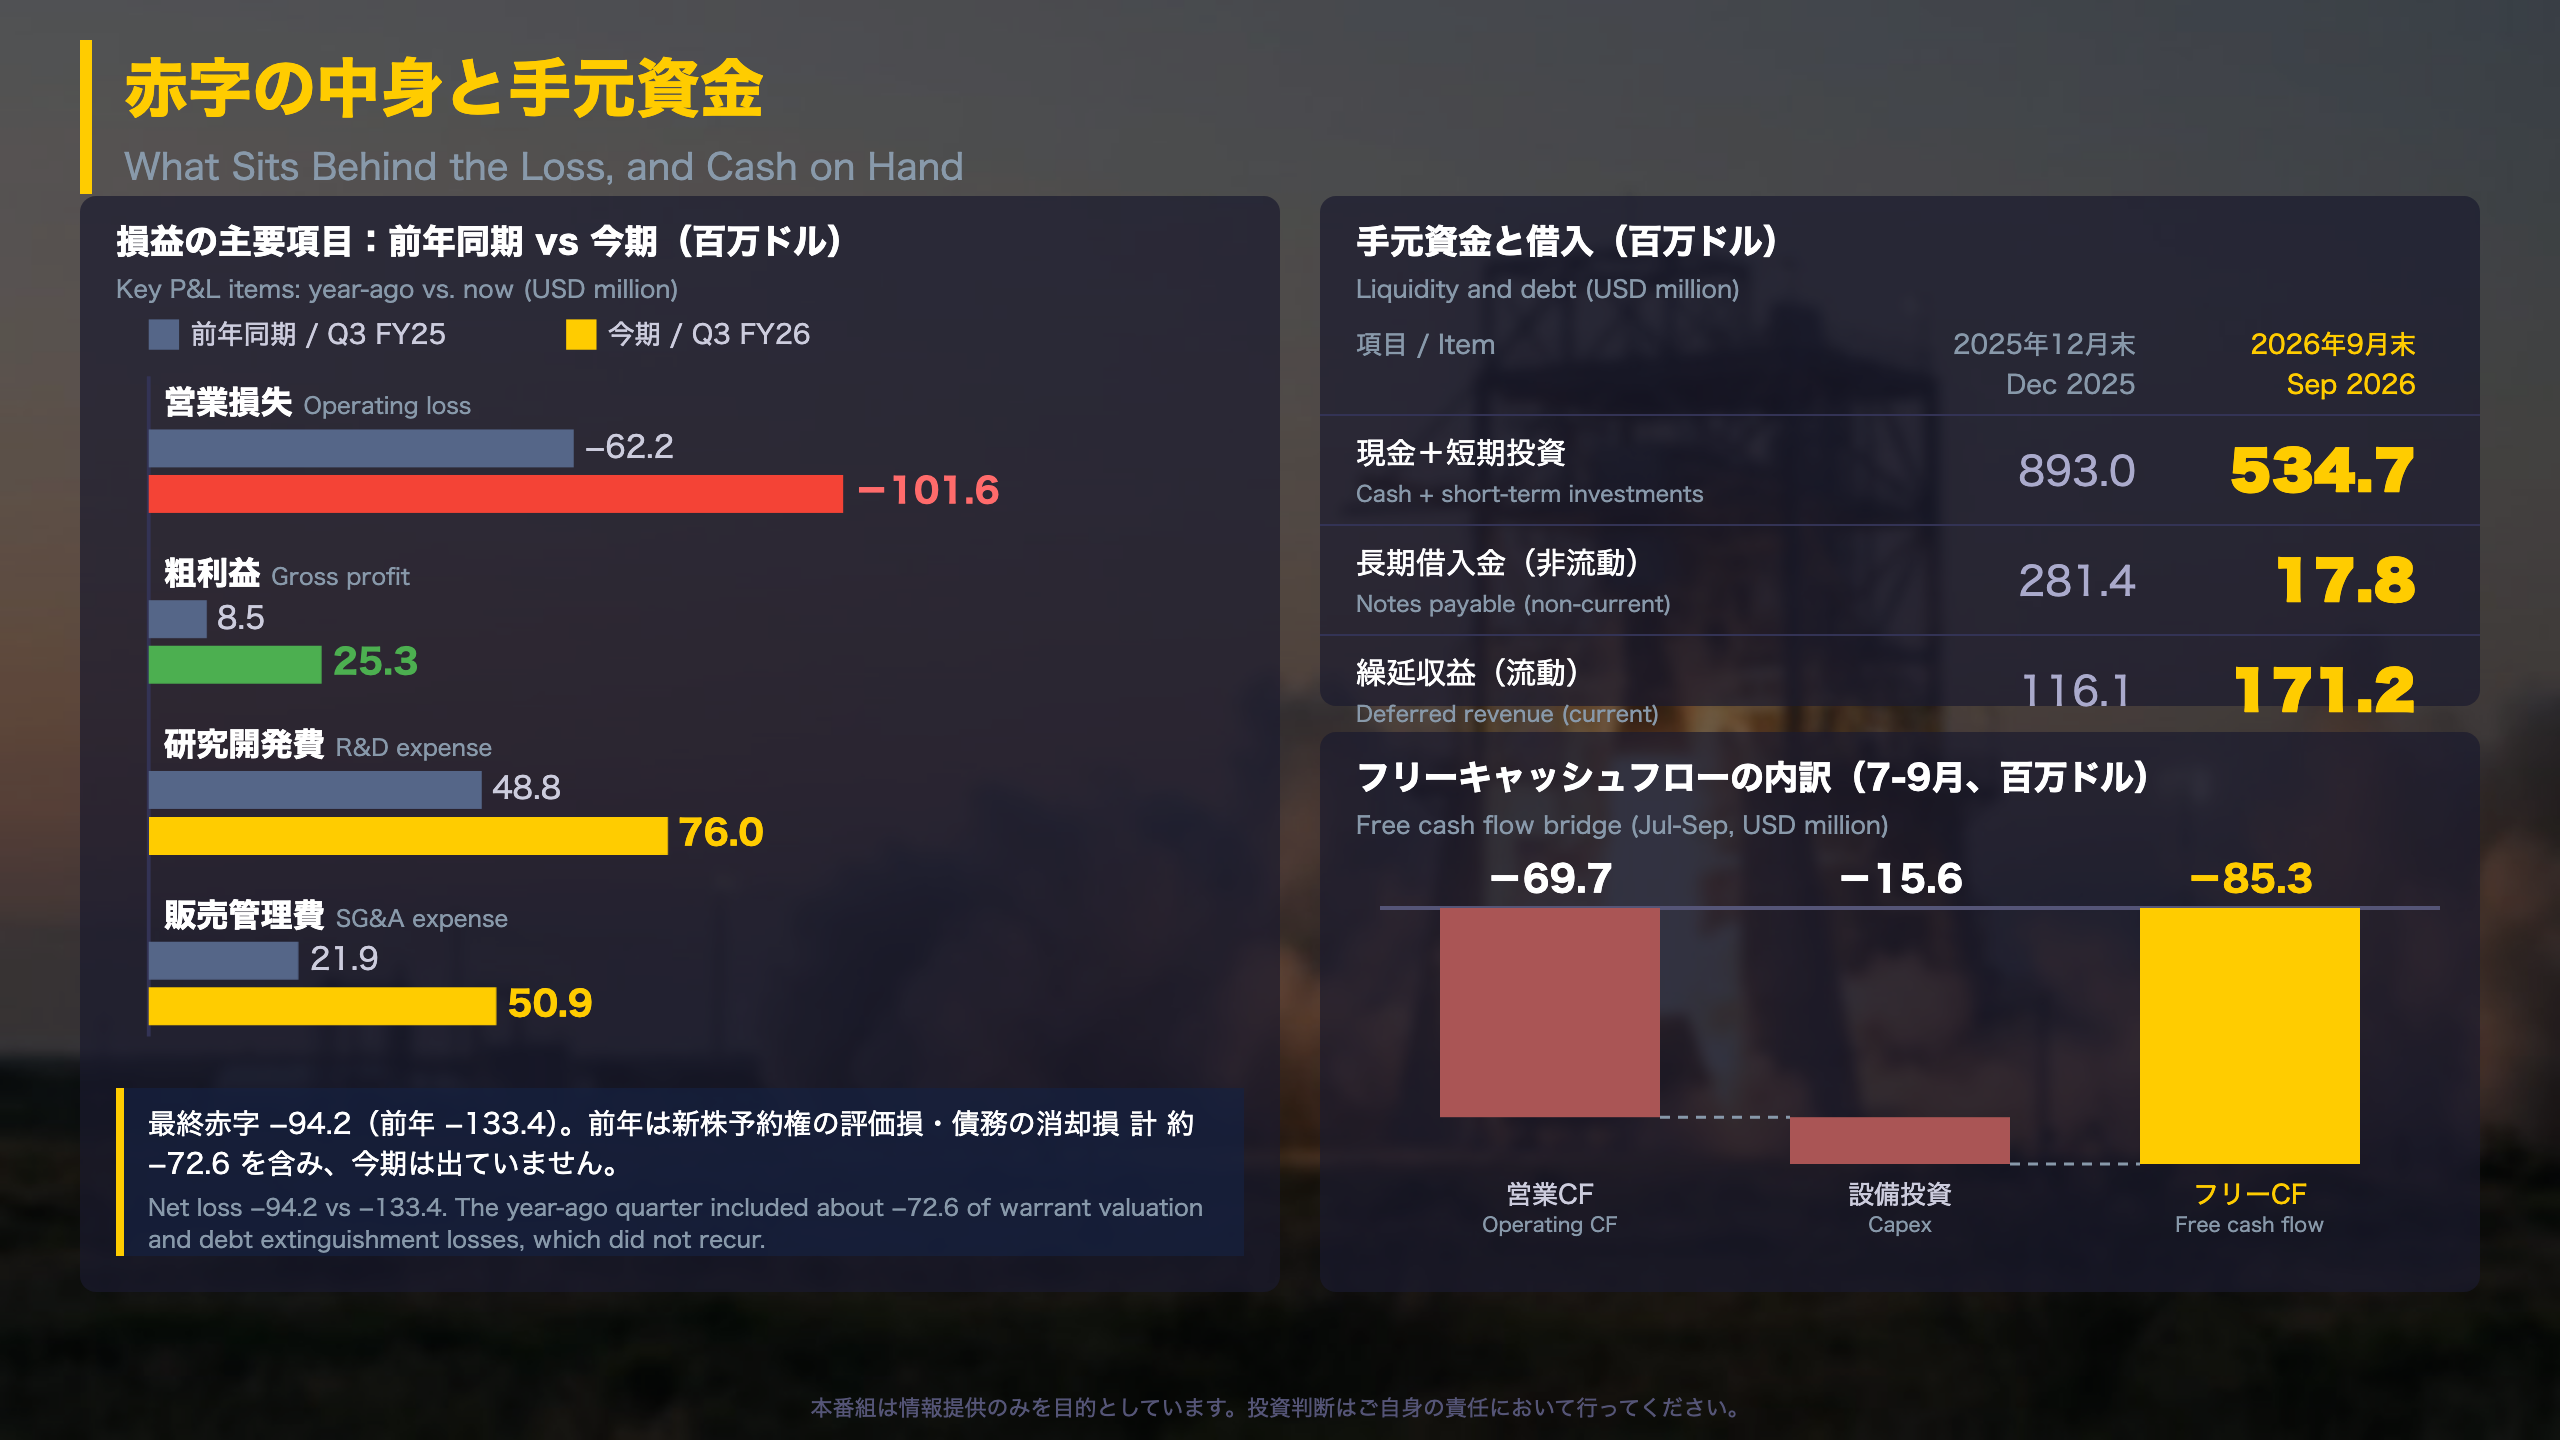
– GAAP operating loss: $101.6M vs $62.2M; non-GAAP: $78.7M vs $52.8M
– R&D: $76.0M (+56%); SG&A: $50.9M (+132%)
– GAAP EPS: -$0.56 vs -$1.50; non-GAAP: -$0.45 vs -$0.55. Weighted shares rose from 93.8M to 168.4M
– Net loss narrowed to $94.2M from $133.4M mainly because a $42.2M warrant loss and a $30.4M debt extinguishment loss in the prior-year quarter did not recur
Liquidity
– Cash fell to $409.3M from $793.0M at December 2025; short-term investments were $125.4M
– In nine months the company repaid a $260M revolver and raised $184.1M from stock issuance. Non-current notes payable fell to $17.8M from $281.4M
– Free cash flow was -$85.3M in Q3 and -$270.5M over nine months
Two readings. Constructive: debt has been largely retired and current deferred revenue rose to $171.2M from $116.1M (the part due to be recognized within a year). Cautious: cash burn continues, and non-current deferred revenue fell, so total deferred revenue was only modestly higher. Investors comparing US GAAP results with Japanese filings should note that US firms commonly emphasize non-GAAP measures alongside GAAP.
質疑で深める:通期見通しと次の確認点
Guidance Math and What to Watch
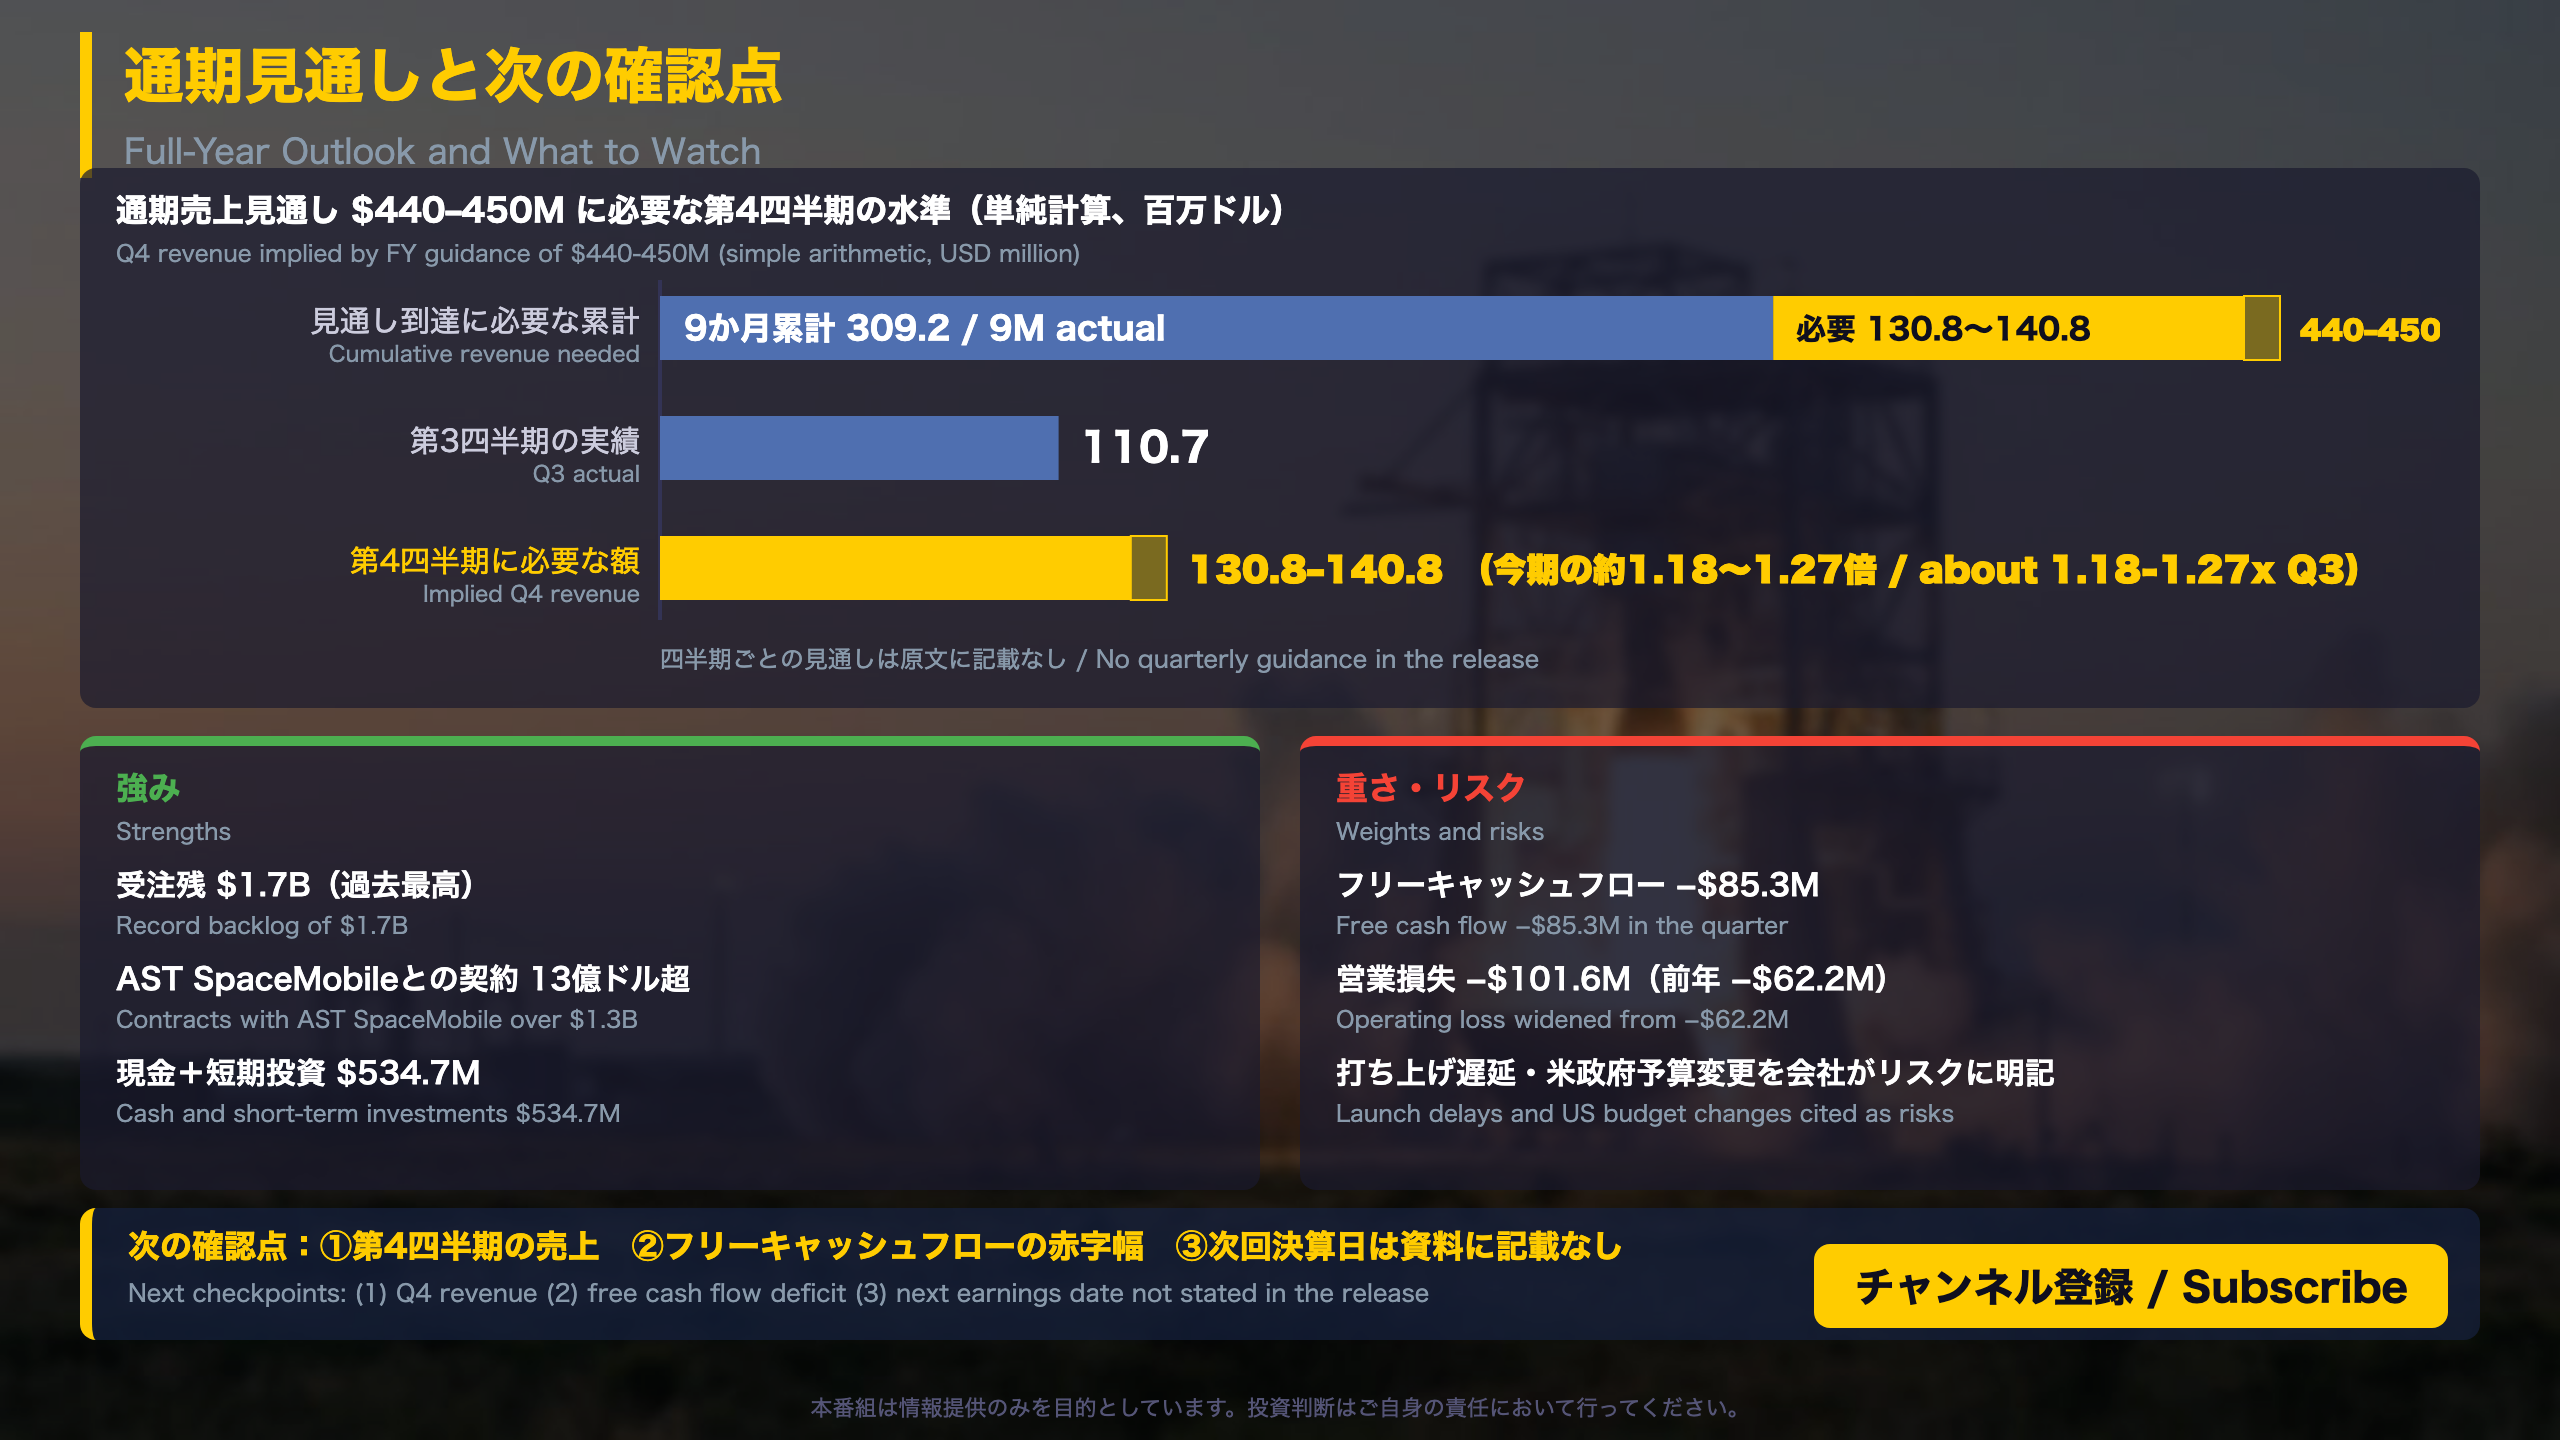
Firefly guides only to full-year revenue: $440M to $450M for 2026. It gives no quarterly guidance, and the release does not cite analyst consensus; neither does this note.
| Item | USD mn |
|---|---|
| Nine-month revenue | 309.2 |
| Needed in Q4 (low end) | about 130.8 |
| Needed in Q4 (high end) | about 140.8 |
| Q3 revenue | 110.7 |
Simple arithmetic implies Q4 revenue roughly 18-27% above Q3.
Risks listed by the company: launch delays or failures, Alpha launch cadence and Eclipse development, changes in U.S. government funding, timely delivery to AST SpaceMobile, and realization of backlog.
Progress markers: more than 170 hot-fire tests in the Miranda engine qualification campaign (a step toward the first Eclipse launch); a third hypersonic task order for Alpha; completion of the MoonFall preliminary design review and the Blue Ghost South Pole critical design review.
Two readings. Constructive: a $1.7B backlog and about $535M of cash and short-term investments give runway. Cautious: nine-month free cash flow of -$270.5M is shrinking that cushion.
Watch list: (1) Q4 revenue versus the implied $131-141M range; (2) free cash flow burn (Q3: -$85.3M); (3) launch timing disclosures for Alpha Block II and Eclipse. The next earnings date is not stated in the release.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.