This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-11-11 06:25 JST)
📊 CoreWeave (CRWV) Q3 2026 results explained.
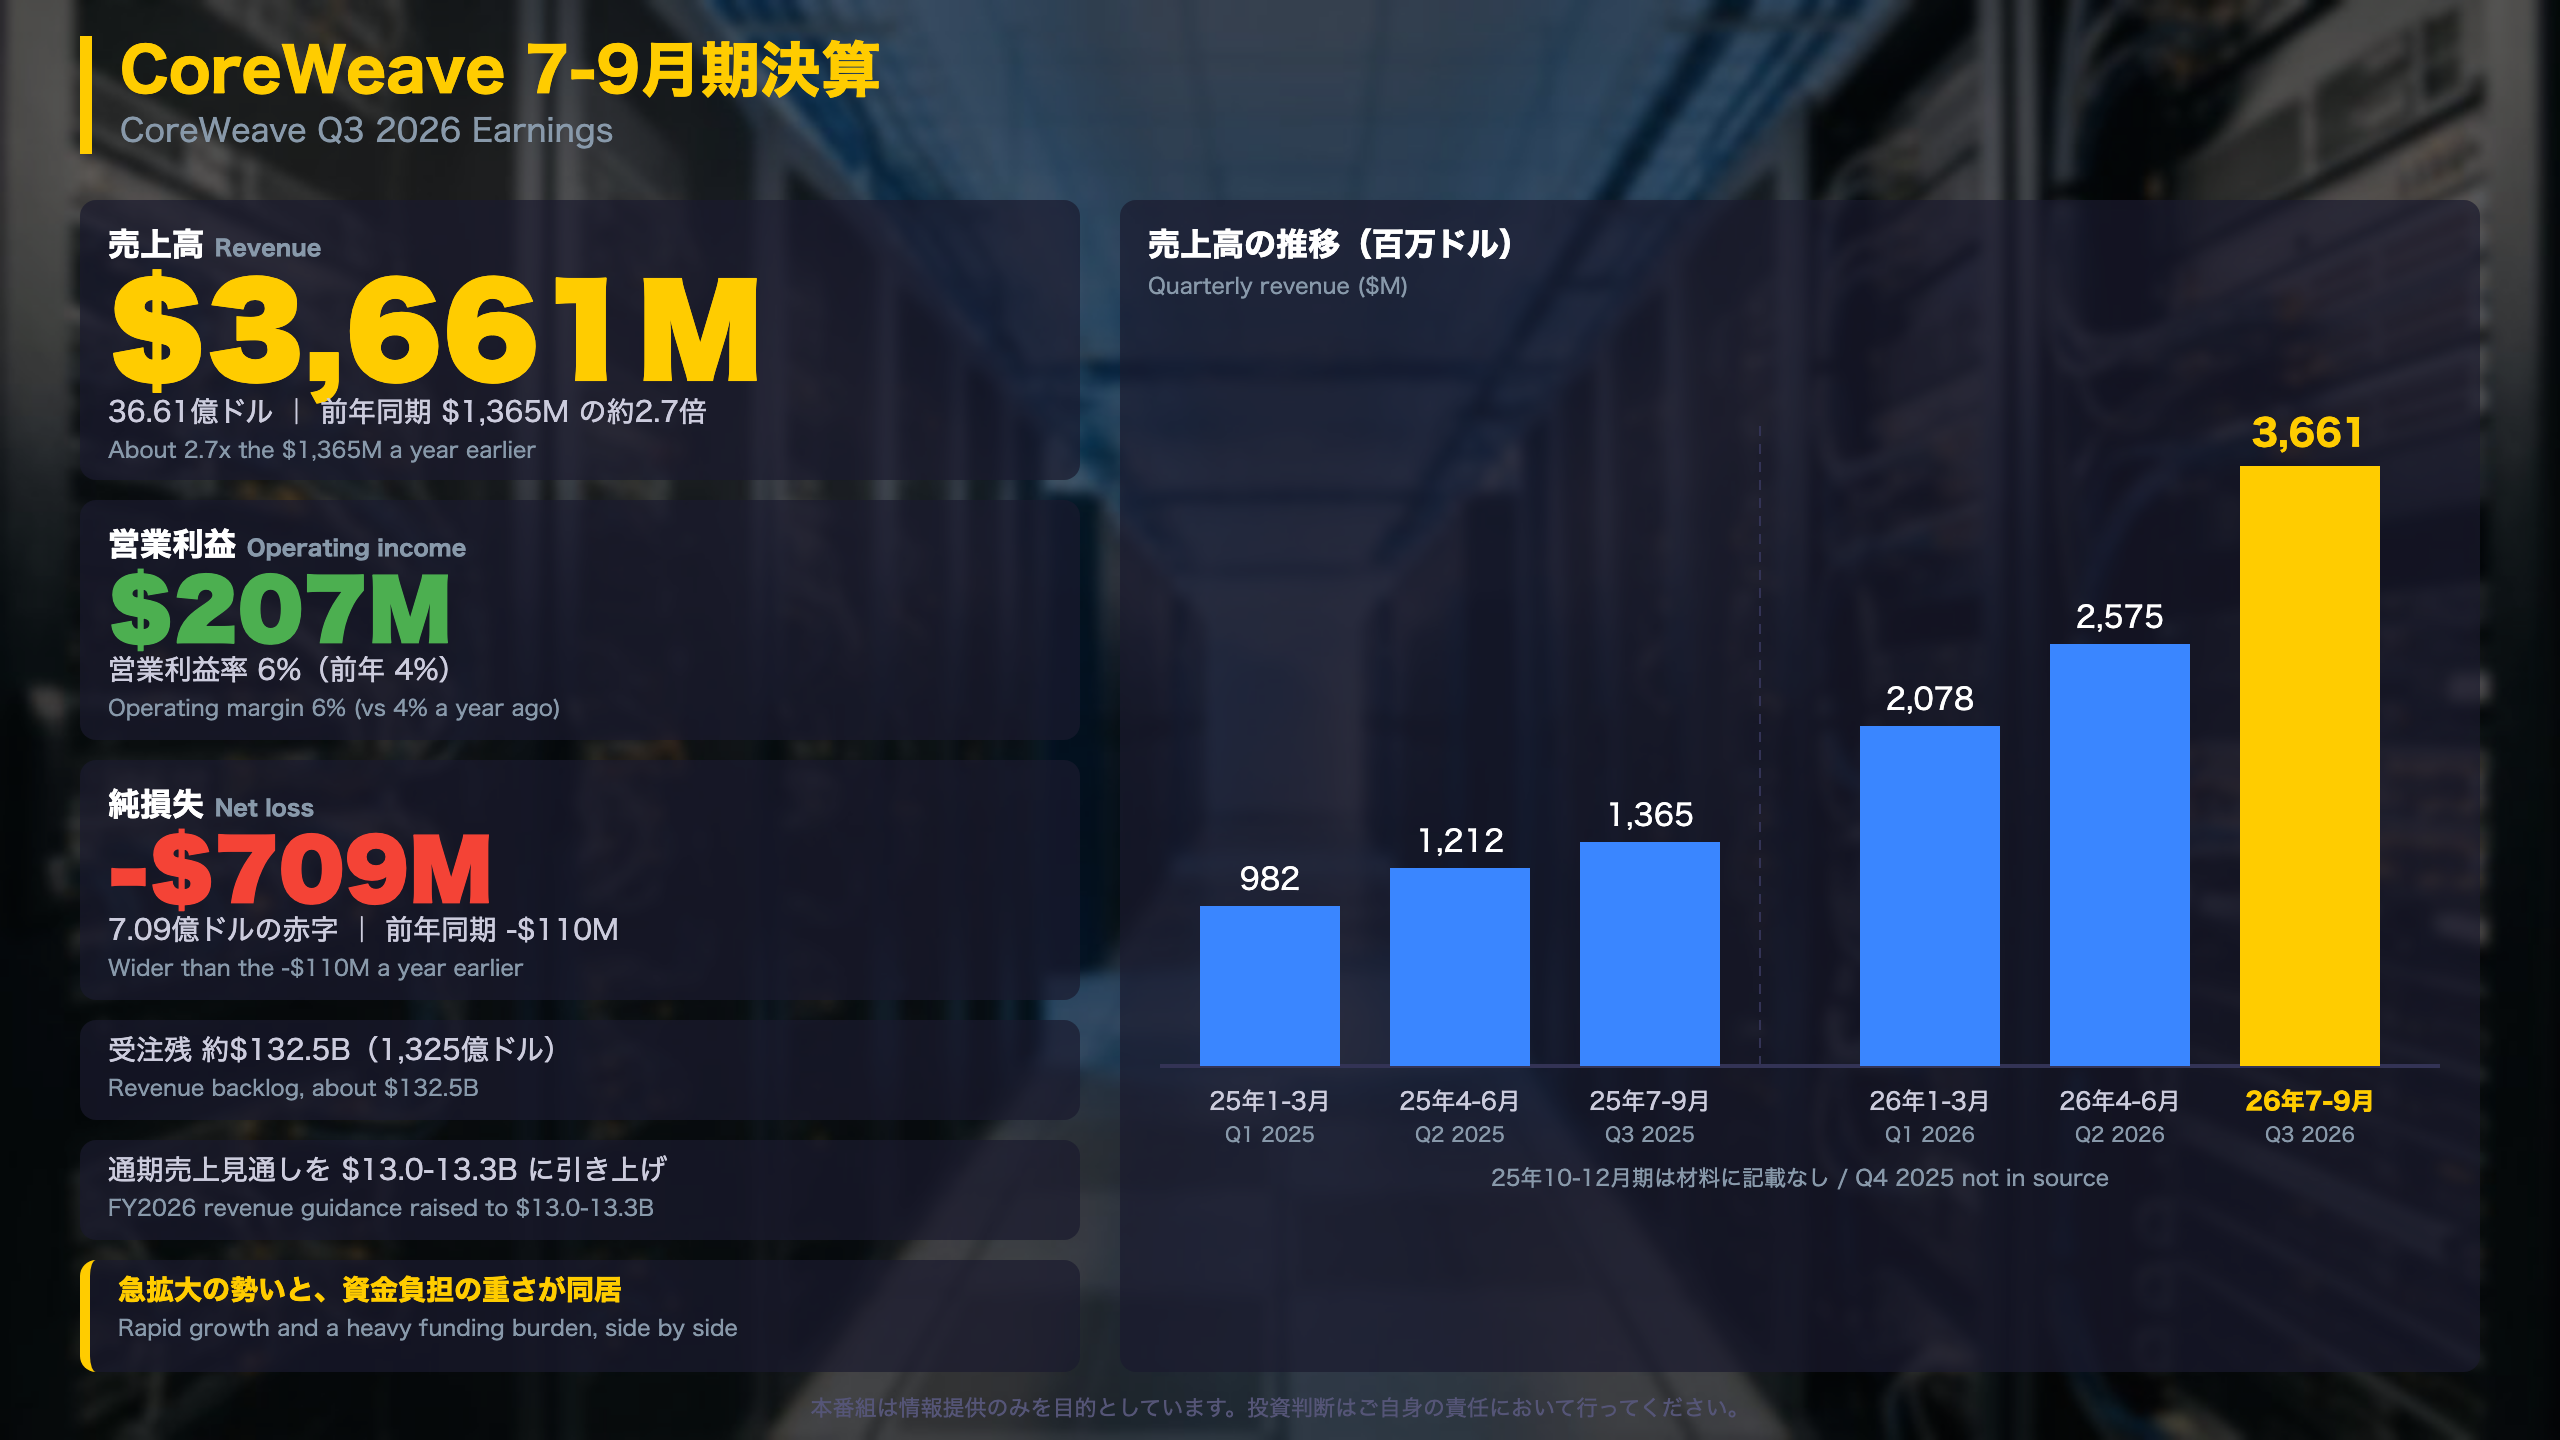
Revenue reached $3.661B, about 2.7x a year earlier, and operating income was $207M.
📉 But net interest expense rose to $846M and the net loss widened to $709M (vs $110M).
💡 Backlog is about $132.5B. The company raised full-year revenue and adjusted operating income guidance, and lifted the low end of its capex range to $37-39B.
⚠️ Next to watch: Q4 interest expense, capex execution and year-end active power.
CoreWeave 7-9月期決算:サマリー
What CoreWeave Reported
CoreWeave (Nasdaq: CRWV) is a so-called neocloud: a company built specifically to rent GPU-based computing capacity to AI labs, hyperscalers and enterprises. It listed on Nasdaq in March 2025. For the quarter ended September 30, 2026, it reported revenue of $3.661B versus $1.365B a year earlier, operating income of $207M, and a GAAP net loss of $709M ($1.27 per share).
How to Read the Numbers
- Growth: Revenue rose by more than $1B sequentially, which the CEO called a ‘breakout quarter’.
- Profitability: GAAP operating margin was 6% (4% a year ago). Adjusted operating margin was 10%, but that is below the 16% of Q3 2025.
- Burden: Net interest expense was $846M versus $310M, which is why a positive operating income still produced a wider net loss.
Context for Non-Japanese Readers
Unlike the large cloud platforms, whose AI spending is spread across wide, already-profitable businesses, CoreWeave’s balance sheet carries the build-out directly. Total assets rose from $49.3B to $91.5B between December 2025 and September 2026, while equity was $4.0B.
Two Readings
- Constructive: Backlog of about $132.5B and guidance raised for revenue and adjusted operating income.
- Cautious: Interest costs and debt keep rising alongside the build-out.
What to Verify Next
Fourth-quarter interest expense (guided at $1.05-1.15B) and year-end active power (over 1.85 GW). The release does not state the next earnings date.
深掘り1:売上の伸びの中身
Behind the Revenue Jump
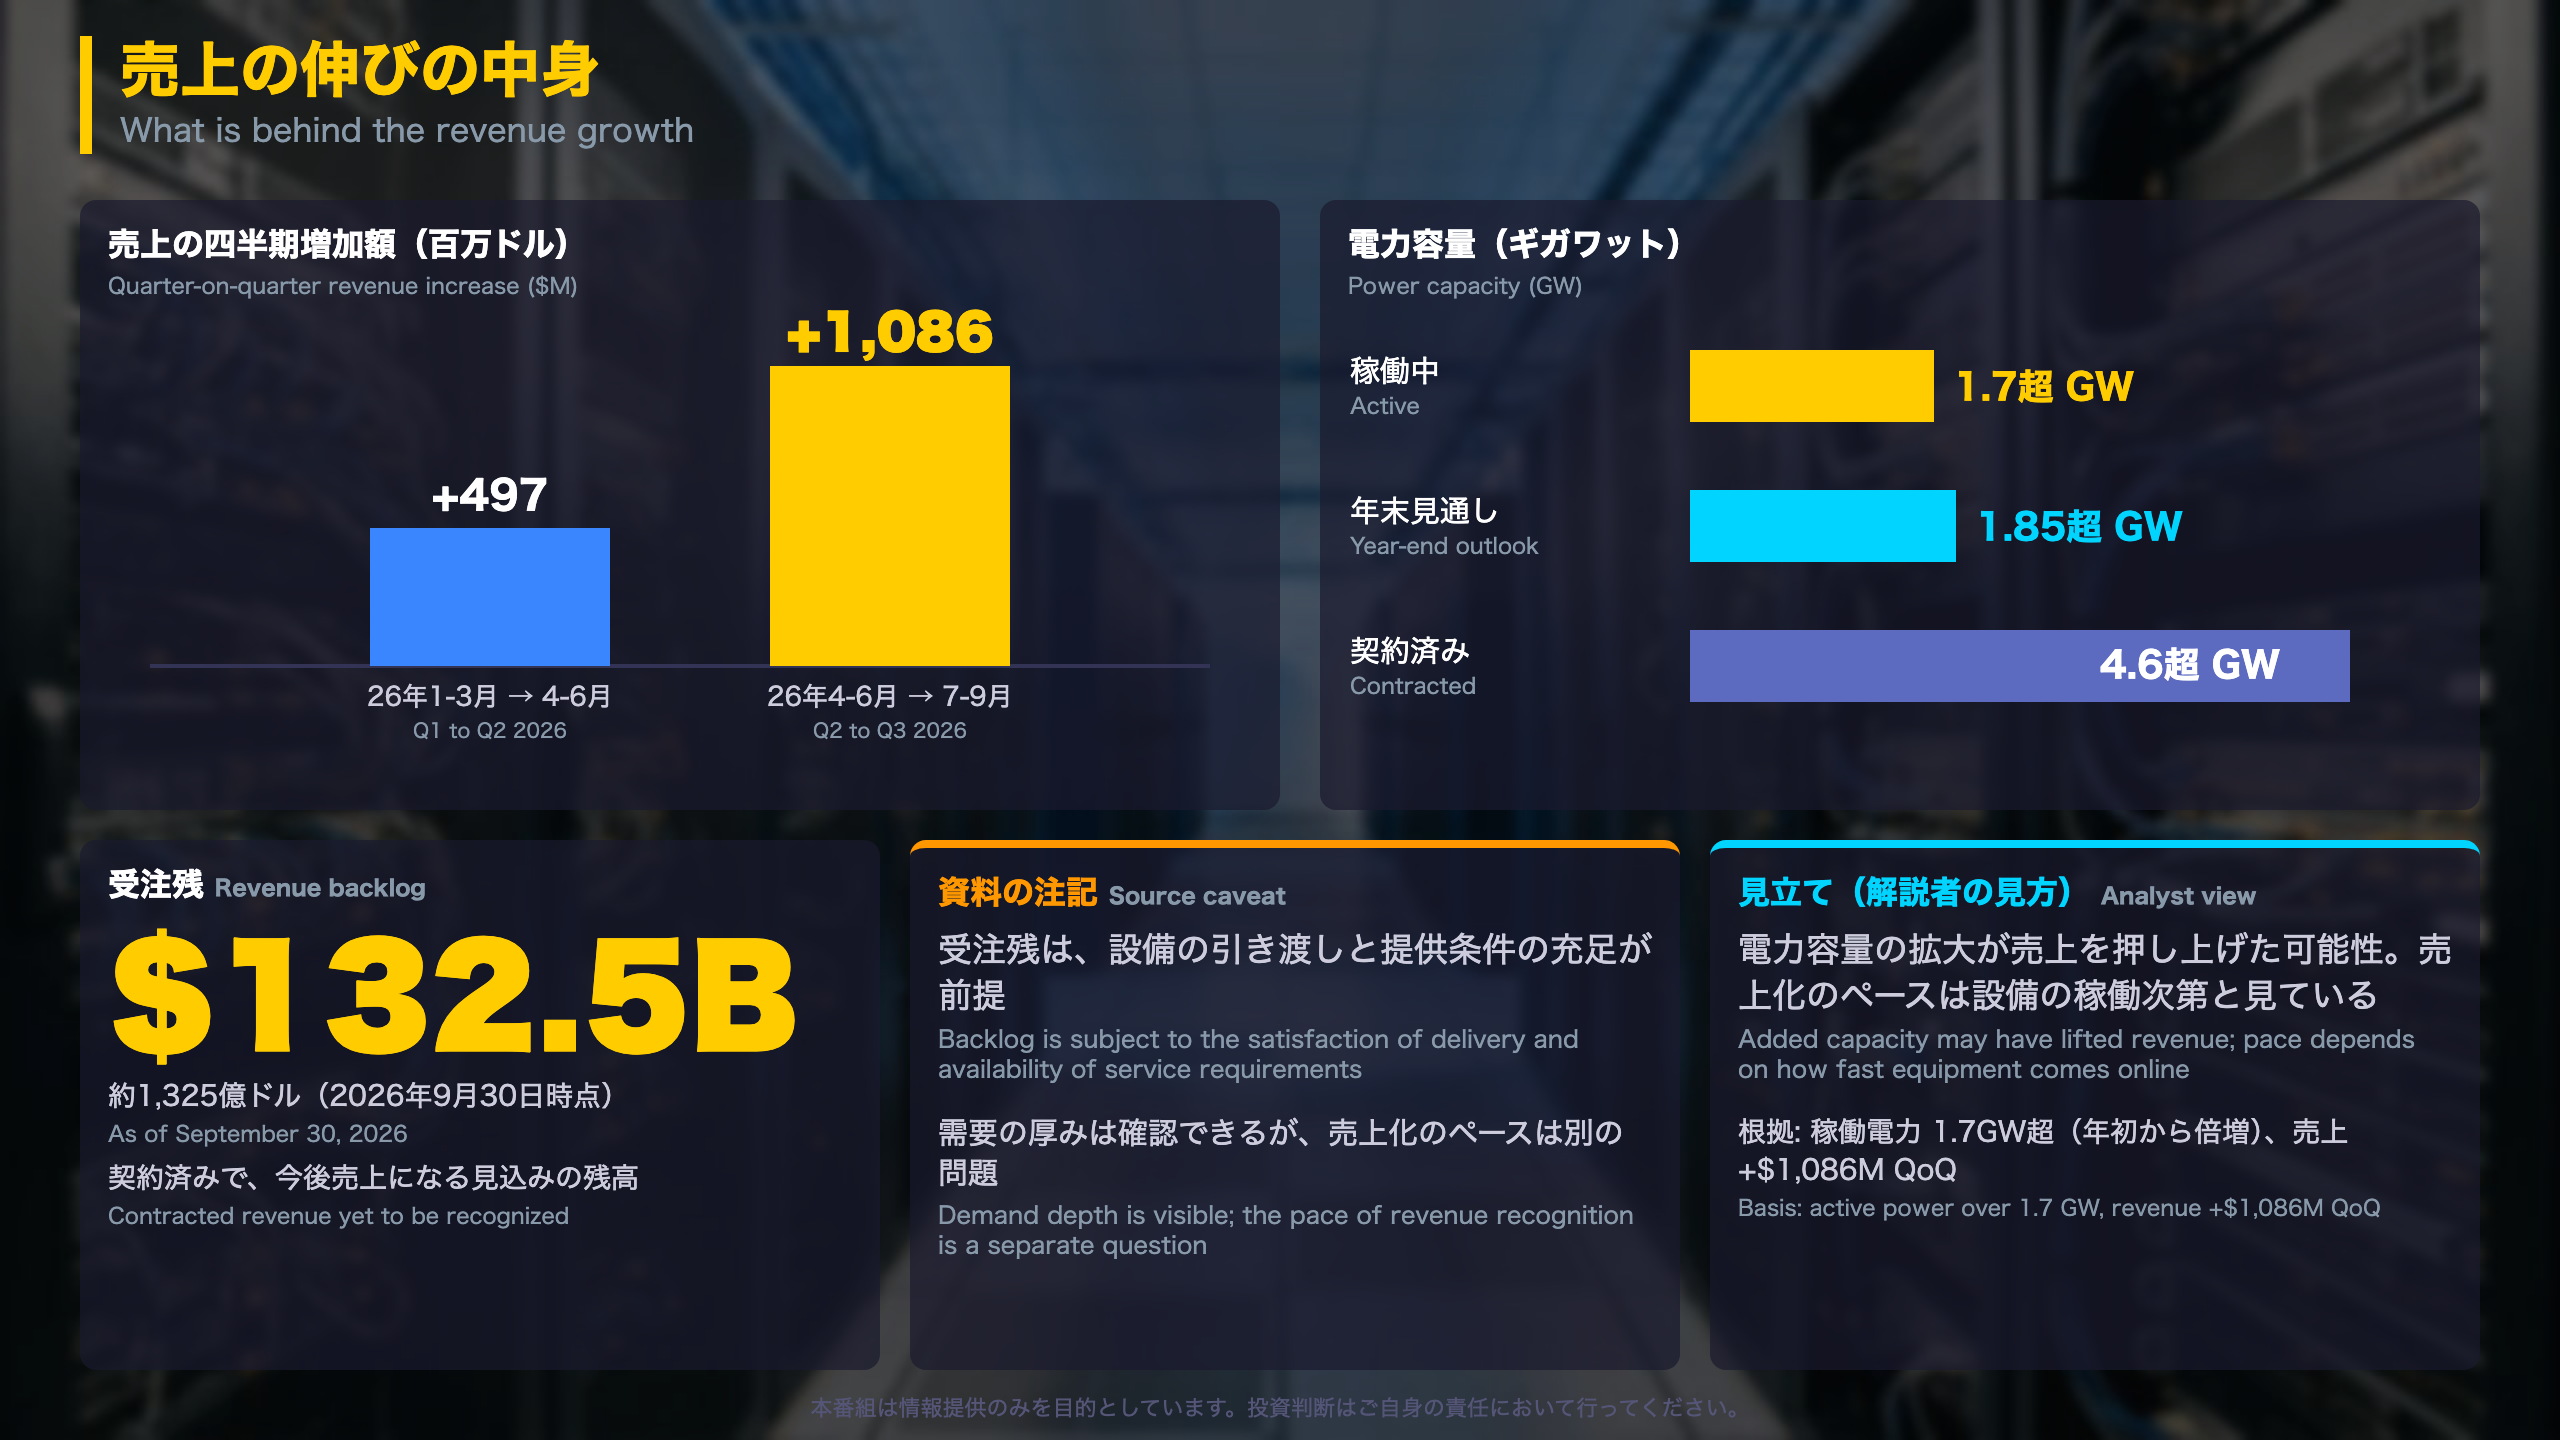
Sequential revenue growth was about $1.09B (from $2.575B to $3.661B), versus roughly $0.5B in the previous quarter, based on the XBRL history. The source does not include Q4 2025, so we compare only the quarters shown.
Capacity Is the Constraint and the Driver
CoreWeave sells access to GPU clusters, so revenue depends on how much powered, equipped capacity is delivered. Active power rose by more than 200 MW to over 1.7 GW, which the company says doubled its active footprint since the start of the year. Contracted power grew by over 900 MW to over 4.6 GW, including more than 1.3 GW internationally (India, Indonesia, Spain).
Technology Milestones
The company says the first production workloads on NVIDIA Vera Rubin NVL72 achieved 4.8x the token throughput of GB200 NVL72, and it launched CoreWeave Forge, an AI development environment.
Backlog With a Footnote
Backlog of about $132.5B includes remaining performance obligations plus other committed amounts, ‘subject to the satisfaction of delivery and availability of service requirements’.
Two Readings
- Constructive: A large committed backlog and growing contracted power point to deep demand.
- Cautious: Revenue recognition depends on equipment delivery and power availability.
What to Verify Next
The company still expects more than 1.85 GW of active power at year-end, only modestly above today’s 1.7 GW.
深掘り2:利益と資金の負担
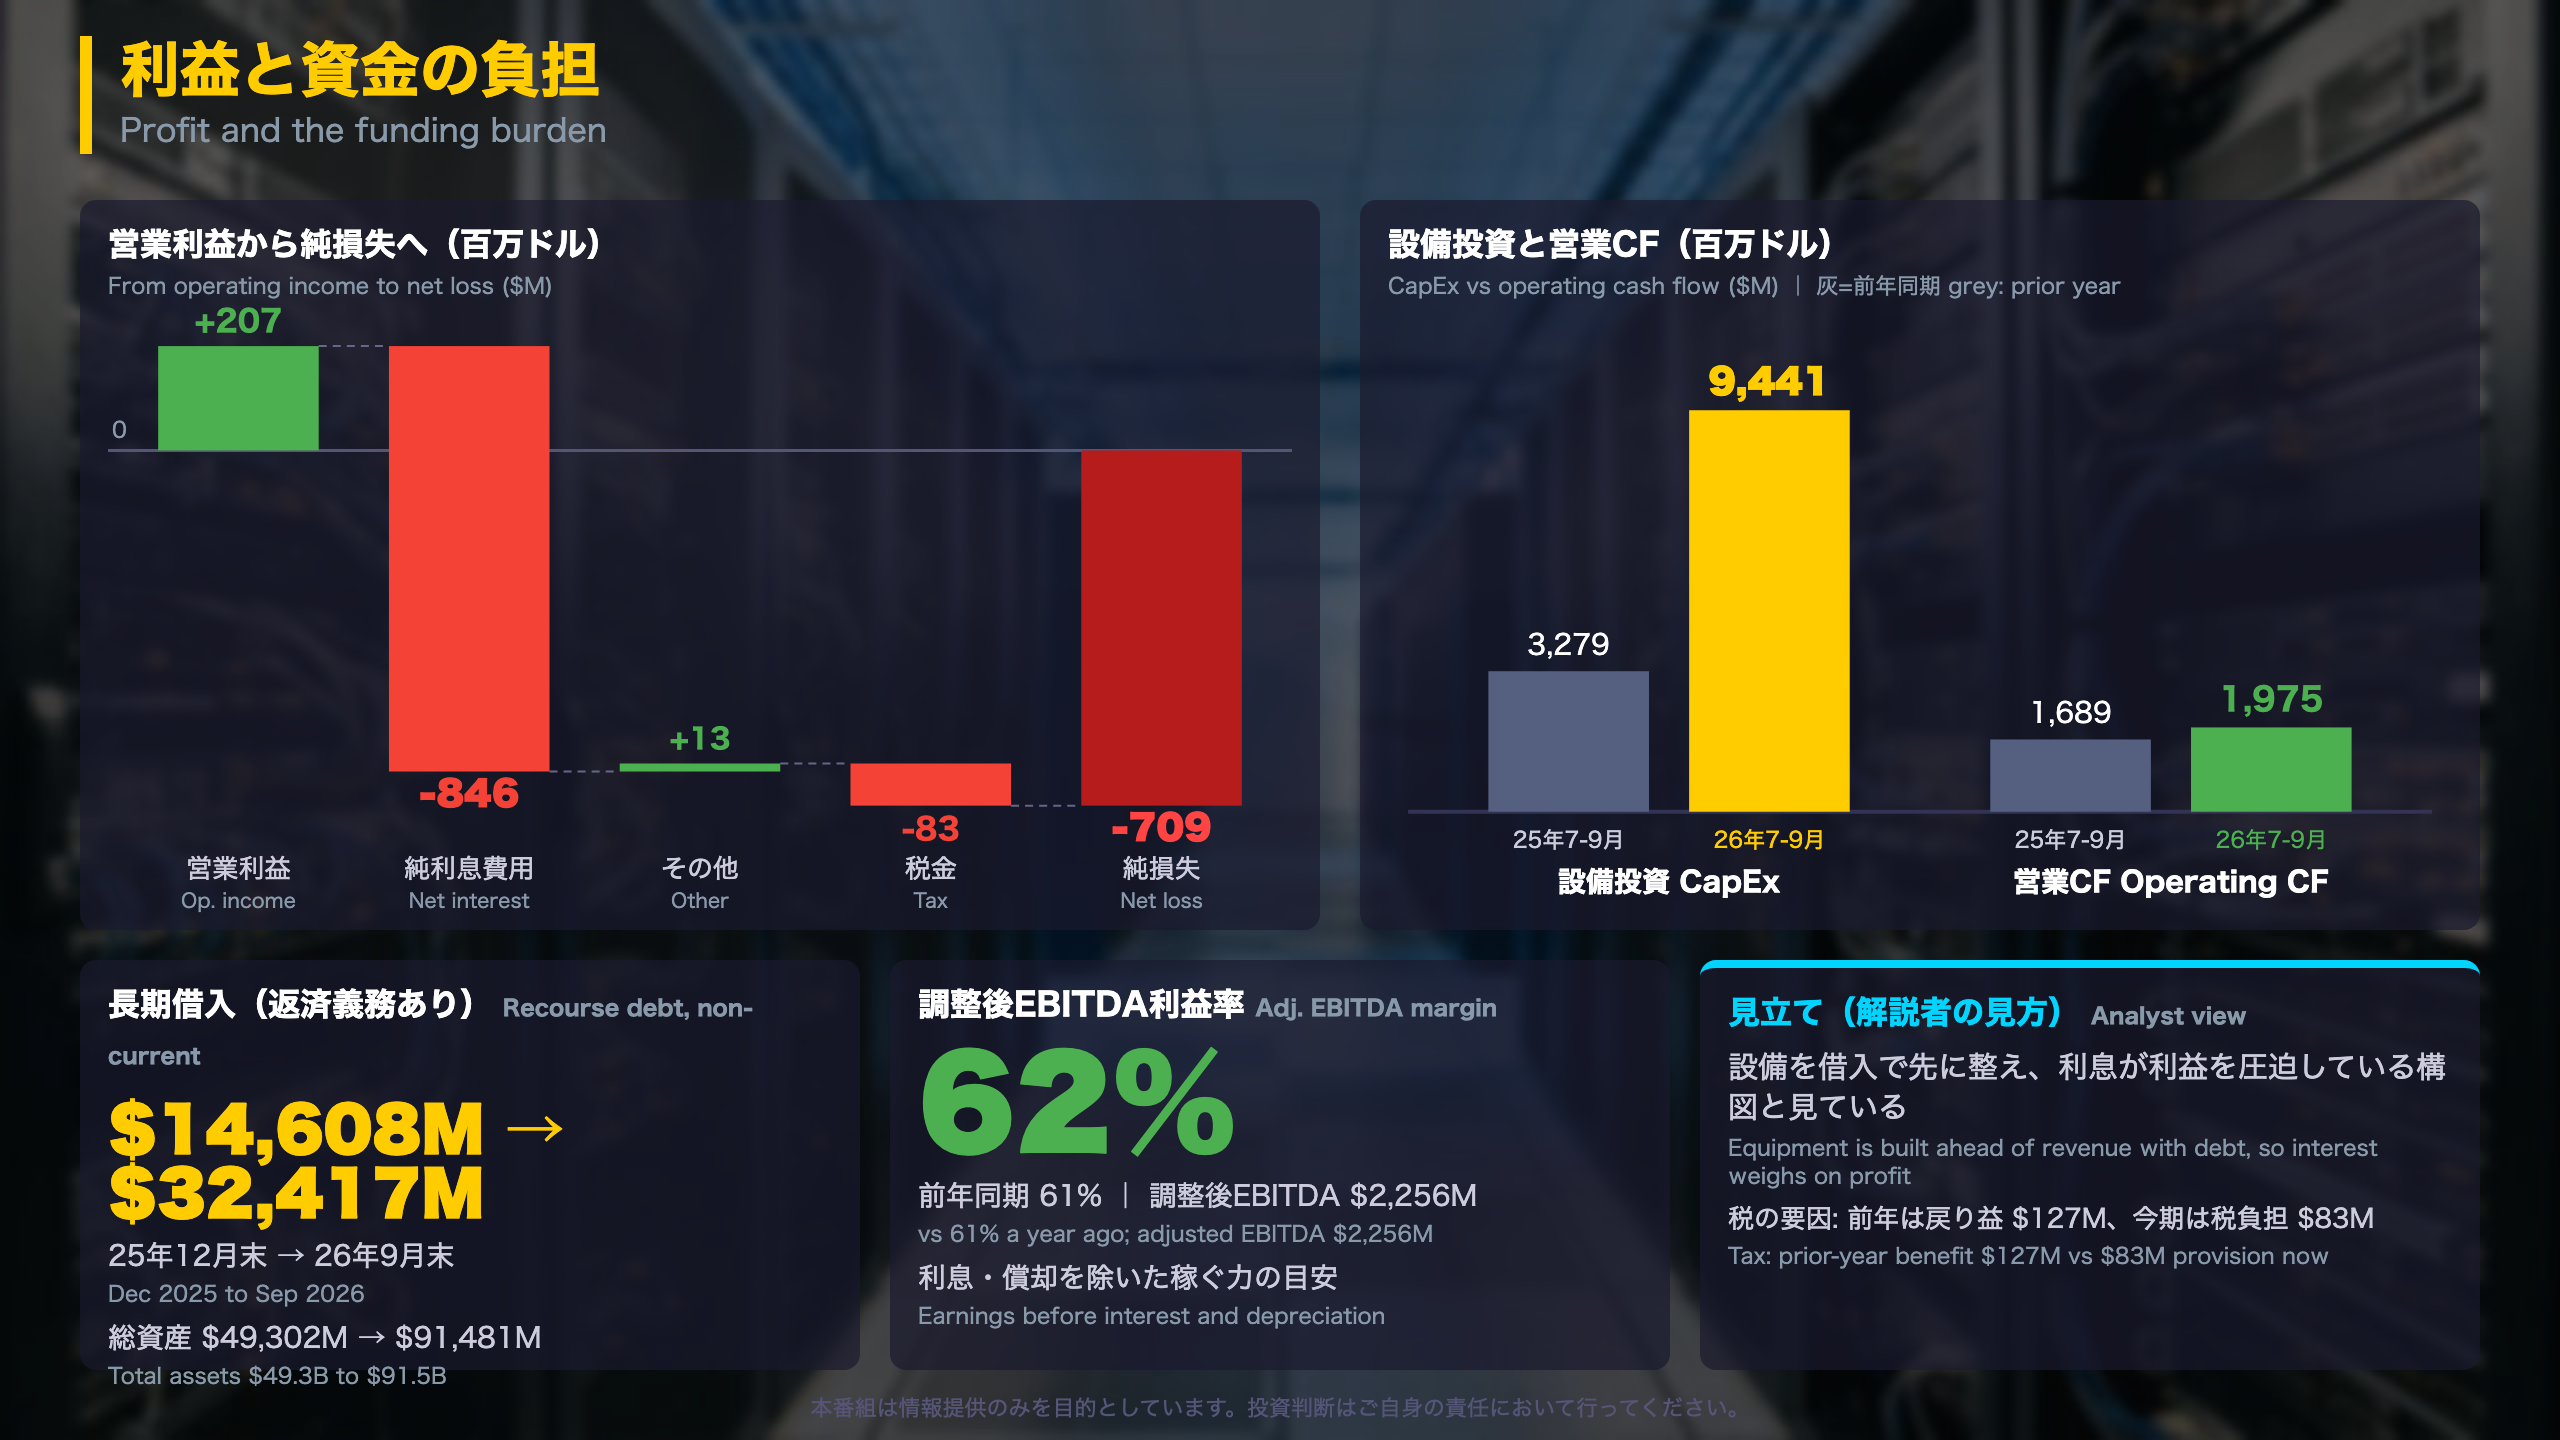
From Operating Income to Net Loss
Operating income of $207M turned into a $709M net loss through $846M of net interest expense, $13M of other income and an $83M tax provision. A year earlier the company booked a $127M tax benefit, so about $210M of the swing in net income is a tax effect. Pre-tax loss was $626M versus $237M.
Cash Flow Picture
- Operating cash flow: $1,975M (vs $1,689M)
- Capital expenditures: $9,441M (vs $3,279M)
- Net debt proceeds: $10,301M, repayments $2,344M, capped call purchases $566M
- Deferred revenue added $2,127M of operating cash, while receivables absorbed $1,741M
Total cash, cash equivalents and restricted cash fell by $500M to $6,404M.
Balance Sheet
Non-current recourse debt rose from $14.6B (December 2025) to $32.4B, and total assets from $49.3B to $91.5B. For readers used to asset-light software firms, the closer comparison is a capital-intensive infrastructure builder financed by debt backed by customer contracts.
Two Readings
- Constructive: Adjusted EBITDA margin of 62% (61% a year ago) shows underlying unit economics holding.
- Cautious: Nine-month net loss of $2,075M compares with $2,022M of net interest expense.
What to Verify Next
Q4 interest expense is guided at $1.05-1.15B, above this quarter’s $846M.
質疑で深める:利益率・見通し・資金調達
The Guidance, Line by Line
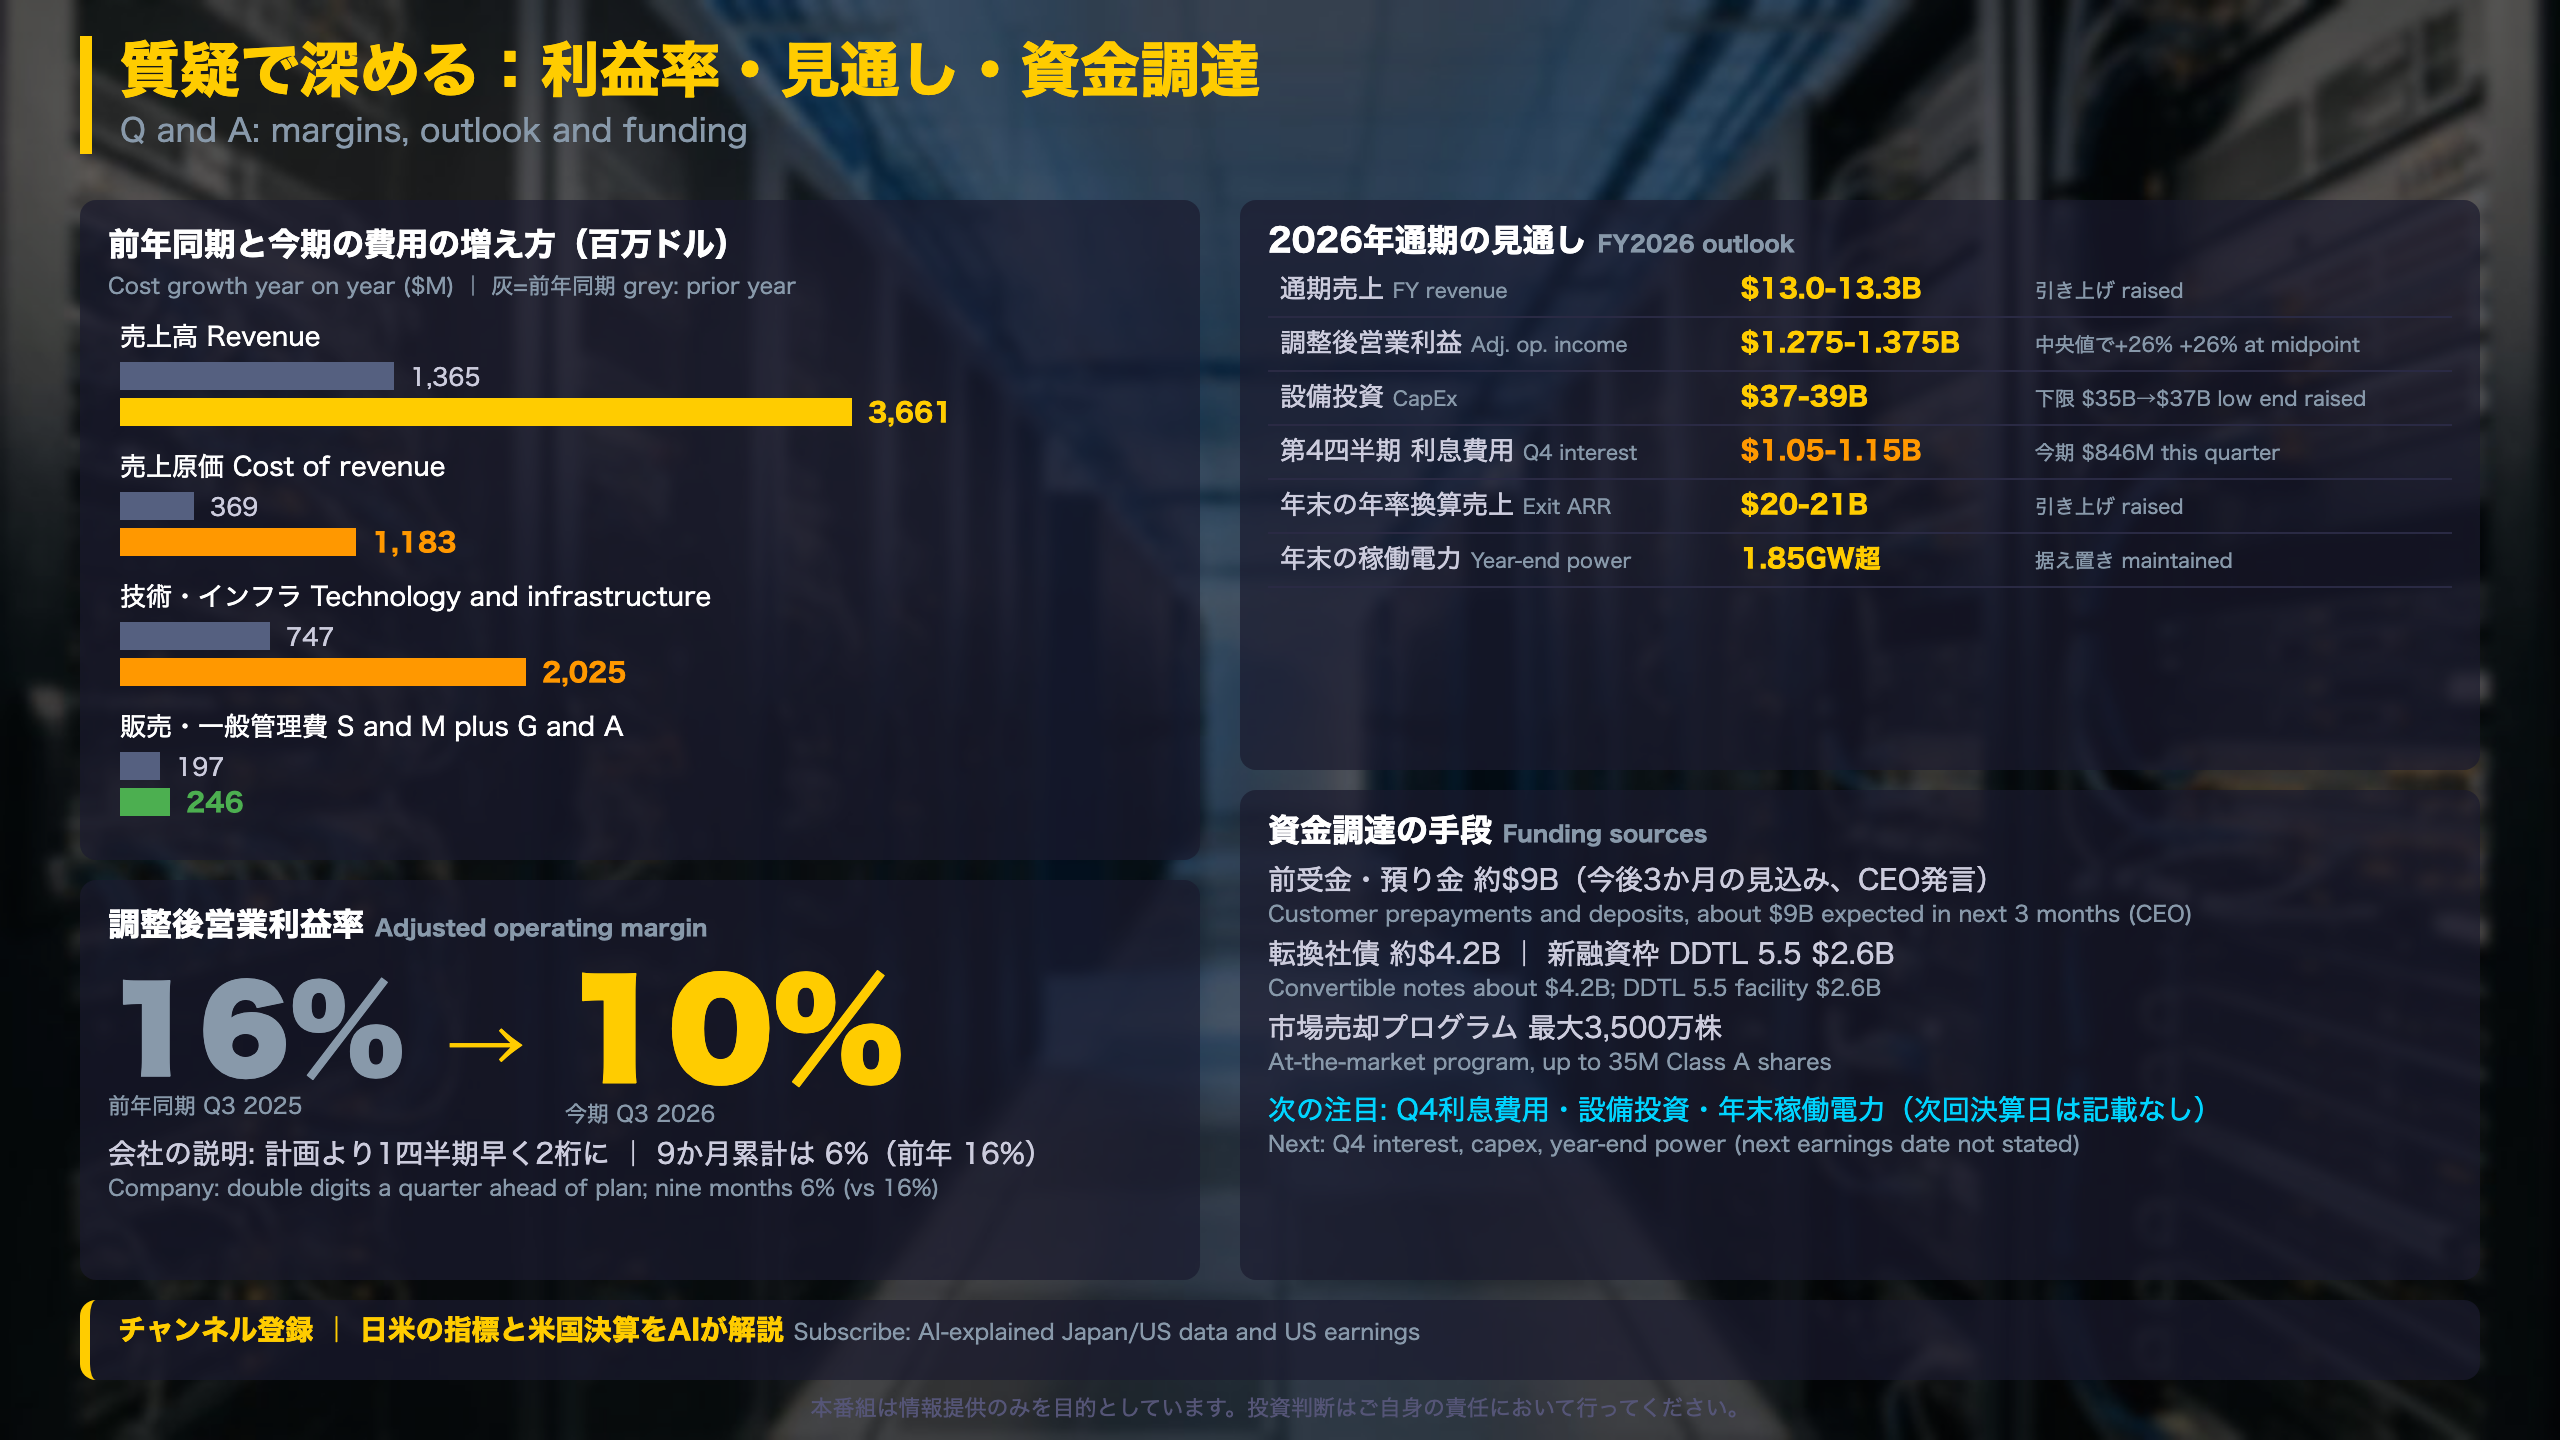
Full-year 2026 revenue guidance was raised to $13.0-13.3B. Adjusted operating income guidance is $1.275-1.375B, a 26% increase at the midpoint over the prior guidance. Capex is now $37-39B (low end raised from $35B) because the company expects to deploy infrastructure and deliver it to customers sooner than planned. Q4 interest expense is guided at $1.05-1.15B, and annualized run-rate revenue (last month of the quarter times 12) at $20-21B to exit 2026.
Why Adjusted Operating Margin Fell Year on Year
Adjusted operating margin was 10% versus 16%. Cost of revenue rose to $1,183M from $369M and technology and infrastructure to $2,025M from $747M, while sales, general and administrative costs rose far less. The company said it reached double-digit margins a quarter ahead of plan.
Funding Mix
The company points to contract-backed financing, operating cash flow and about $9B of expected customer prepayments and deposits over the next three months. In the quarter it raised about $4.2B of convertible notes, closed a $2.6B DDTL 5.5 facility designed for shorter-duration contracts, and set up an at-the-market program for up to 35 million Class A shares.
Two Readings
- Constructive: Diversified funding and raised guidance.
- Cautious: Adjusted operating income excludes interest, which remains a separate burden.
What to Verify Next
The release does not give the next earnings date. Our simple arithmetic: nine-month revenue of $8.314B against the full-year range implies roughly $4.7-5.0B for Q4, which is not company-stated.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.