This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-11-13 06:20 JST)
📊 Cerebras Systems (NASDAQ: CBRS) reported Q3 2026 results on Nov 12.
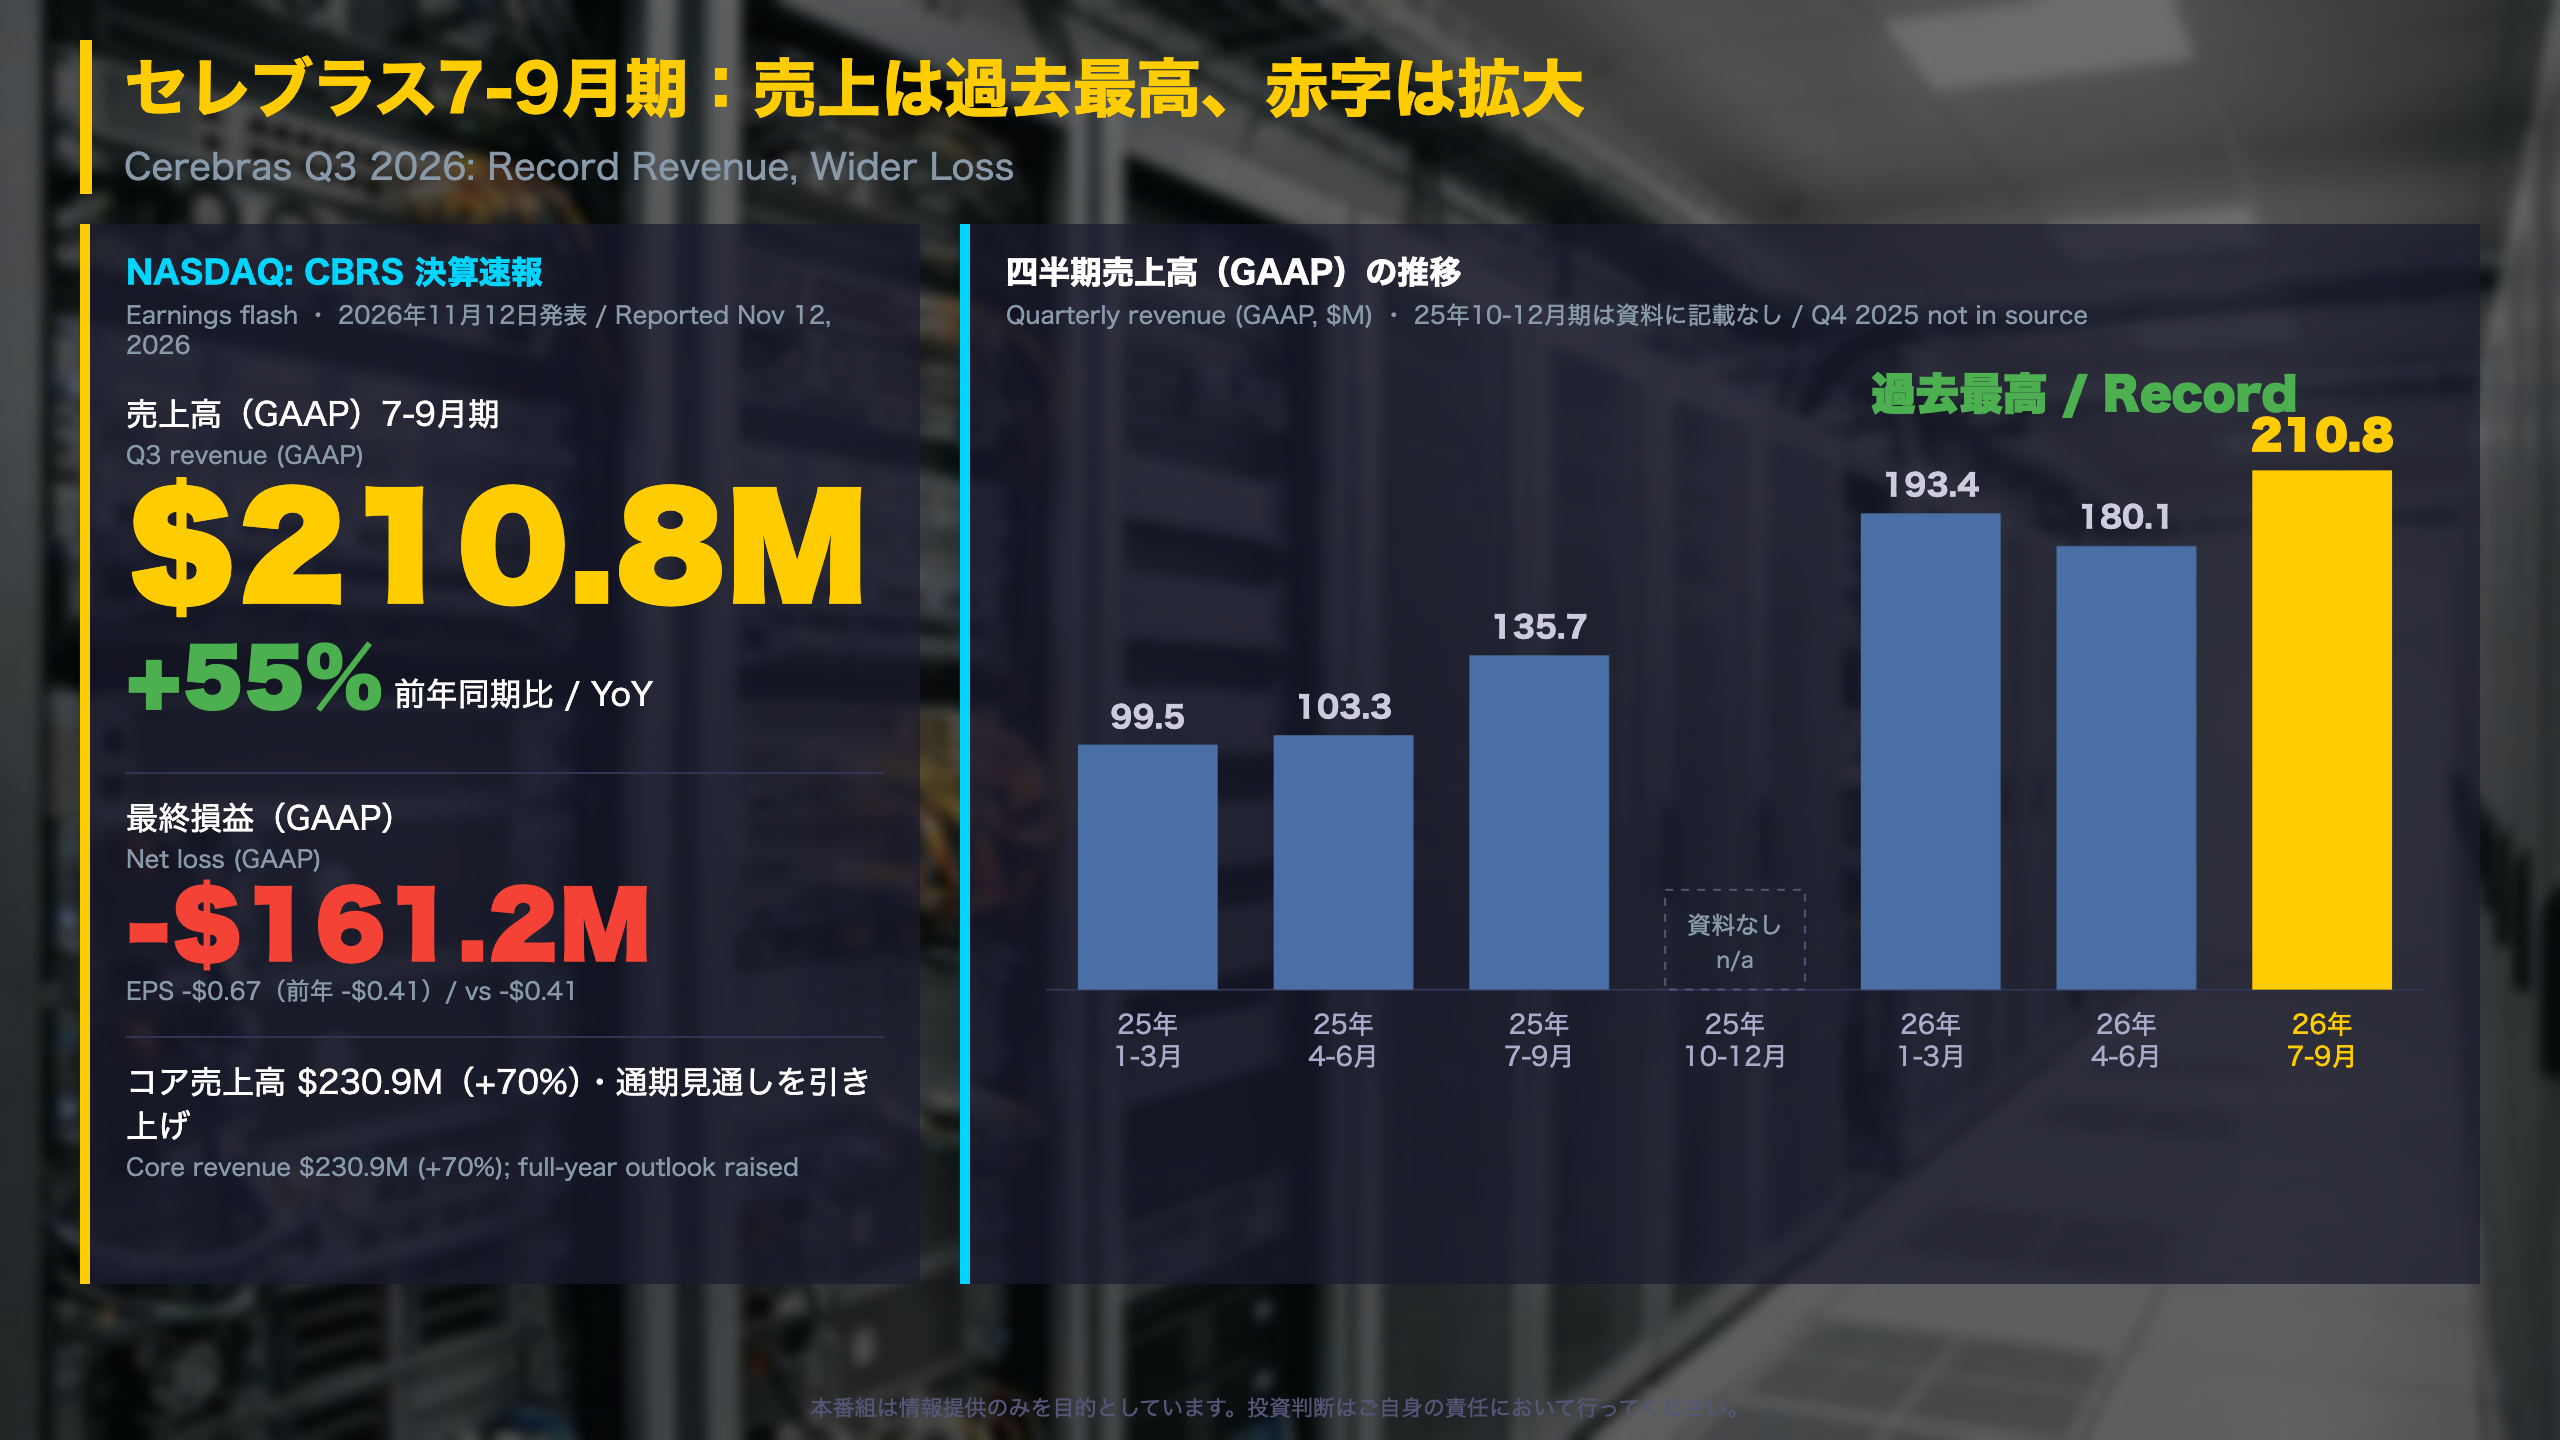
💰 GAAP revenue hit a record $210.8M, up 55% YoY. Cloud and services revenue rose 265% to $141.9M.
📉 The GAAP net loss was $161.2M. On the company’s core basis, which excludes stock-based compensation and other items, operating margin was -14% and net income was +$29.8M.
💡 Q4 core revenue guidance is $310-330M and the full-year outlook was raised. Remaining performance obligations stand at $26.1B.
⚠️ The company discloses dependence on a few large customers, including its agreement with OpenAI, as a key risk.
セレブラス7-9月期:売上は過去最高、赤字は拡大
Cerebras Q3 2026: What the Release Tells Us
Who is Cerebras? A U.S.-listed (NASDAQ: CBRS) AI infrastructure company known for wafer-scale processors. It sells systems outright and also sells fast inference through its own cloud and partner clouds. This release is an SEC Form 8-K, Exhibit 99.1.
Headline numbers
- GAAP revenue: $210.8M, +55% YoY; nine-month revenue $584.3M vs $338.5M.
- Core revenue (non-GAAP): $230.9M, +70% YoY.
- GAAP net loss: $161.2M, or $0.67 per share (vs $0.41).
- Core net income: +$29.8M.
Why two sets of numbers?
‘Core’ adds back customer-warrant amortization (booked as a reduction of revenue) and excludes stock-based compensation and pass-through items. Unlike GAAP, there is no standard definition, so comparisons with other companies need care.
Share count matters
Weighted average shares rose from 54.0M to 238.9M, so per-share figures are not like-for-like with last year.
What to watch
Q4 core revenue guidance is $310-330M. The release does not state the next earnings date.
売上の中身が入れ替わった:ハードからクラウドへ
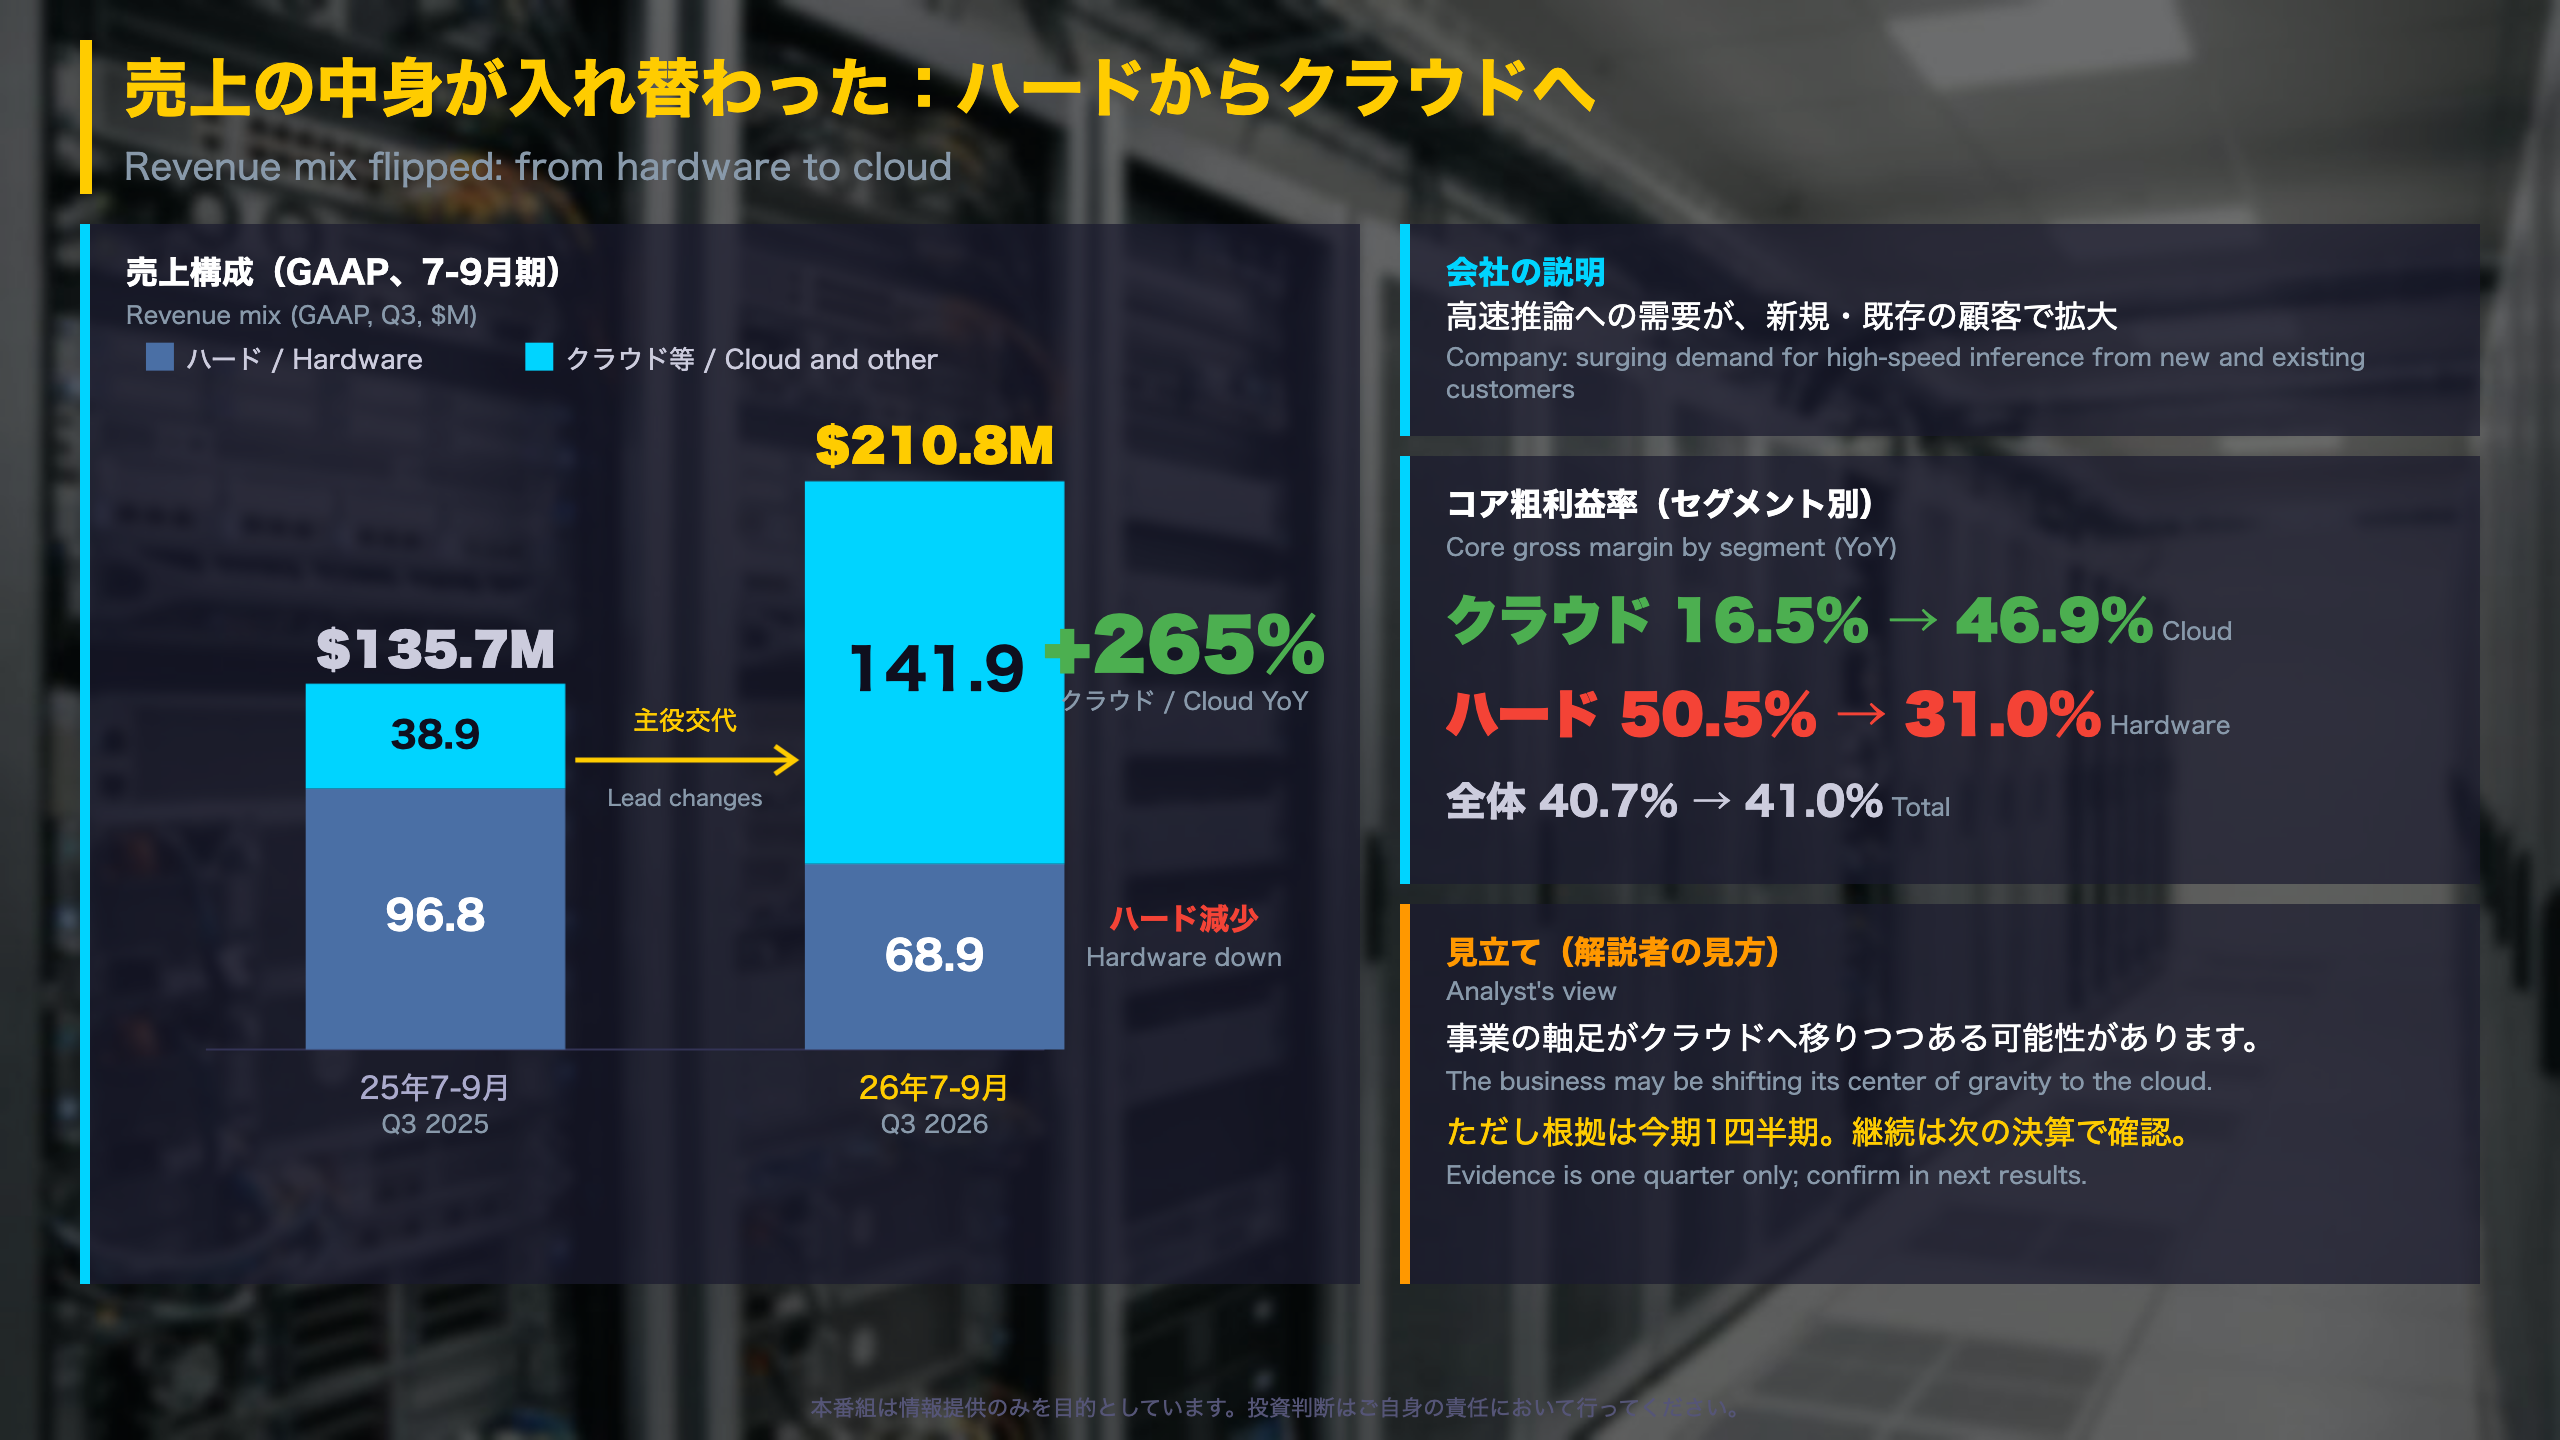
Revenue Mix: Cloud Overtakes Hardware
| Segment (GAAP) | Q3 2026 | Q3 2025 |
|---|---|---|
| Hardware | $68.9M | $96.8M |
| Cloud & other services | $141.9M | $38.9M |
Cloud now makes up about two-thirds of GAAP revenue, versus roughly 29% a year ago.
Margin picture (core basis)
- Cloud gross margin: 46.9% vs 16.5%
- Hardware gross margin: 31.0% vs 50.5%
- Total: 41.0% vs 40.7%
The cloud improvement is offset by weaker hardware margins, which is why the blended margin barely moved year over year.
Context for global readers
Cloud revenue depends on having data center capacity to rent out. Cerebras says it has secured 700 MW (gross) for delivery by the end of 2027, and it highlights a technique called disaggregated inference that it says delivers more high-speed tokens for the same power.
Two readings
Bull: a higher cloud mix and better cloud margins suggest a more recurring revenue model is emerging.
Bear: one quarter of margin gains is thin evidence, and the hardware margin compression is real.
Watch next: whether cloud growth and margin hold in Q4.
赤字の見え方:GAAPとコアの差の大半は株式報酬
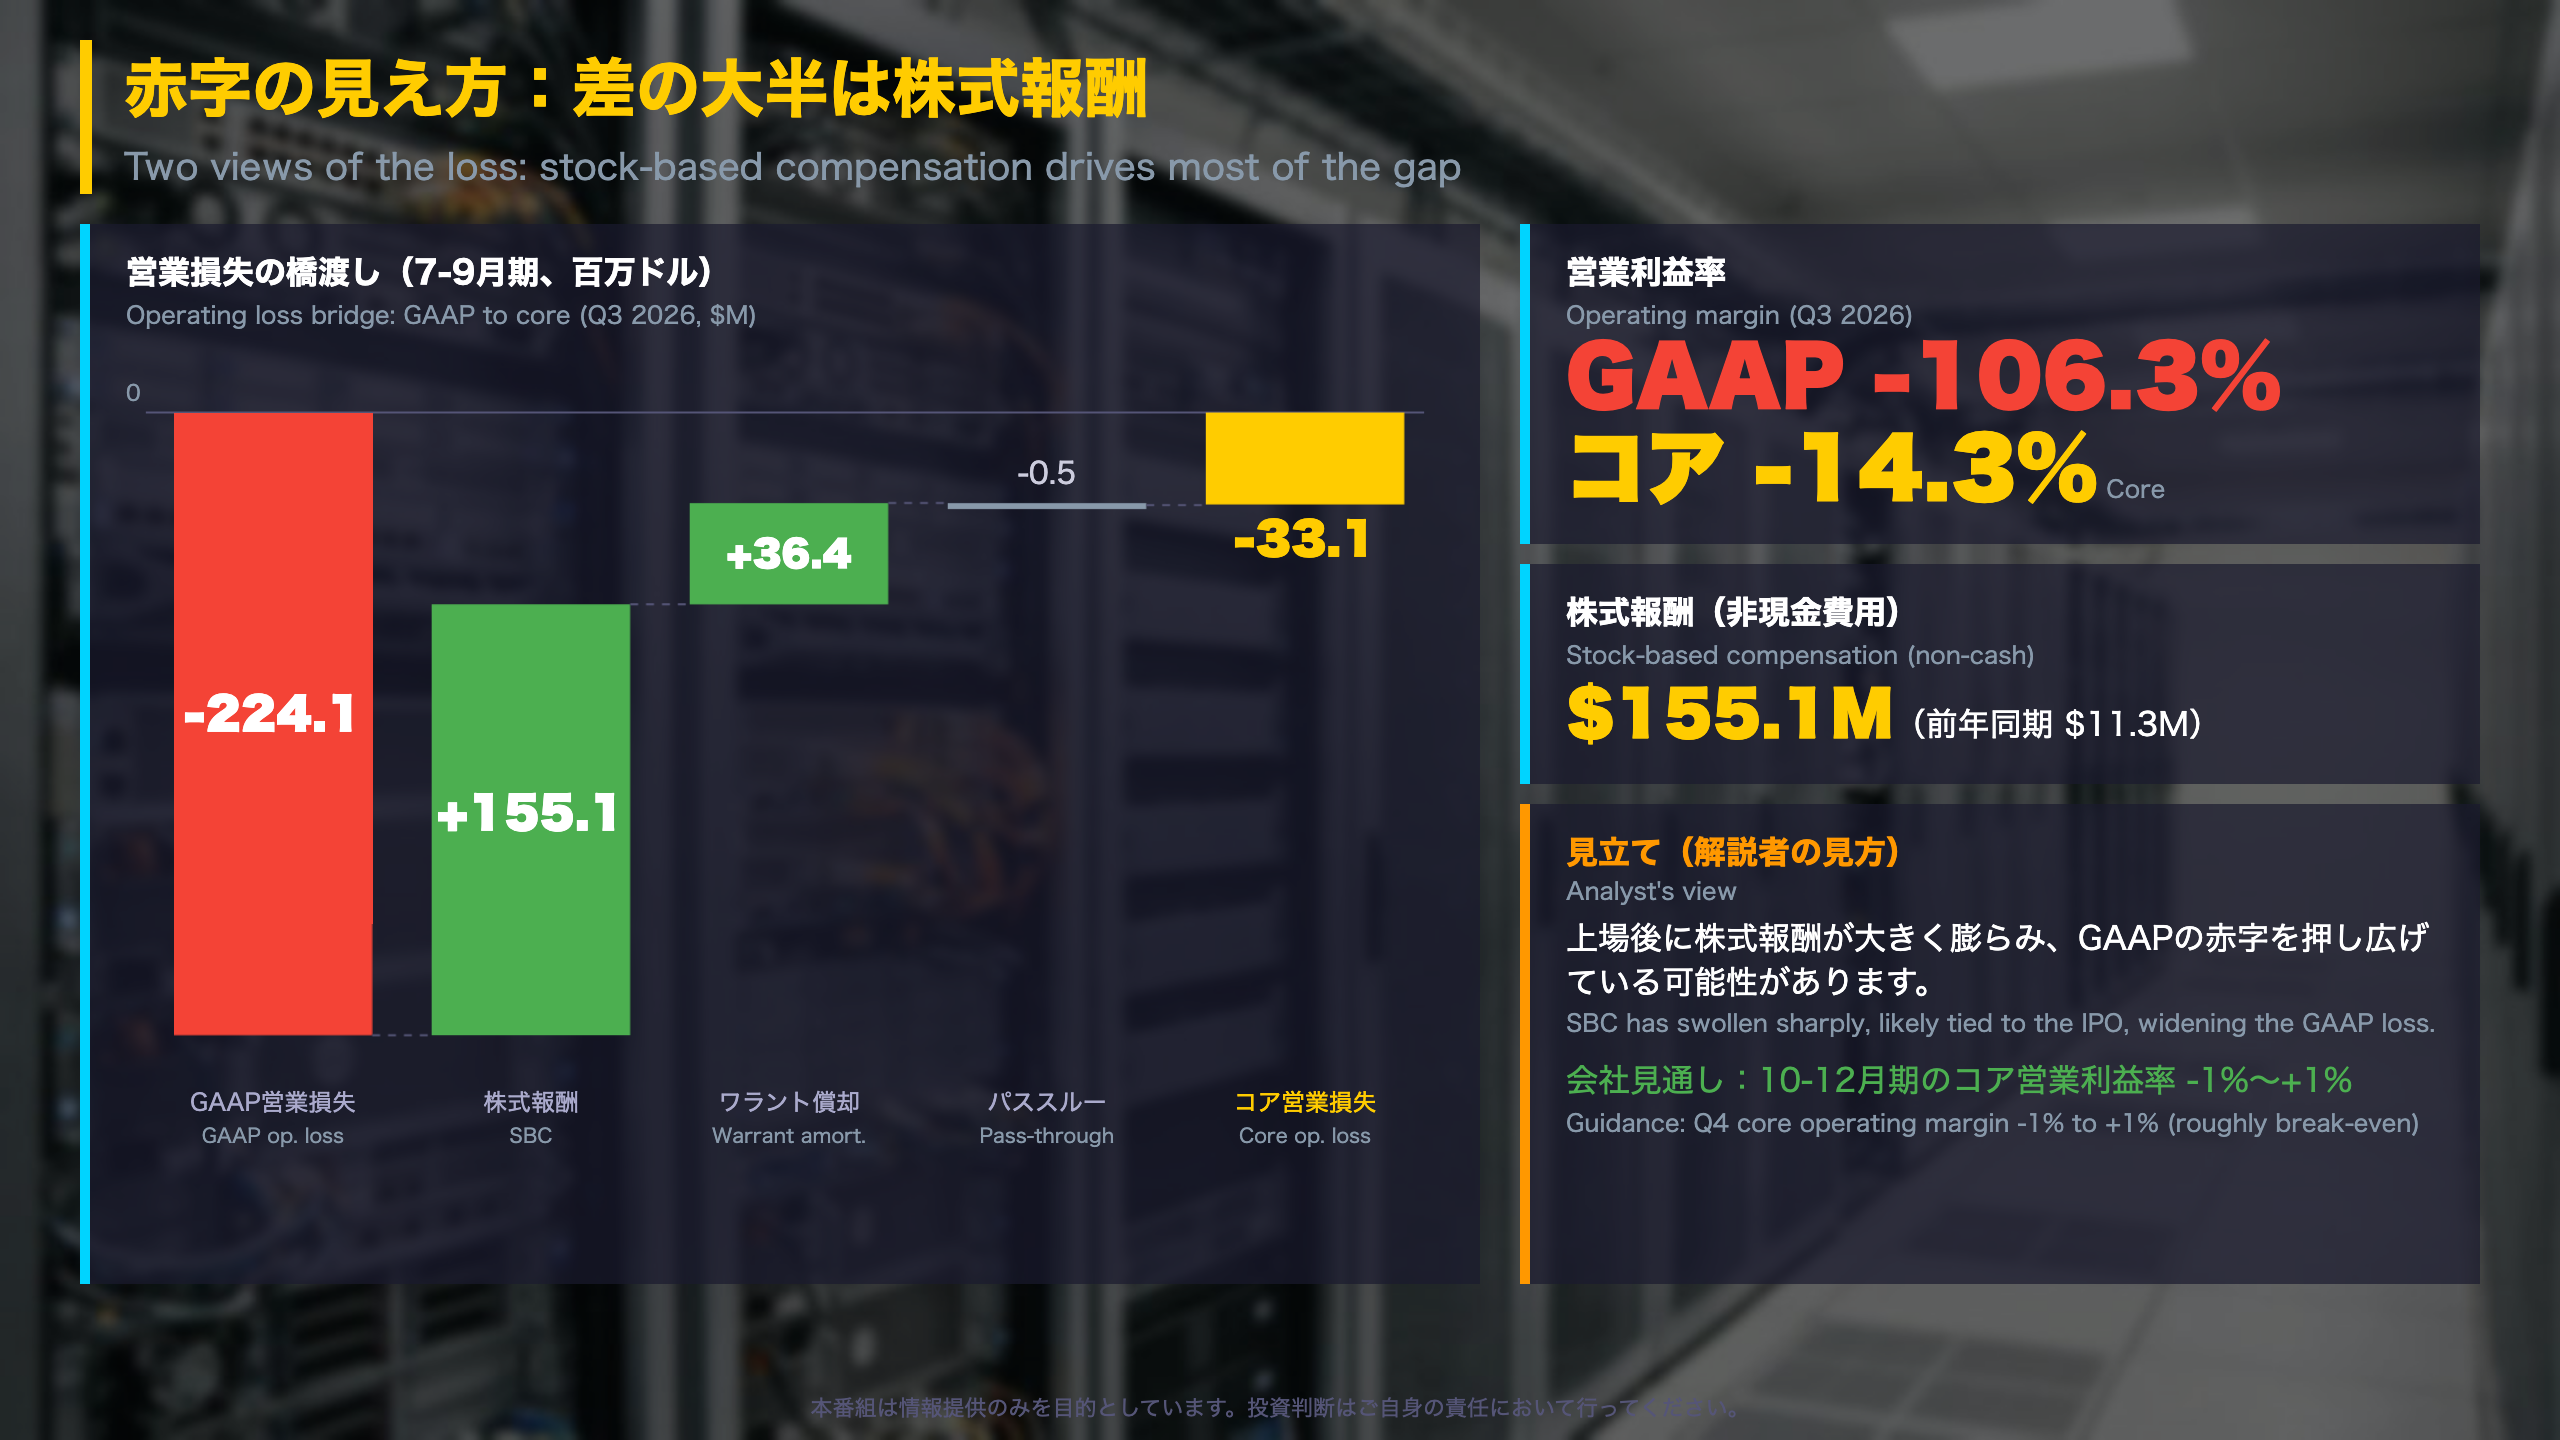
Reading the Loss: GAAP vs Core
Bridge from GAAP to core operating loss ($M)
| Item | Q3 2026 |
|---|---|
| GAAP operating loss | -224.1 |
| Pass-through (net) removed | -0.5 |
| + Stock-based compensation | +155.1 |
| + Customer-warrant amortization | +36.4 |
| Core operating loss | -33.1 |
Spending trend
R&D rose to $177.8M from $57.3M and G&A to $55.6M from $3.5M. Even excluding stock-based compensation, operating expenses were $127.7M vs $70.4M, so the company is investing heavily.
Below the operating line
Other income was $63.9M (vs $5.8M), which is why the GAAP net loss ($161.2M) is smaller than the operating loss. The release does not break out what drove it.
Cash
Nine-month operating cash flow was -$388.9M and capex was $1,046.1M, funded by $6,232.5M of IPO proceeds.
Two readings
Stock-based compensation is non-cash, so core may better show underlying economics. But it is a real cost that dilutes shareholders. Both views are valid.
Guidance: Q4 core operating margin of -1% to +1%.
質疑で深める:見通しの確かさと次の確認点
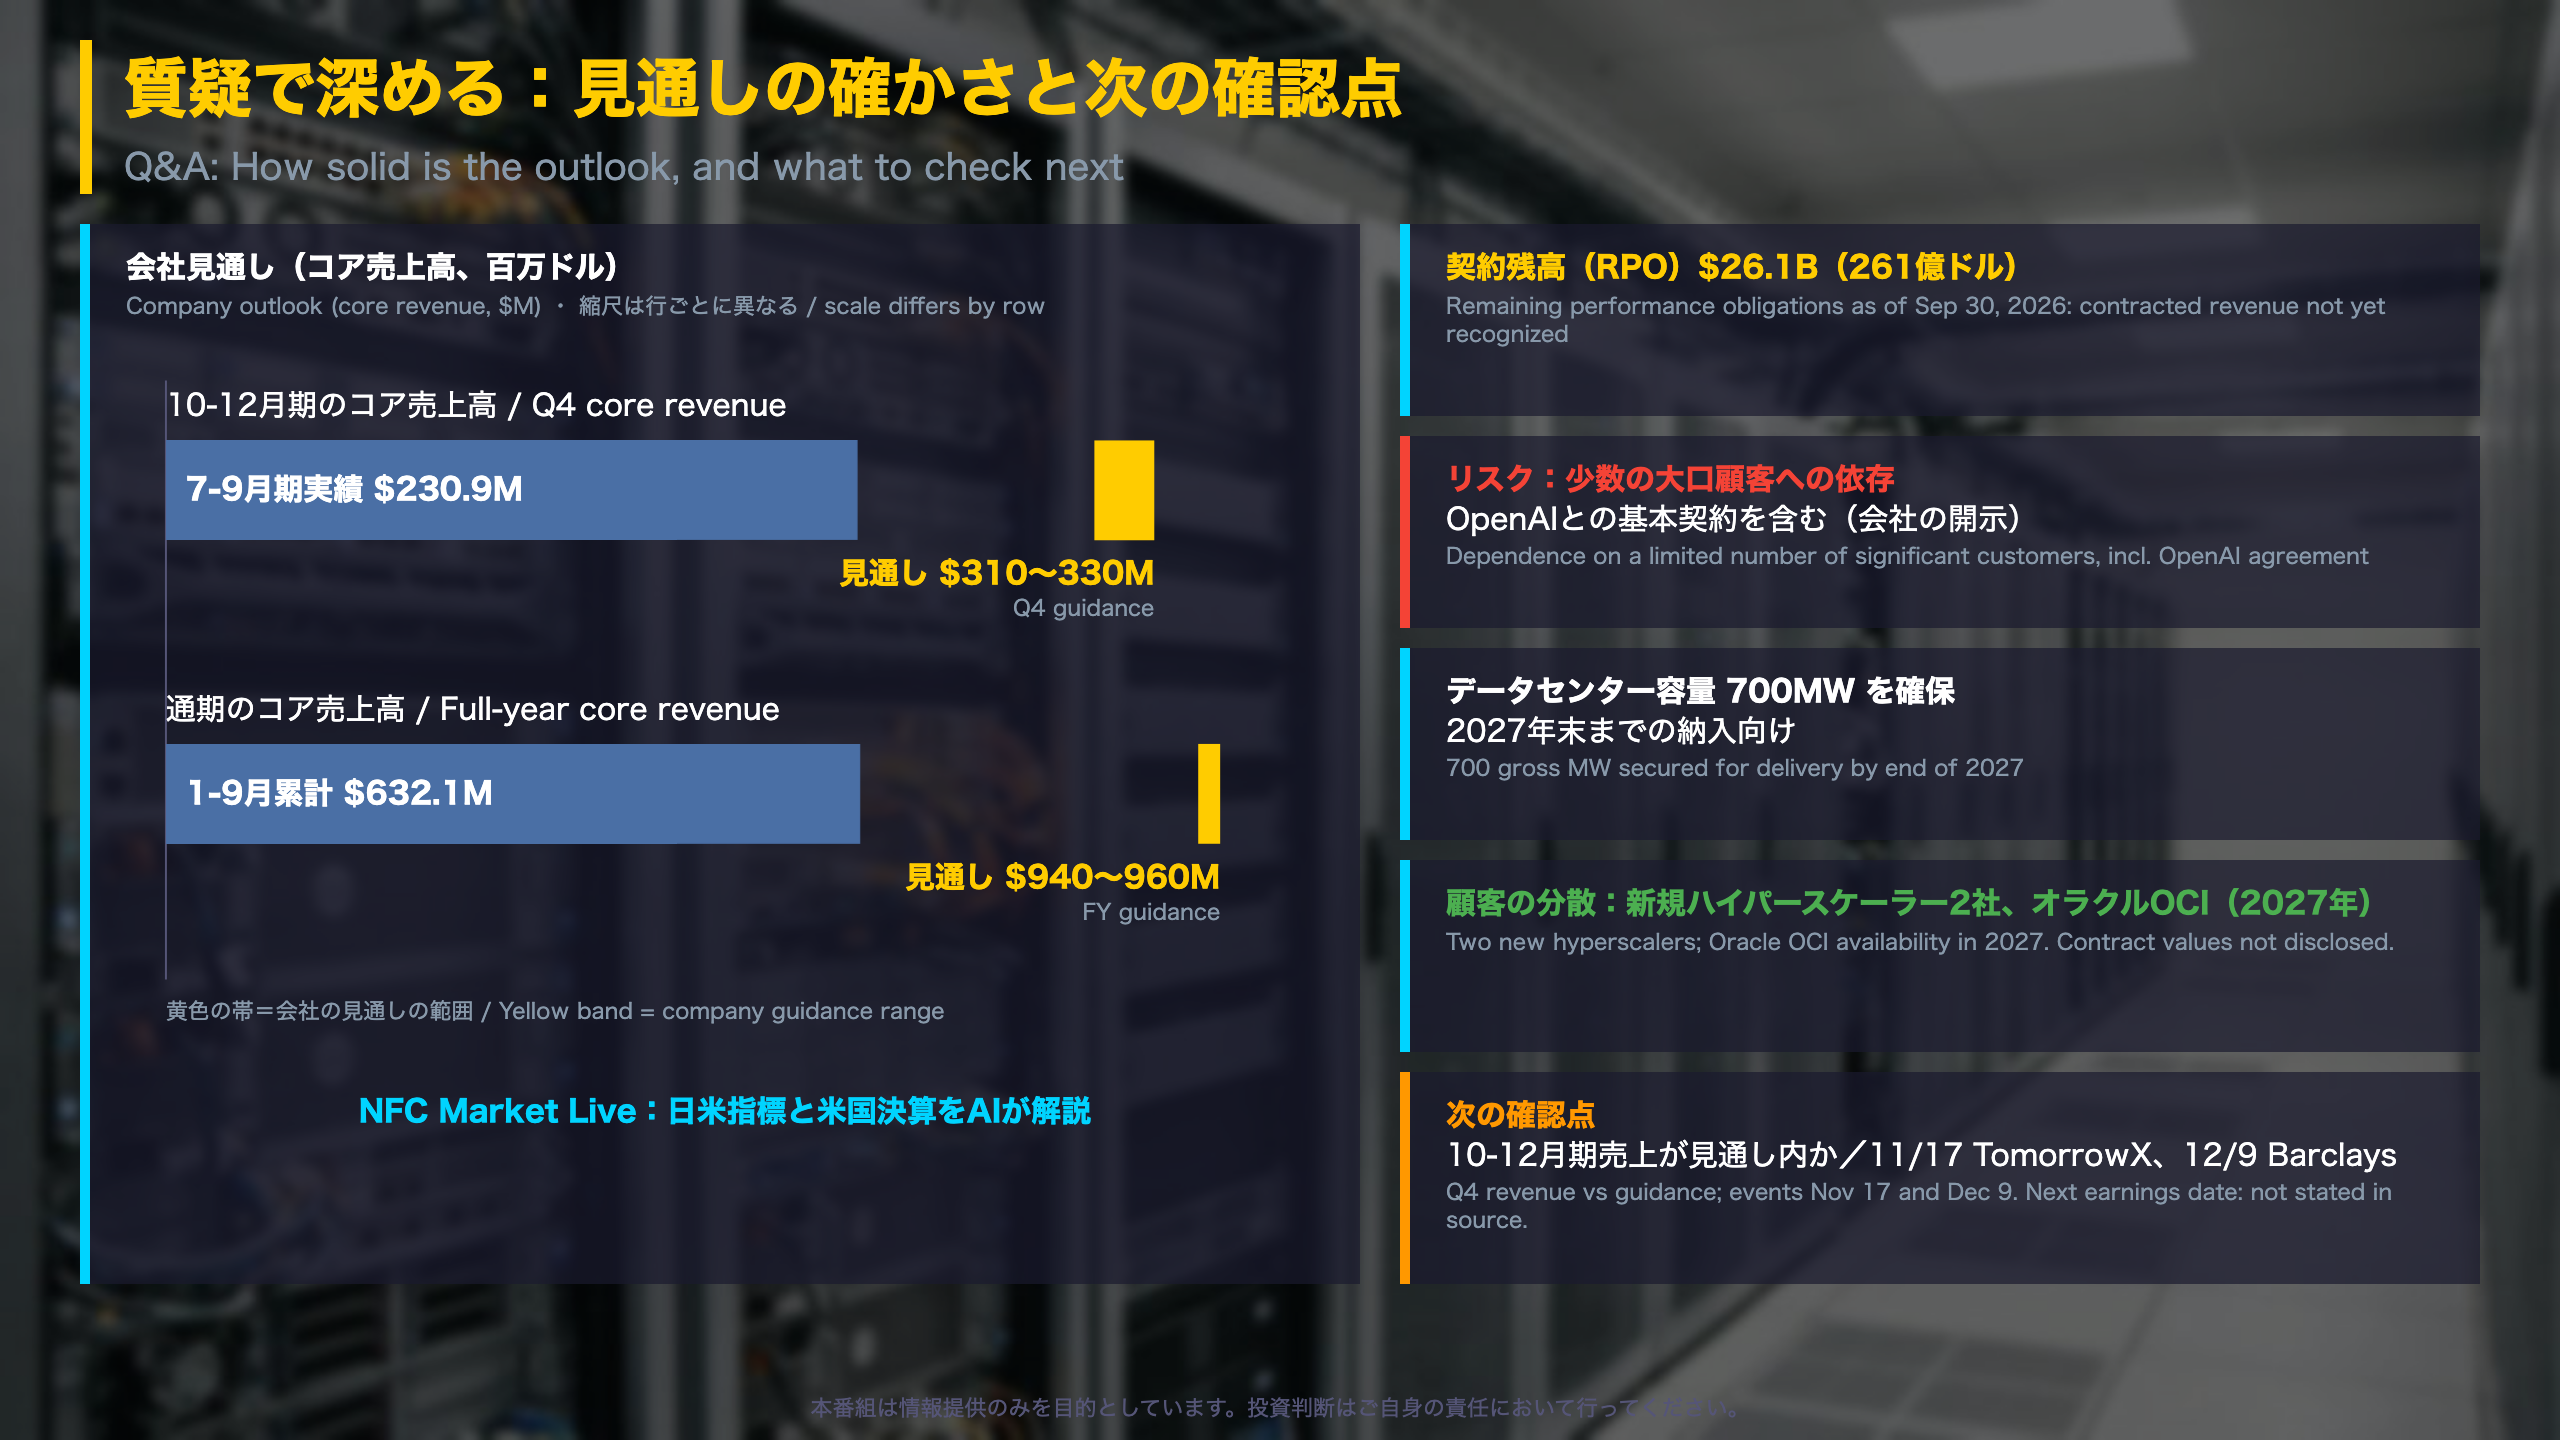
Outlook, Backlog and Risks
Is guidance consistent?
Nine-month core revenue is $632.1M. Adding Q4 guidance of $310-330M gives $942-962M, in line with the full-year range of $940-960M. The release says the full-year outlook was raised; the prior range is not in the source.
Backlog and balance sheet
- Remaining performance obligations: $26.1B
- Cash, restricted cash and short-term investments: $7.8B; debt capacity $850M
- Working-capital loans: about $829M in total
- Customer deposits fell to $108.7M from $354.5M at end-2025
Capacity
700 MW gross secured for delivery by end-2027, plus new European capacity in Norway and Finland.
Risk disclosure
The company cites dependence on a limited number of significant customers, including its Master Relationship Agreement with OpenAI. Converting backlog into revenue also depends on data center delivery schedules.
Two readings
Bull: a large backlog, new hyperscaler wins, and Oracle OCI availability in 2027.
Bear: customer concentration and long delivery timelines.
Calendar
TomorrowX Summit (Nov 17) and Barclays Global Technology Conference (Dec 9). Next earnings date: not stated.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.