This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-11-10 06:23 JST)
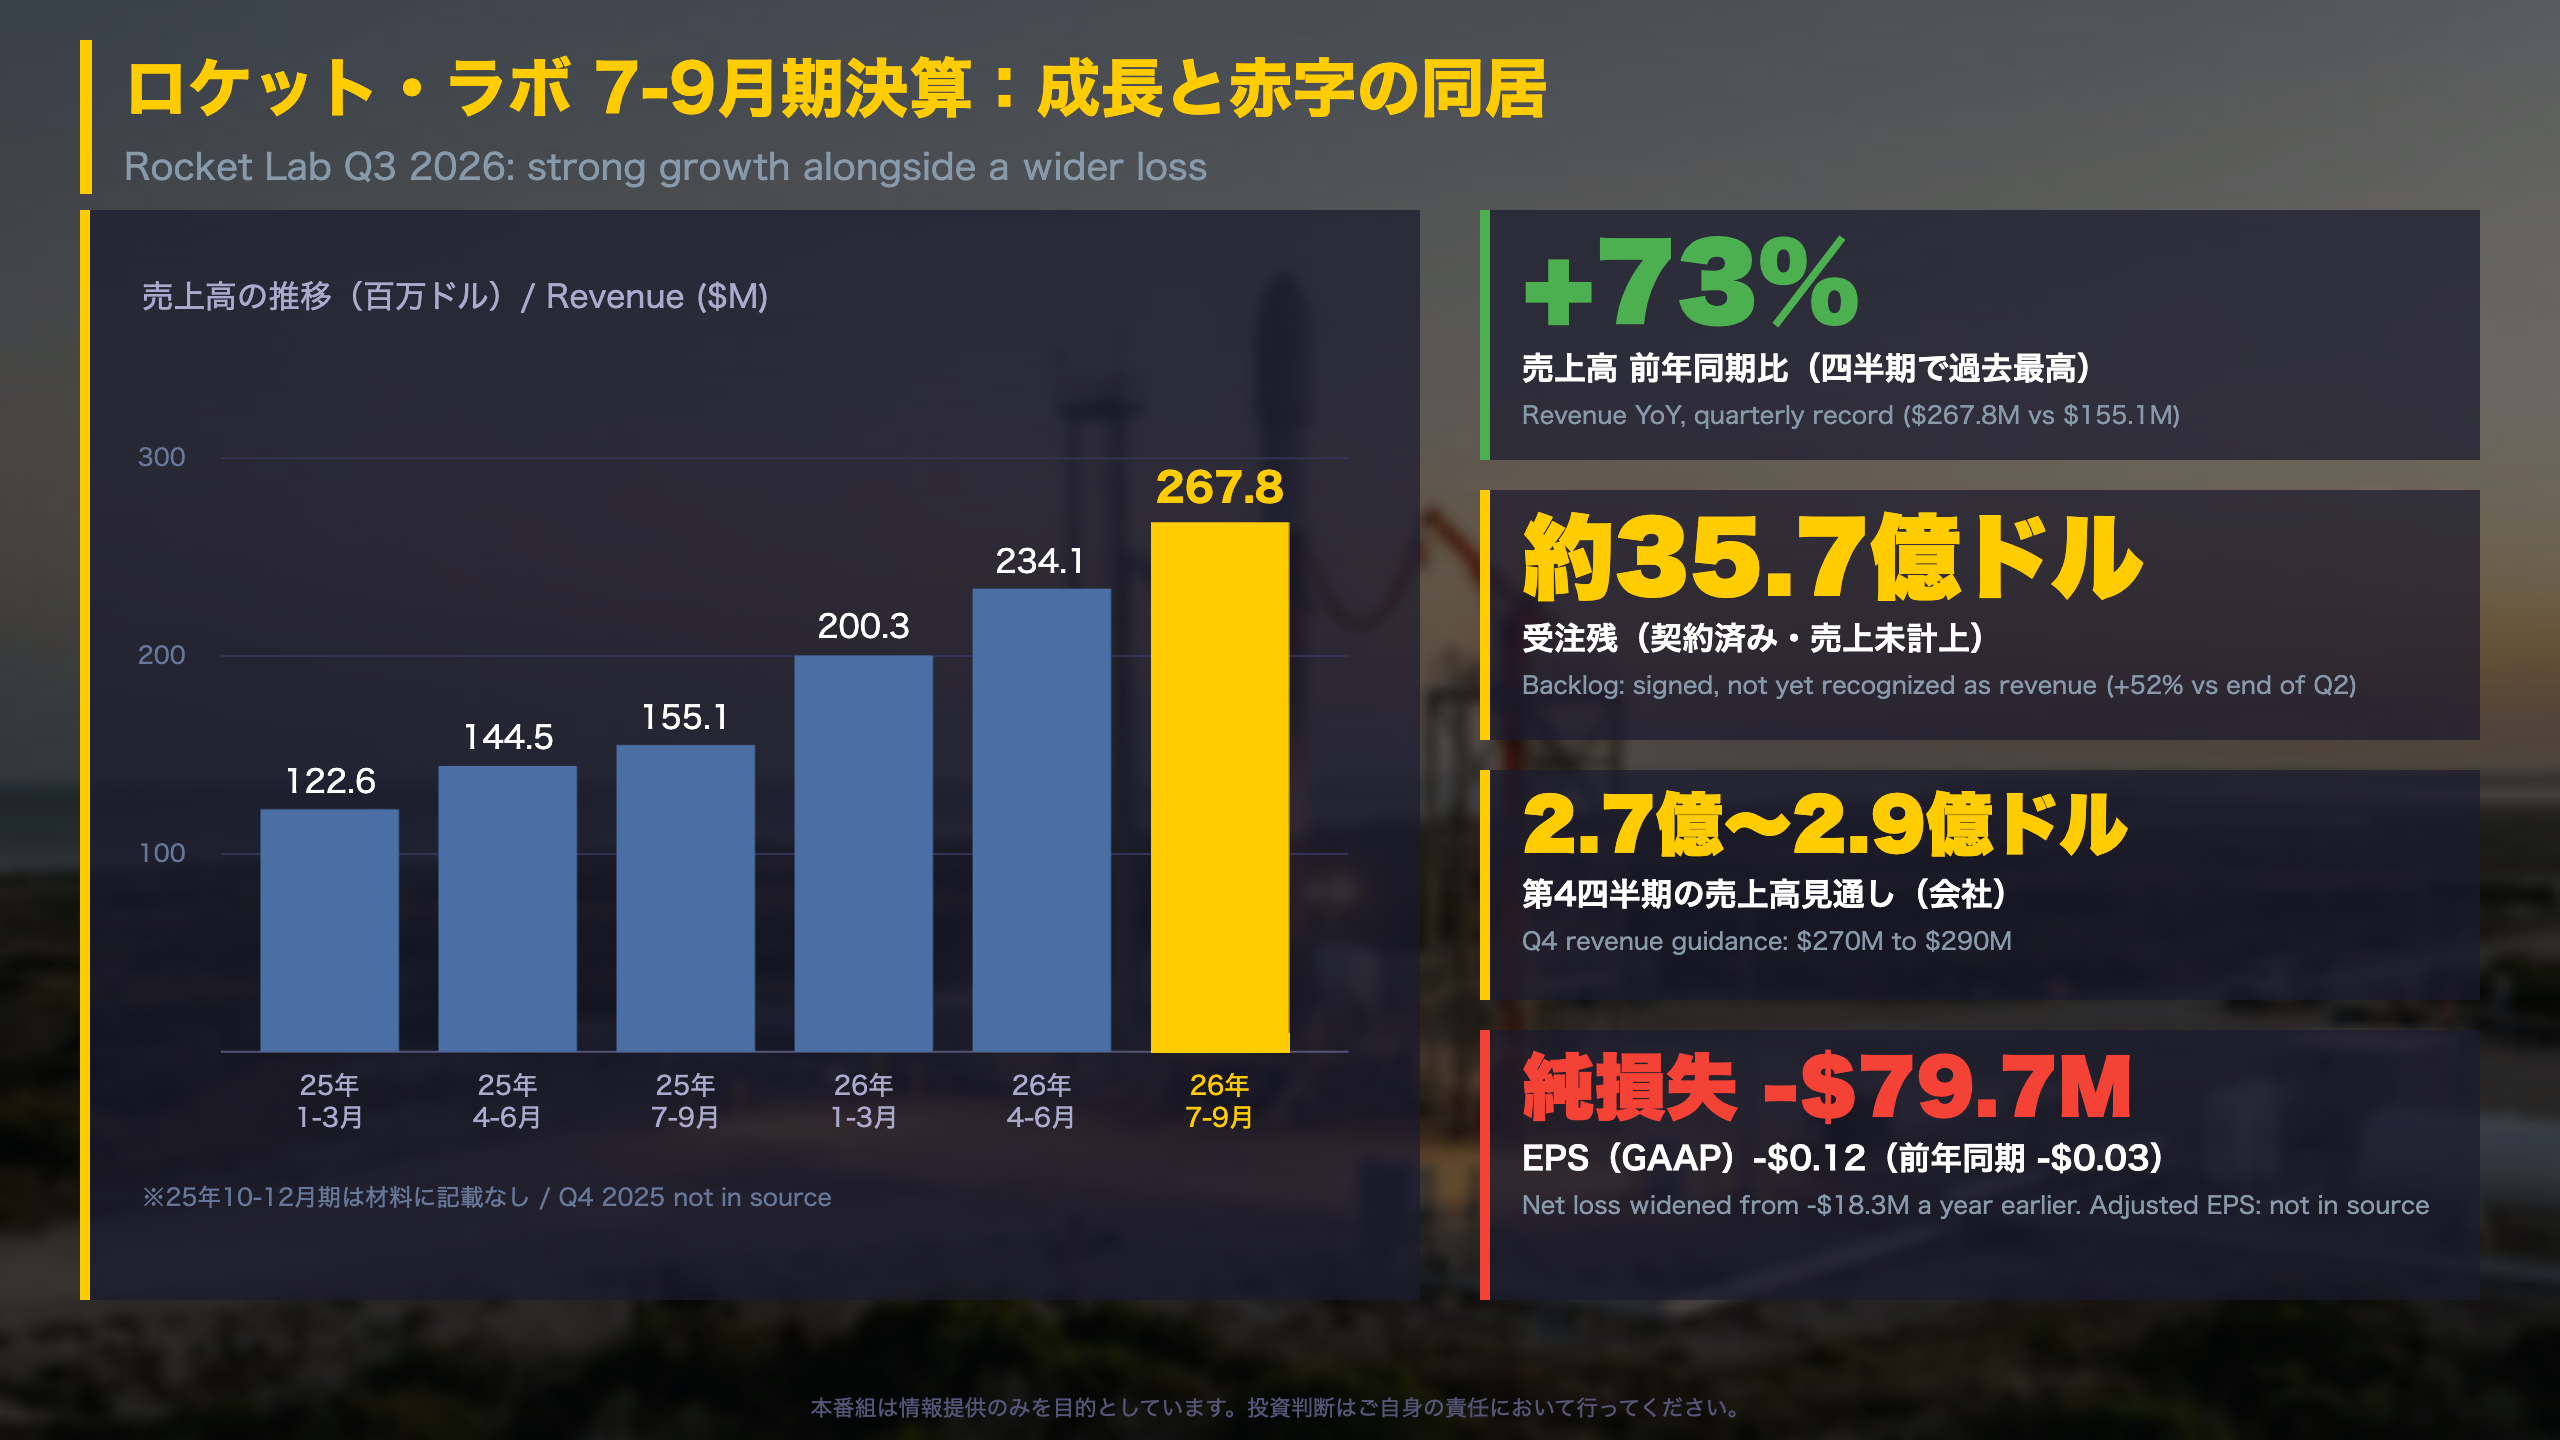
📊 Rocket Lab (RKLB) reported Q3 2026 results: revenue of $267.8M, up 73% year on year and a quarterly record.
📈 Backlog reached about $3.57B, with roughly $1B in new launch contracts signed, including more than $515M for Neutron.
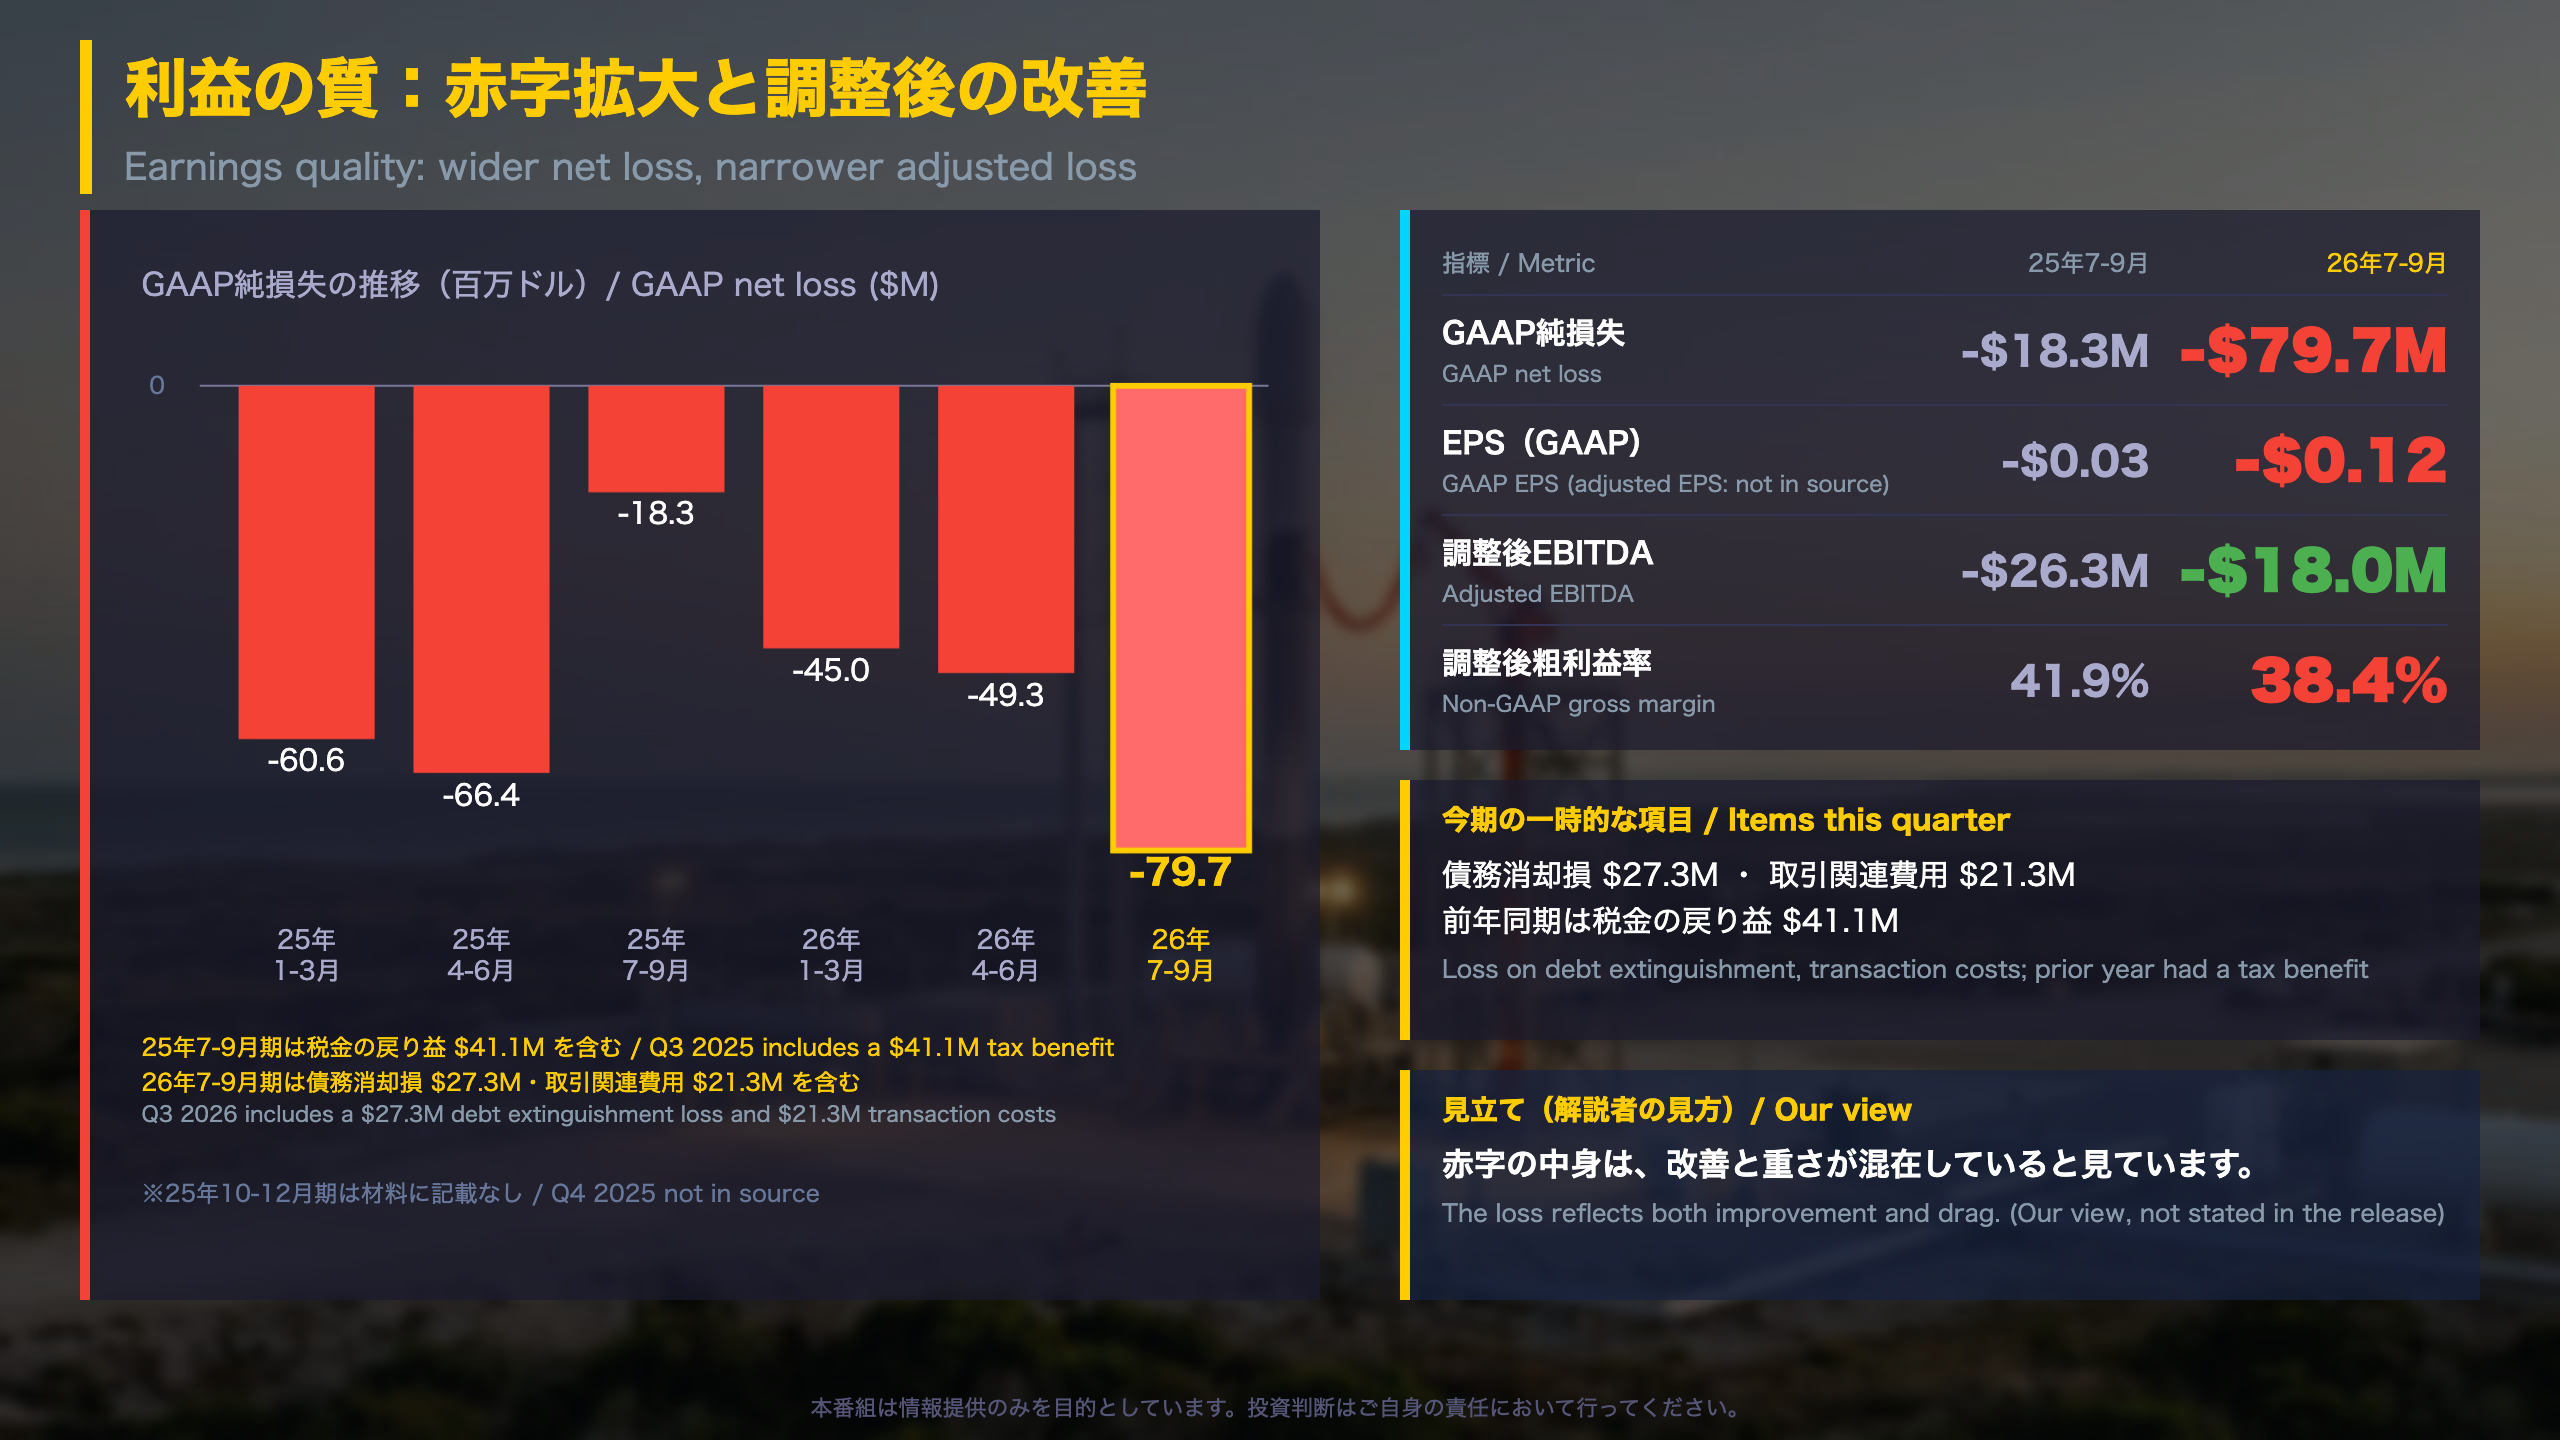
⚠️ The GAAP net loss widened to $79.7M (EPS -$0.12) from $18.3M, including one-time items such as a debt extinguishment loss.
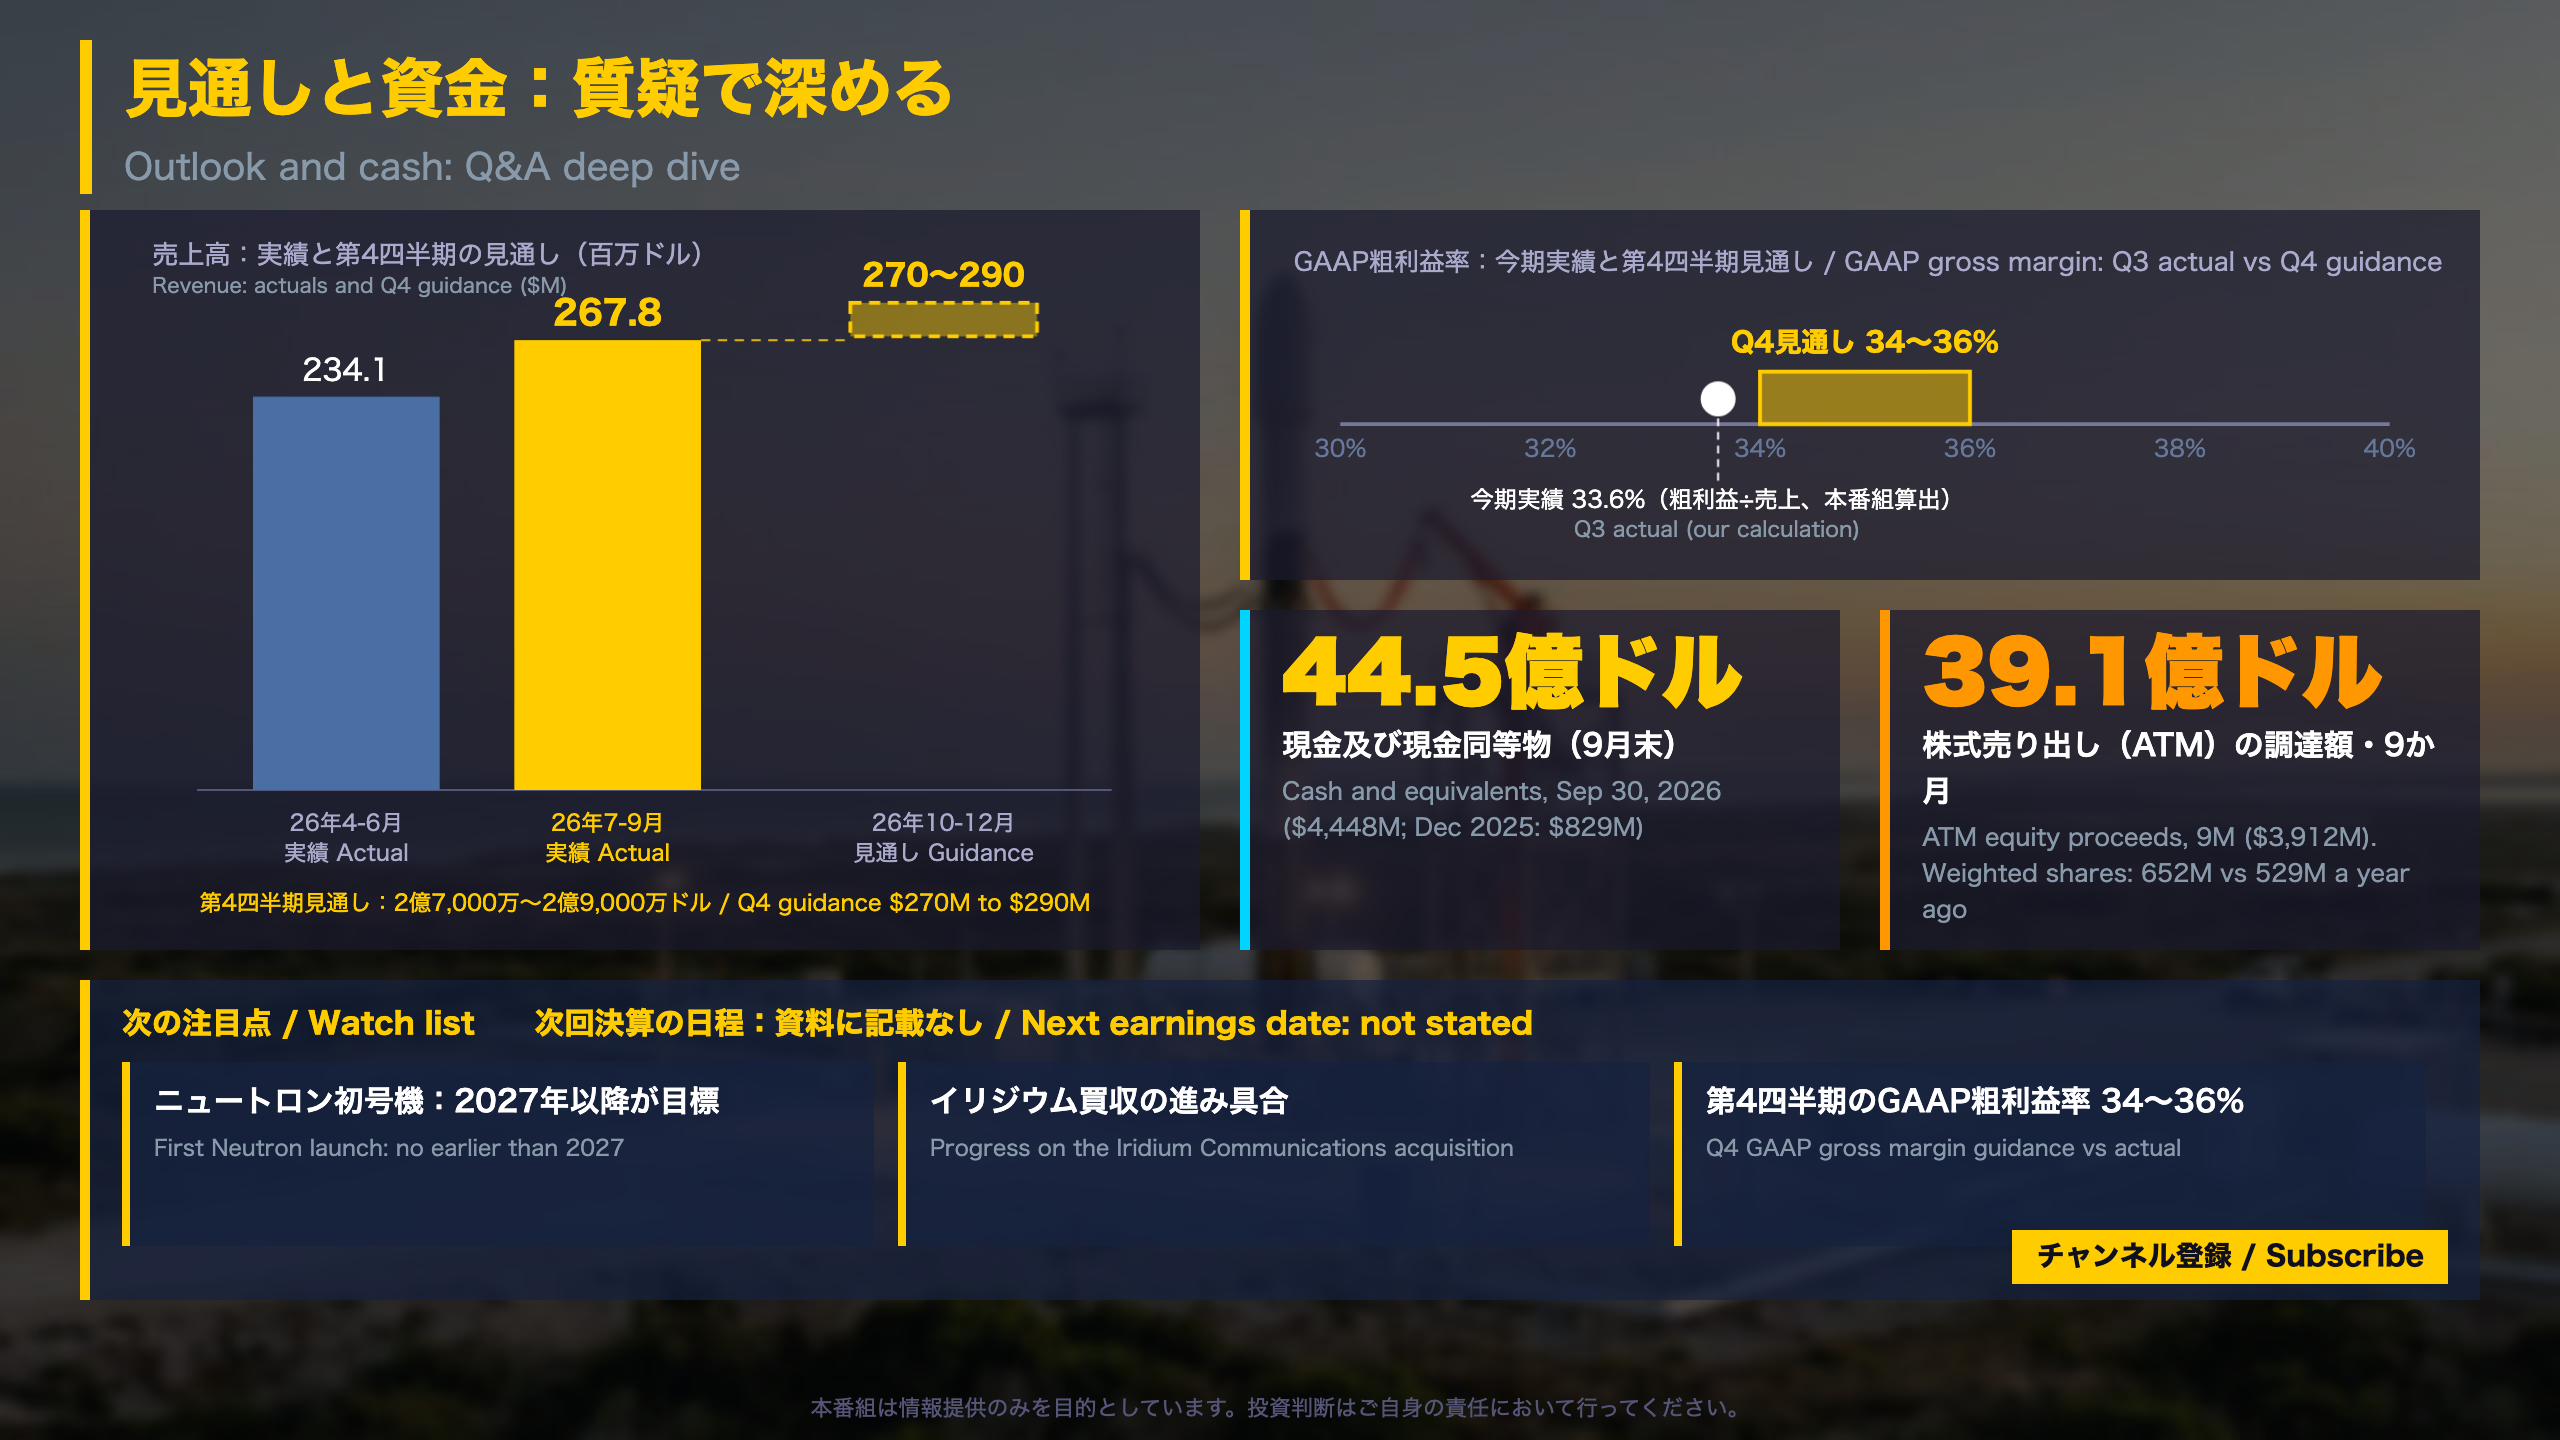
💡 Adjusted EBITDA loss narrowed to $18.0M. Q4 revenue guidance is $270M to $290M. We rely only on the company’s own release, not consensus estimates.
ロケット・ラボ7-9月期決算:成長と赤字の同居
Rocket Lab Q3 2026: record revenue, wider loss
This note covers the Exhibit 99.1 press release that Rocket Lab (Nasdaq: RKLB) furnished to the SEC on November 9, 2026. Exhibit 99.1 is the earnings release attached to a Form 8-K, the filing US companies use to report material events.
Key figures
- Revenue: $267.8M, up 72.7% from $155.1M a year earlier and up $33.8M (+14.4%) from $234.1M in the prior quarter.
- Mix: product revenue +89.8% to $197.5M; service revenue +37.8% to $70.3M.
- Nine months: revenue of $702.2M versus $422.1M, roughly 1.66 times the year-earlier level.
- GAAP net loss: $79.7M (EPS -$0.12) versus $18.3M (EPS -$0.03).
Why GAAP and adjusted figures differ
GAAP follows US accounting rules. Non-GAAP and adjusted EBITDA strip out items management calls unrepresentative, such as stock-based compensation and transaction costs. The release does not give an adjusted EPS, so we do not quote one.
Reading the guidance
Q4 revenue guidance of $270M to $290M implies roughly +0.8% to +8.3% sequential growth, slower than the +14.4% seen this quarter. That is a fact about the range, not a forecast.
What to watch
The release does not state the next earnings date. The first check is whether Q4 actuals land inside the guided range. We do not rely on consensus estimates in this programme.
受注残の中身:打ち上げ契約とNeutron
Inside Rocket Lab’s backlog
What the release says
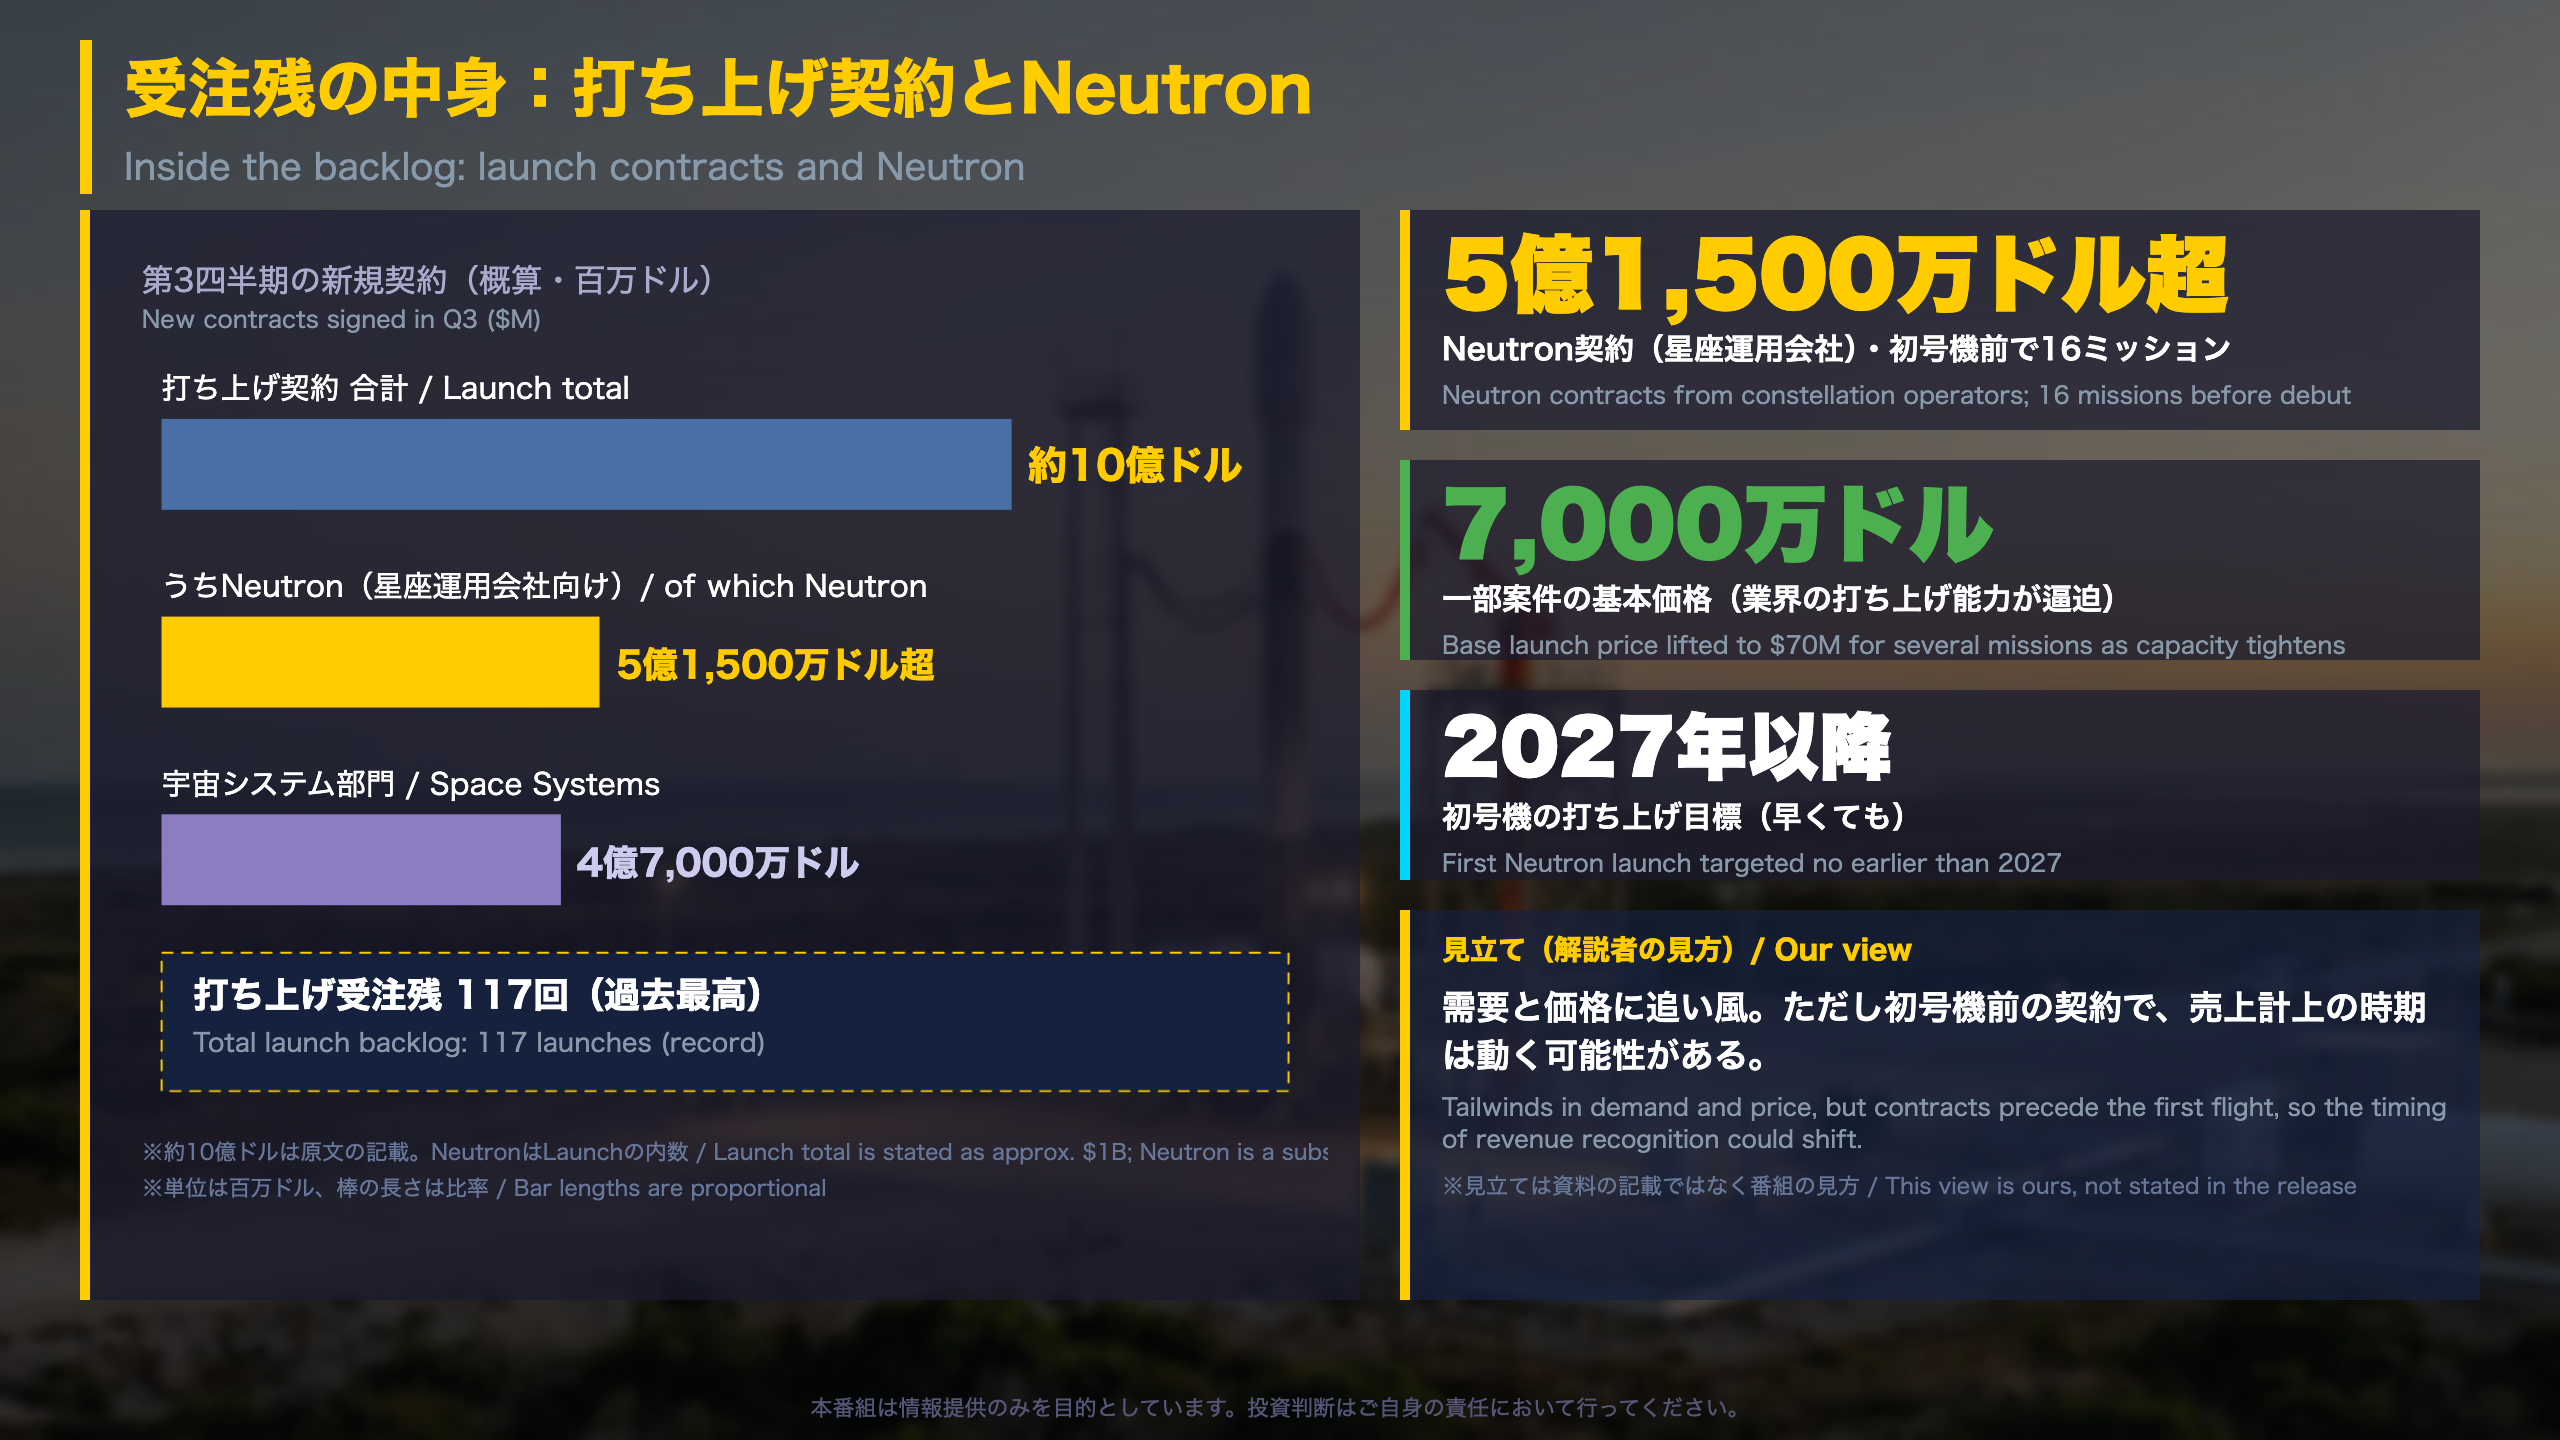
Backlog is the value of signed contracts not yet recognized as revenue. Rocket Lab reports about $3.57B, up 52% (about $1.2B) from the end of Q2.
– Launch: roughly $1B of new contracts across Electron, HASTE and Neutron, taking launch backlog to a record 117 launches.
– Neutron: more than $515M signed from constellation operators, lifting its pre-debut backlog to 16 missions. Electron is the company’s small-lift rocket; Neutron is the upcoming reusable medium-lift vehicle, a different payload class.
– Pricing: the base launch price rose to $70M for several Neutron missions as industry capacity tightens.
– Space Systems: $470M signed; more than 55 spacecraft are in build.
Balance sheet cross-check
Contract liabilities, which largely reflect customer advances, rose to $423.6M from $195.4M at year-end, and inventories to $280.9M from $158.4M. Both are consistent with a business scaling up, though the release does not itemize them.
Two readings
Supportive: price increases and large contracts point to firm demand. Cautious: Neutron has not flown, with a first launch targeted no earlier than 2027, and the release gives no schedule for converting backlog into revenue.
What to monitor
Milestones for Neutron hardware delivery to Launch Complex 3 and any change to the 2027 target. Investors comparing with other launch providers should note that backlog definitions differ by company.
利益の質:赤字拡大と調整後の改善
Earnings quality: reading the wider loss
GAAP versus adjusted
GAAP net loss widened to $79.7M from $18.3M, while adjusted EBITDA loss narrowed to $18.0M from $26.3M. Adjusted EBITDA excludes interest, taxes, depreciation, amortization, stock-based compensation and items management deems unrepresentative; it is a company-defined measure, not a GAAP figure.
What drove the gap
- Tax: Q3 2025 booked a $41.1M tax benefit; Q3 2026 booked a $3.5M provision.
- One-time items: a $27.3M loss on extinguishment of debt and $21.3M of transaction costs this quarter.
- Operating costs: GAAP operating expenses rose 45.6% to $169.3M; non-GAAP operating expenses rose 32.7% to $130.2M.
- Interest: interest income rose to $28.6M from $6.7M while interest expense fell to $0.3M.
Margin detail (our calculation)
Product gross margin improved to roughly 32.6% from 30.0%, while service gross margin fell to roughly 36.5% from 51.2%. Non-GAAP gross margin was 38.4% versus 41.9%.
Two readings
Constructive: adjusted loss measures narrowed and quarterly operating cash flow turned positive at $7.2M. Cautious: margins slipped, and nine-month operating cash flow remained negative at $127.3M.
Watch next
Q4 guidance calls for GAAP operating expenses of $162M-$168M and an adjusted EBITDA loss of $14M-$20M. Investors comparing with US peers should remember that non-GAAP definitions vary by company.
見通しと資金:質疑で深める
Outlook and funding: what the release lets us verify
Guidance versus Q3 actuals
| Item | Q3 2026 | Q4 2026 guidance |
|---|---|---|
| Revenue | $267.8M | $270M-$290M |
| GAAP gross margin | ~33.6% (our calc.) | 34%-36% |
| Non-GAAP gross margin | 38.4% | 39%-41% |
| GAAP opex | $169.3M | $162M-$168M |
| Adjusted EBITDA | -$18.0M | -$14M to -$20M |
Funding
Cash and equivalents were $4.45B at September 30, versus $829M at year-end. Nine-month proceeds from ATM offerings, where a company sells new shares gradually into the open market, were $3.91B. The company states it has fully funded the pending Iridium Communications acquisition through a completed ATM offering, with lender and shareholder approvals obtained. The purchase price is not given in this document.
Dilution is part of the picture
Weighted-average shares rose to 652.3M from 528.7M a year earlier (about +23%), and Q4 guidance assumes 681M basic weighted shares including about 41M Series A convertible participating preferred shares.
Two readings
Constructive: guidance implies higher revenue, a slightly higher gross margin and a smaller adjusted EBITDA loss. Cautious: nine-month operating cash flow is -$127.3M and per-share metrics are affected by the rising share count.
What to watch
The next earnings date is not stated. Key checks: first Neutron launch timing (no earlier than 2027), Iridium deal progress, and Q4 gross margin versus the guided range. Guidance is forward-looking and subject to the risks listed in the company’s filings.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.