📺 Watch the Full Video Analysis
This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-11-06 06:35 JST)
📊 Cloudflare (NET) reported Q3 2026 results on November 5, 2026.
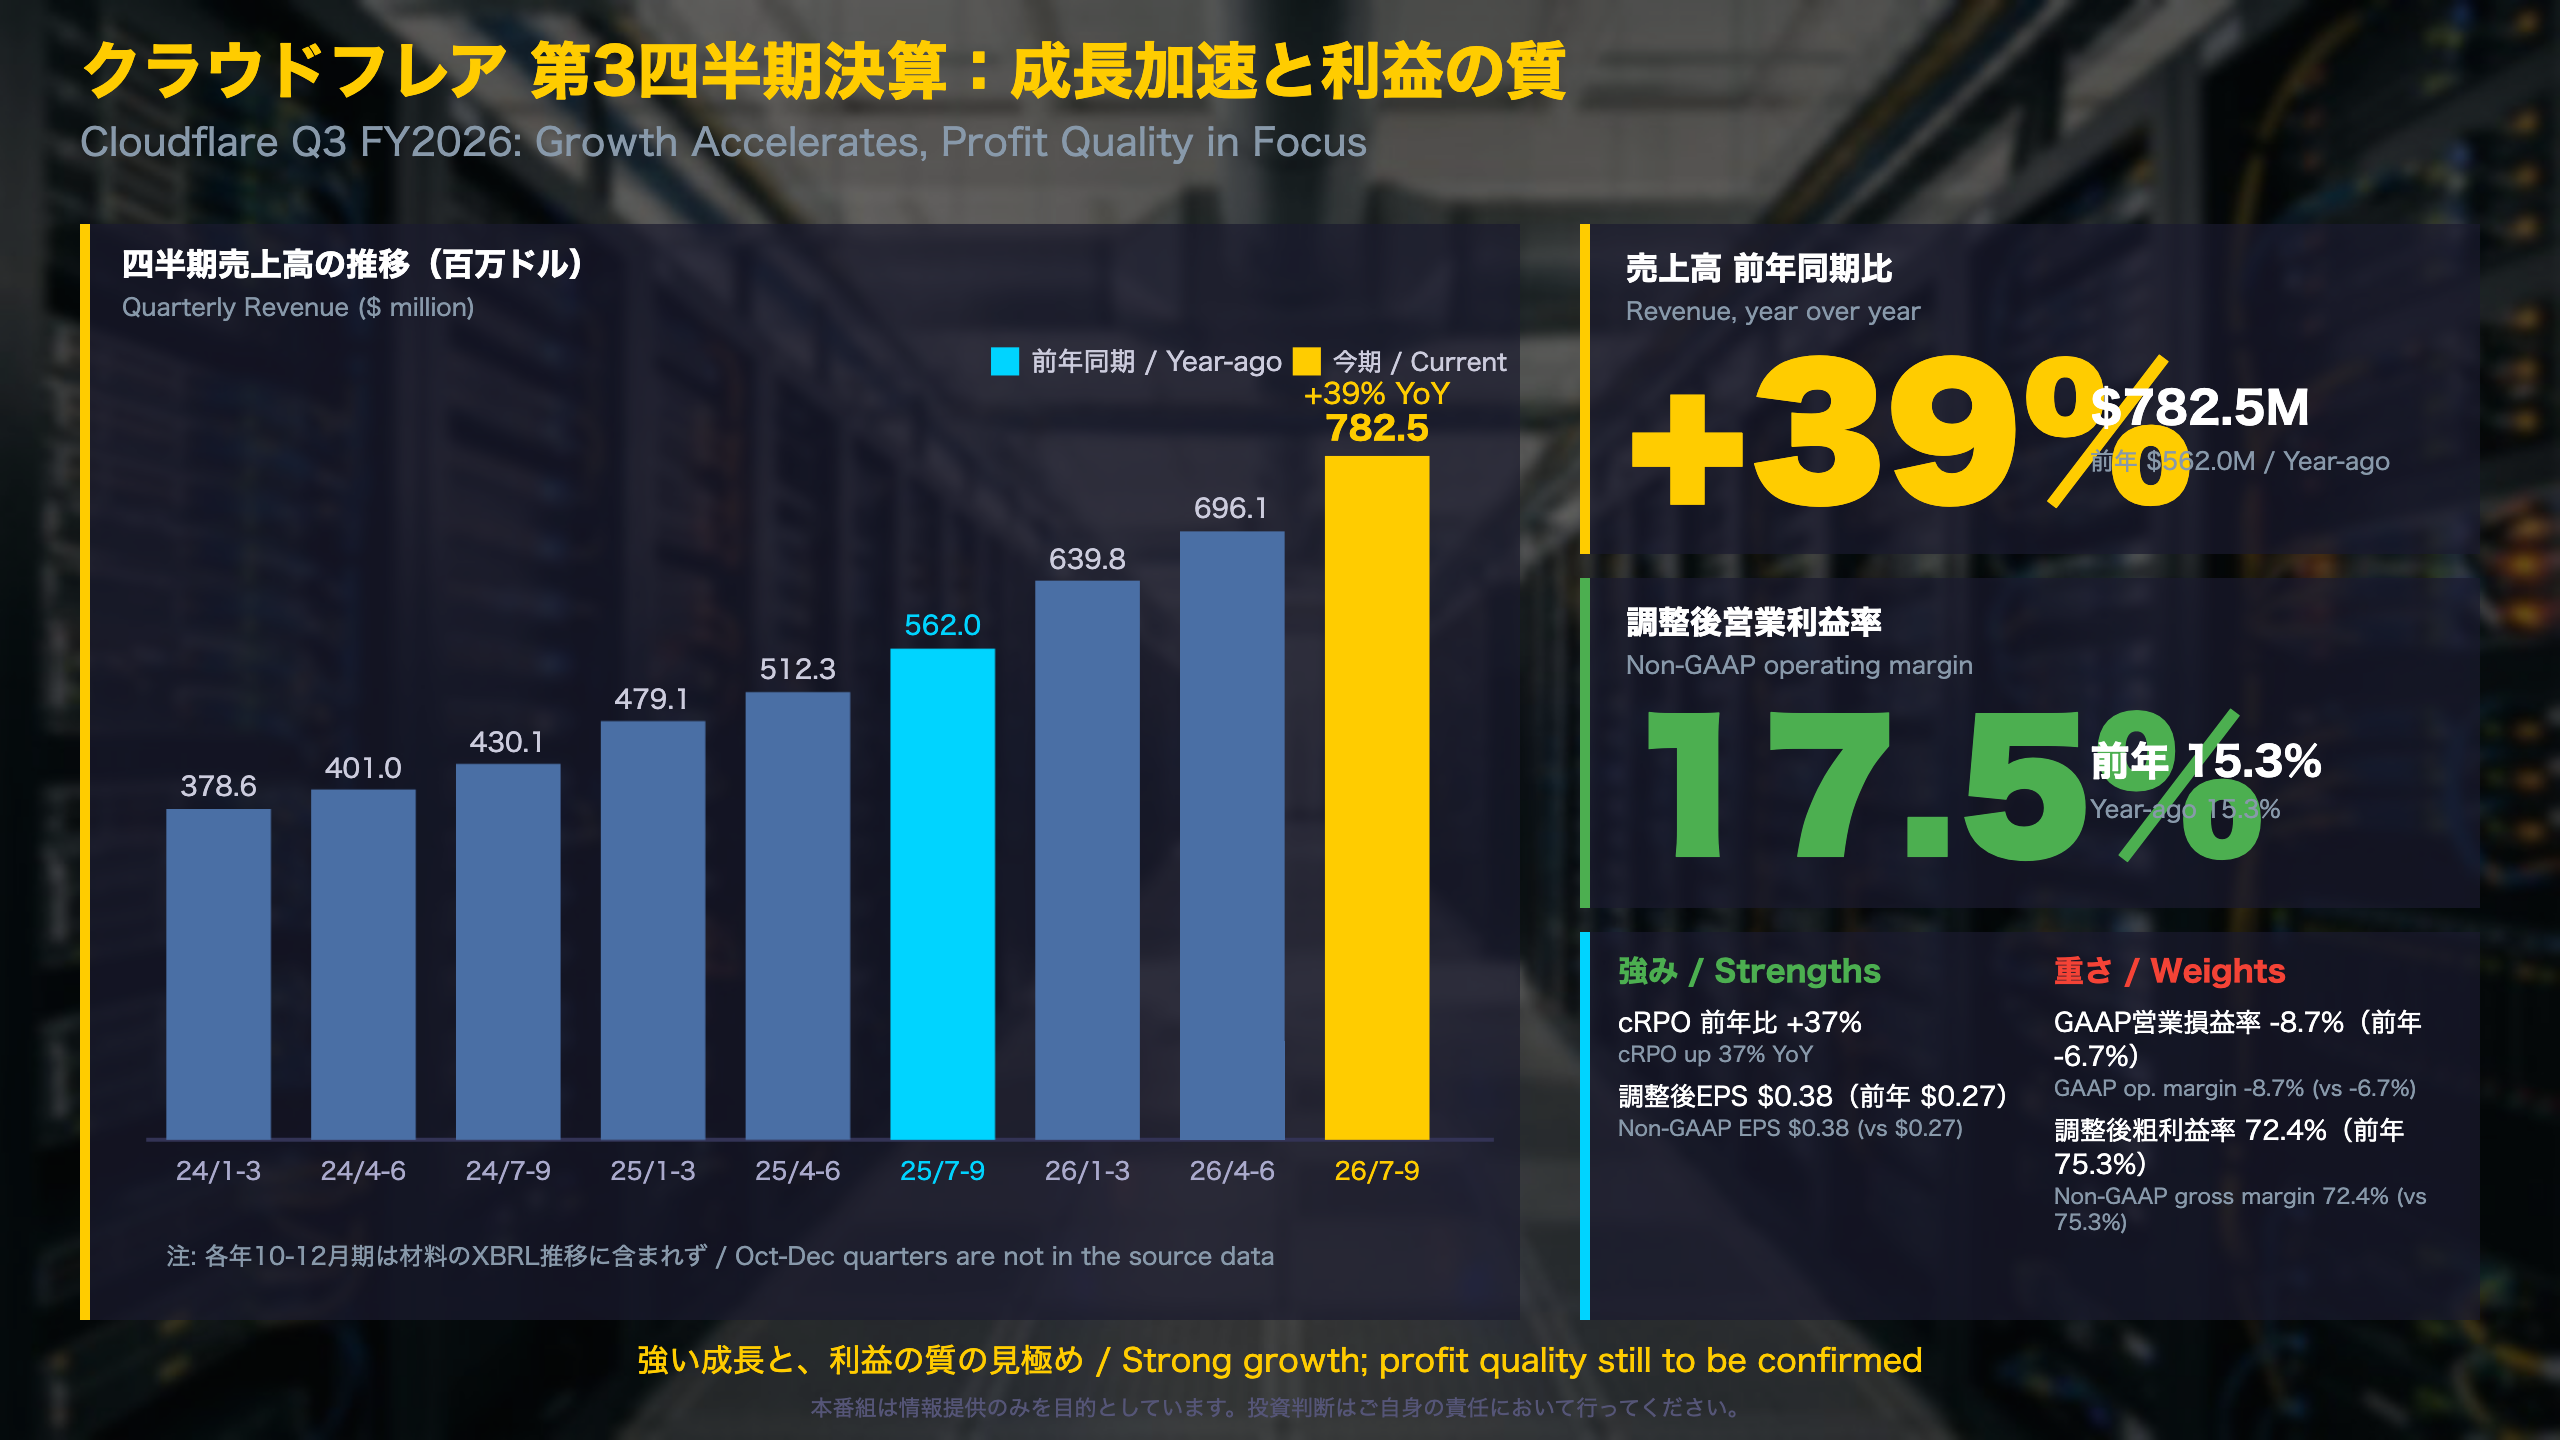
📈 Revenue was $782.5 million, up 39% year over year. Non-GAAP operating margin improved to 17.5% (15.3% a year ago) and non-GAAP EPS was $0.38 ($0.27 a year ago).
⚠️ On a GAAP basis the operating loss was $67.9 million, and non-GAAP gross margin slipped to 72.4% from 75.3%.
💡 Q4 revenue guidance is $845.0-846.0 million. The company also named a new President of Revenue.
We walk through both the strengths and the weights in this report.
サマリー:売上39%増、成長加速と利益の質
Cloudflare Q3 2026: The Big Picture
Who reports this? Cloudflare (NYSE: NET) filed this earnings release as Exhibit 99.1 to a Form 8-K with the US Securities and Exchange Commission. The 8-K is the standard way US-listed companies disclose material news such as quarterly results.
Headline numbers
- Revenue: $782.5 million, up 39% year over year (from $562.0 million).
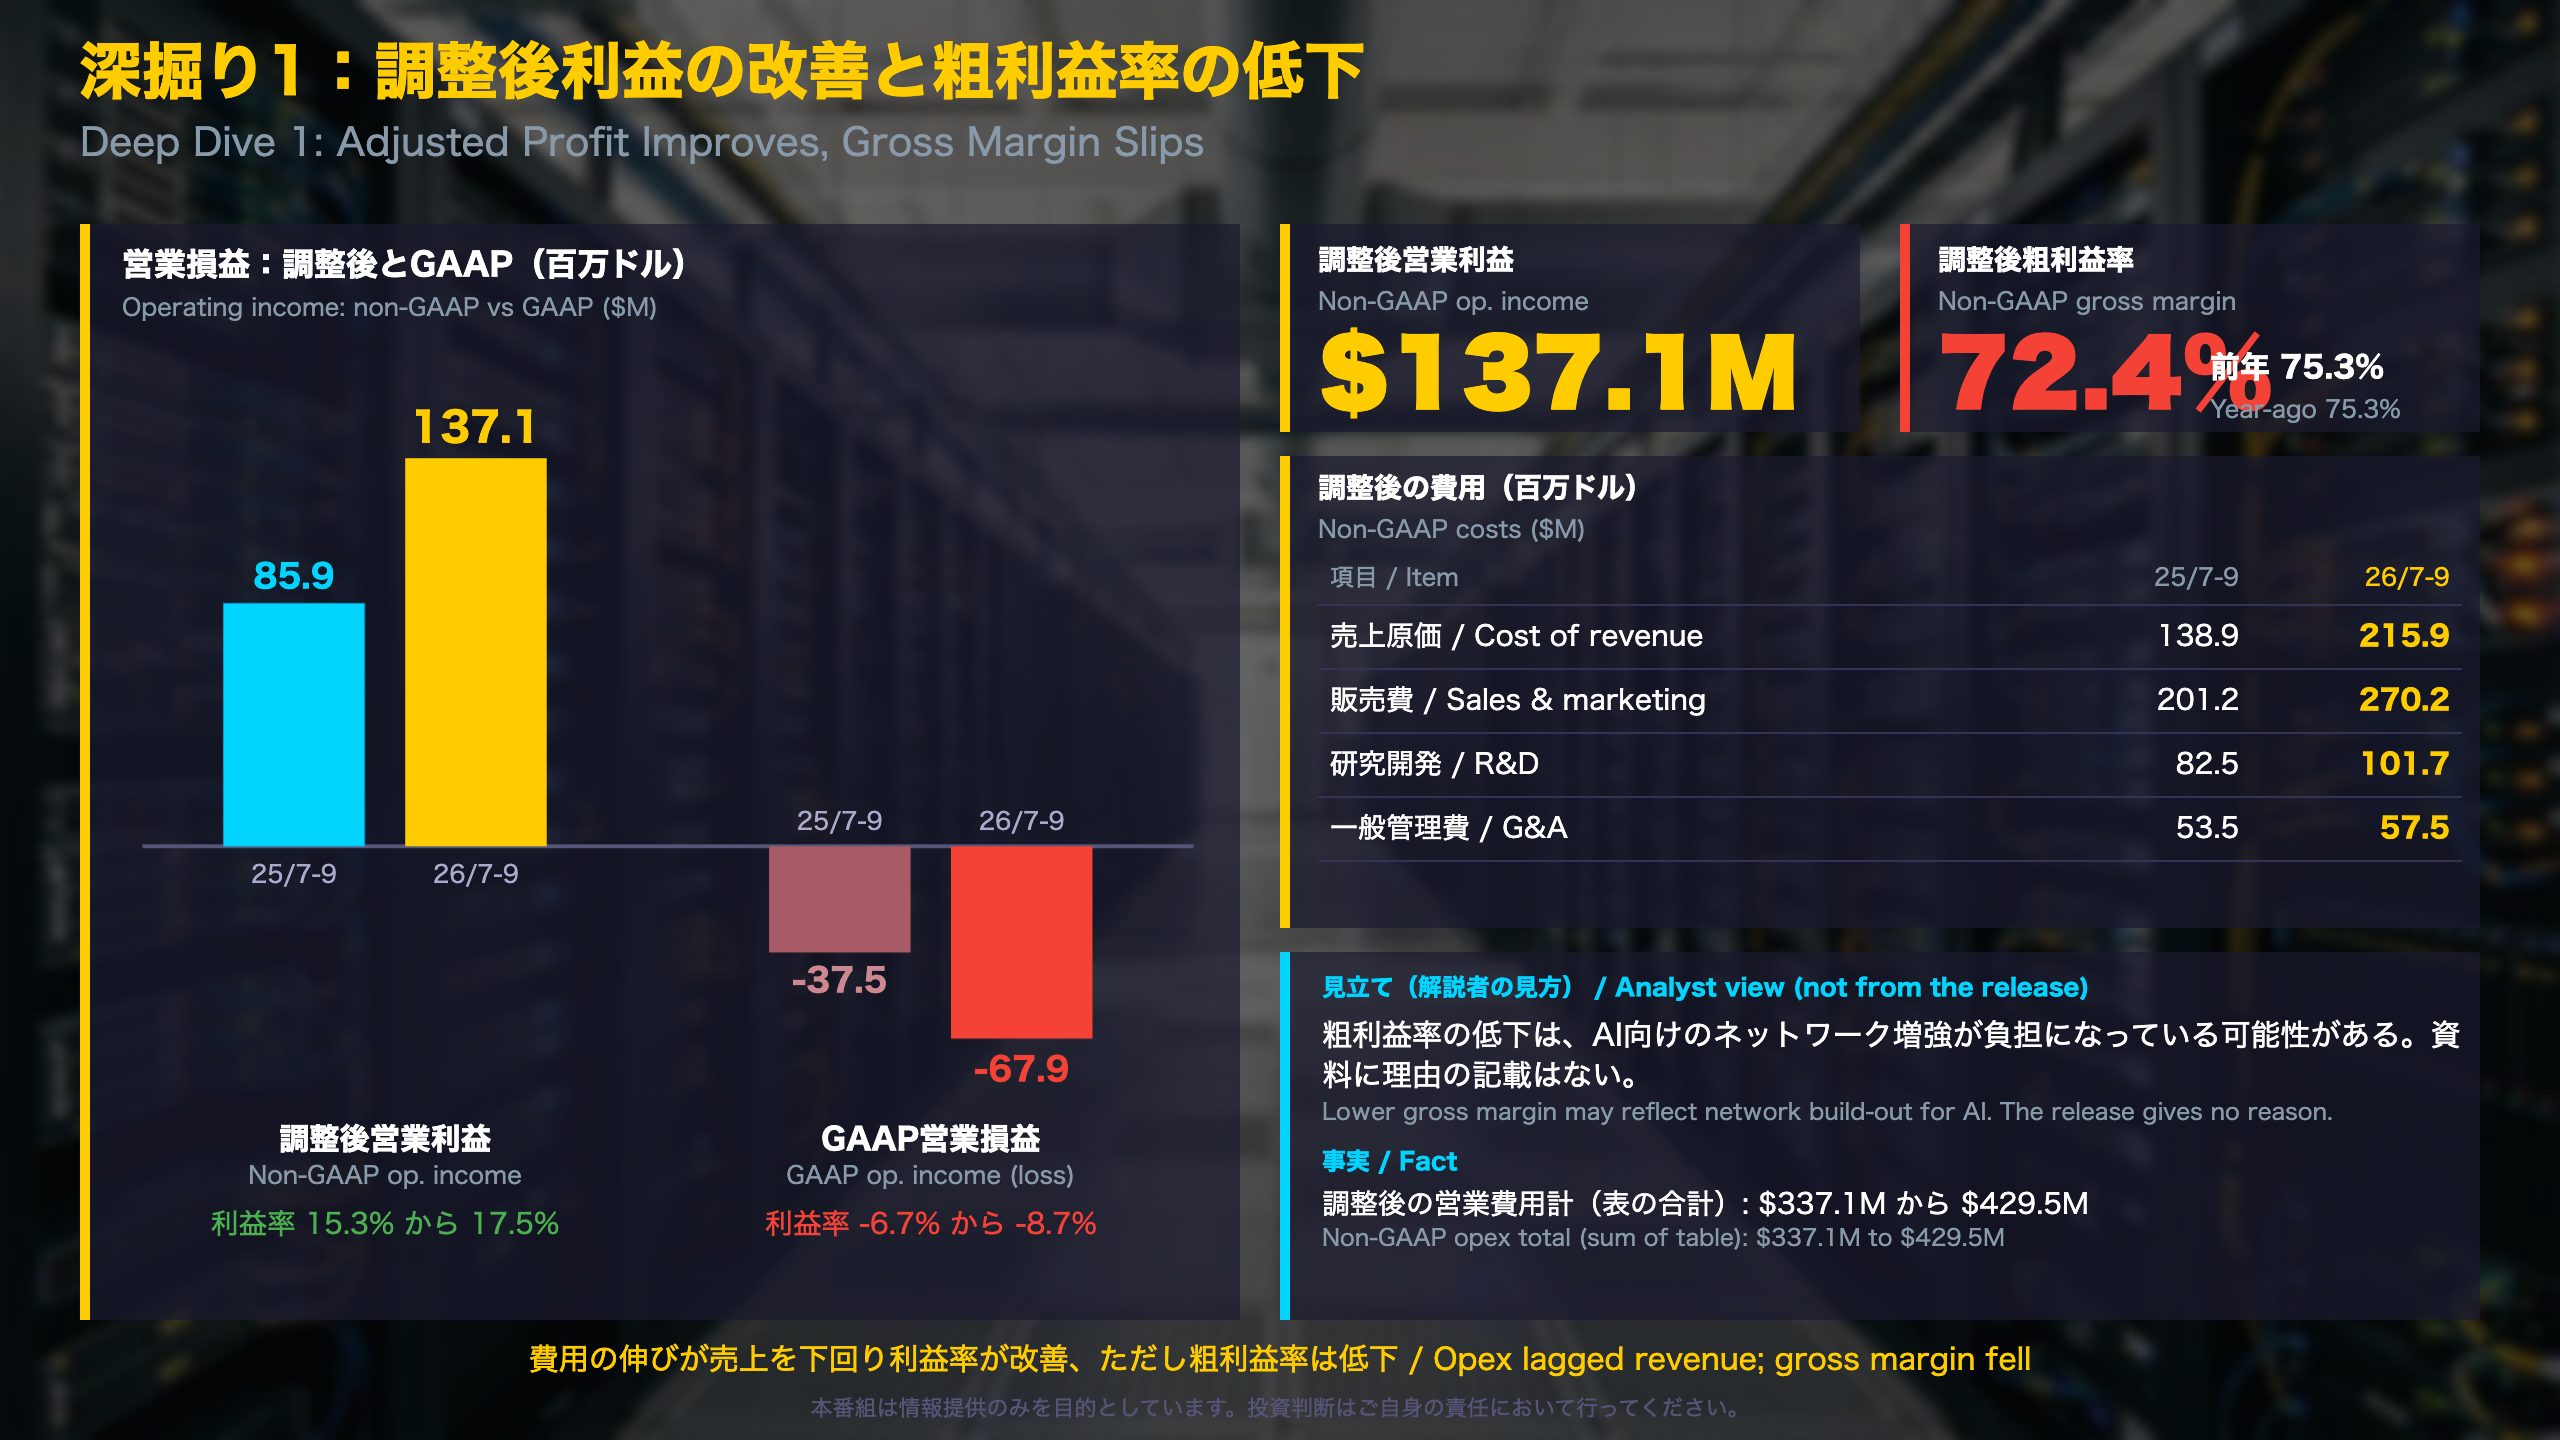
- Non-GAAP operating margin: 17.5% versus 15.3% a year ago.
- GAAP operating loss: $67.9 million (8.7% of revenue) versus a $37.5 million loss a year ago.
- Current RPO (contracted revenue expected to be recognized over roughly the next twelve months) grew 37%.
Why GAAP and non-GAAP differ
US companies report under GAAP, but many also publish adjusted ‘non-GAAP’ figures. Cloudflare’s non-GAAP numbers exclude stock-based compensation, amortization of acquired intangibles, legal items and restructuring. Investors in the US and Japan alike usually read both versions side by side.
Trend context
The XBRL history in the source shows quarterly revenue rising from $378.6 million in Q1 2024 to $696.1 million in Q2 2026, so this quarter is the highest in the table. The table omits October-December quarters.
Two readings
The constructive reading is faster growth together with a wider adjusted margin. The cautious reading is a larger GAAP loss and lower gross margin. Both are single-quarter facts, and neither alone proves a trend.
What to watch
Guidance for Q4 revenue is $845.0-846.0 million. The release does not state the next earnings date.
深掘り1:調整後利益の改善と粗利益率の低下
Cloudflare Q3 2026: Costs, Margins and the Gross Margin Dip
Reading the non-GAAP cost lines
Cloudflare reports ‘non-GAAP’ results that strip out stock-based compensation and similar items. On that basis, operating expenses (sales and marketing, R&D, and G&A) rose from $337.1 million to $429.5 million, an increase of roughly 27% against revenue growth of 39%. As a share of revenue, sales and marketing fell from 35.8% to 34.5%, R&D from 14.7% to 13.0%, and G&A from 9.5% to 7.4% (our calculations from the release tables). That spread is why adjusted operating income reached $137.1 million.
The gross margin side
Non-GAAP cost of revenue rose about 55% to $215.9 million, faster than revenue, so non-GAAP gross margin slipped to 72.4% from 75.3%. The release gives no explanation. Our view, labeled as interpretation, is that network and infrastructure build-out for AI-related workloads could be a factor, and the company’s CEO describes the business as ‘the development platform for the AI-powered Internet’.
International context
US software and infrastructure companies are commonly judged on both gross margin and operating leverage. For Japanese readers, the closest analogy is watching the cost-of-sales ratio and the SG&A ratio together in a Japanese company’s quarterly summary (tanshin).
Two readings
- Constructive: cost ratios fell across all three operating expense lines.
- Cautious: if cost of revenue keeps outgrowing revenue, it narrows room for further margin gains. This is a single quarter, so no trend can be confirmed.
What to watch
Q4 guidance implies a higher adjusted operating margin than Q3 at the midpoint, but no gross margin guidance is provided.
深掘り2:GAAP赤字の中身とキャッシュ
GAAP Loss, Balance Sheet and Free Cash Flow
Bridging GAAP to non-GAAP operating income ($M)
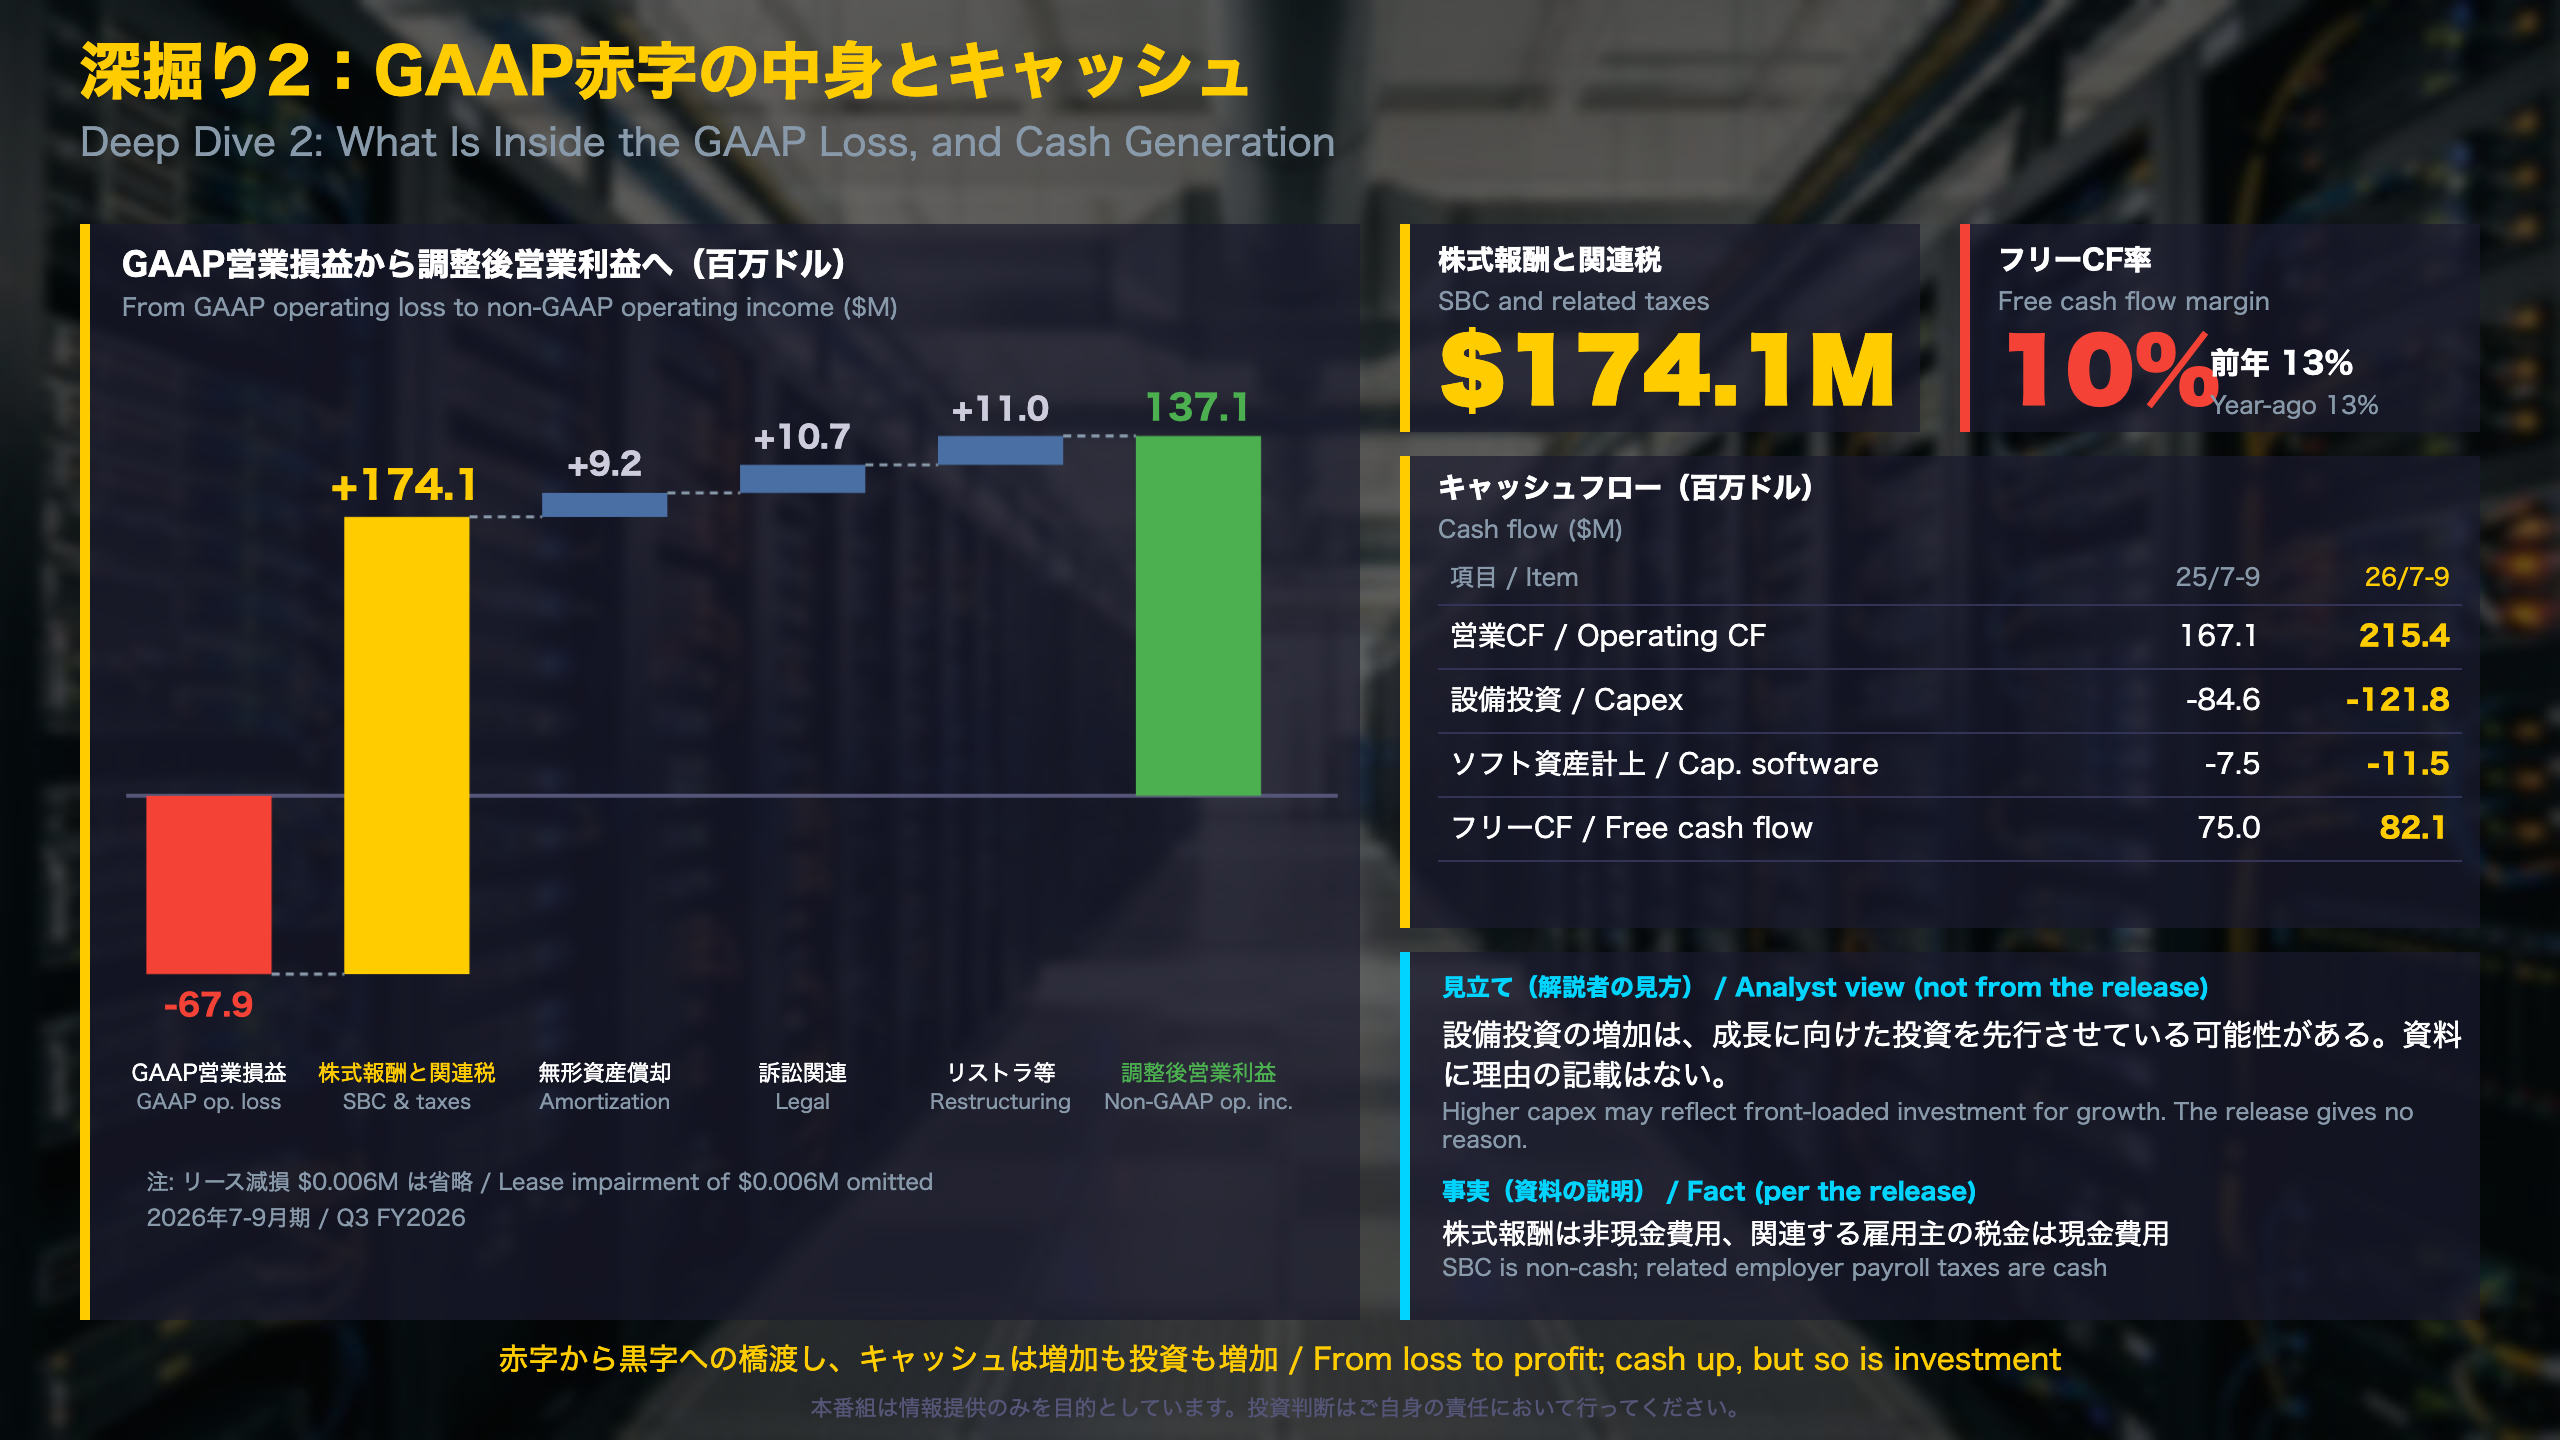
Start with the GAAP operating loss of -67.9. Add stock-based compensation and related payroll taxes (+174.1), amortization of acquired intangibles (+9.2), legal reserves and settlements (+10.7) and restructuring (+11.0), and you reach non-GAAP operating income of 137.1. By our calculation from the release, stock-based compensation and related taxes equal 22.2% of revenue, versus 21.3% a year ago.
Why it matters
The release classes stock-based compensation as a non-cash expense but employer payroll taxes on it as a cash expense. Readers who treat equity pay as a genuine cost will focus on GAAP; those who focus on cash generation will lean on non-GAAP and free cash flow. Both views are legitimate, which is why this program shows them together.
Restructuring
Nine-month restructuring charges total $161.7 million, only $11.0 million of it in Q3. The XBRL history shows a $170.0 million net loss in Q2 2026, which may relate to this, though the release does not say so. The forward-looking statements also mention a plan toward an ‘agentic AI-first operating model’ and a workforce reduction.
Cash and funding
Operating cash flow was $215.4 million (28% of revenue versus 30%). Capital spending was $121.8 million versus $84.6 million, leaving free cash flow of $82.1 million, a 10% margin versus 13%. Cash and securities were $5,128.7 million. Convertible senior notes are carried at $4,441.9 million, versus roughly $3,265 million in total at the end of 2025. Convertible notes are bonds that can be exchanged for shares, a common funding tool for US growth companies.
What to watch
Whether free cash flow margin recovers toward last year’s 13% as investment matures.
質疑:第4四半期の見通しと次の焦点
Guidance, Leadership Change and What Comes Next
The company’s outlook ($ millions)
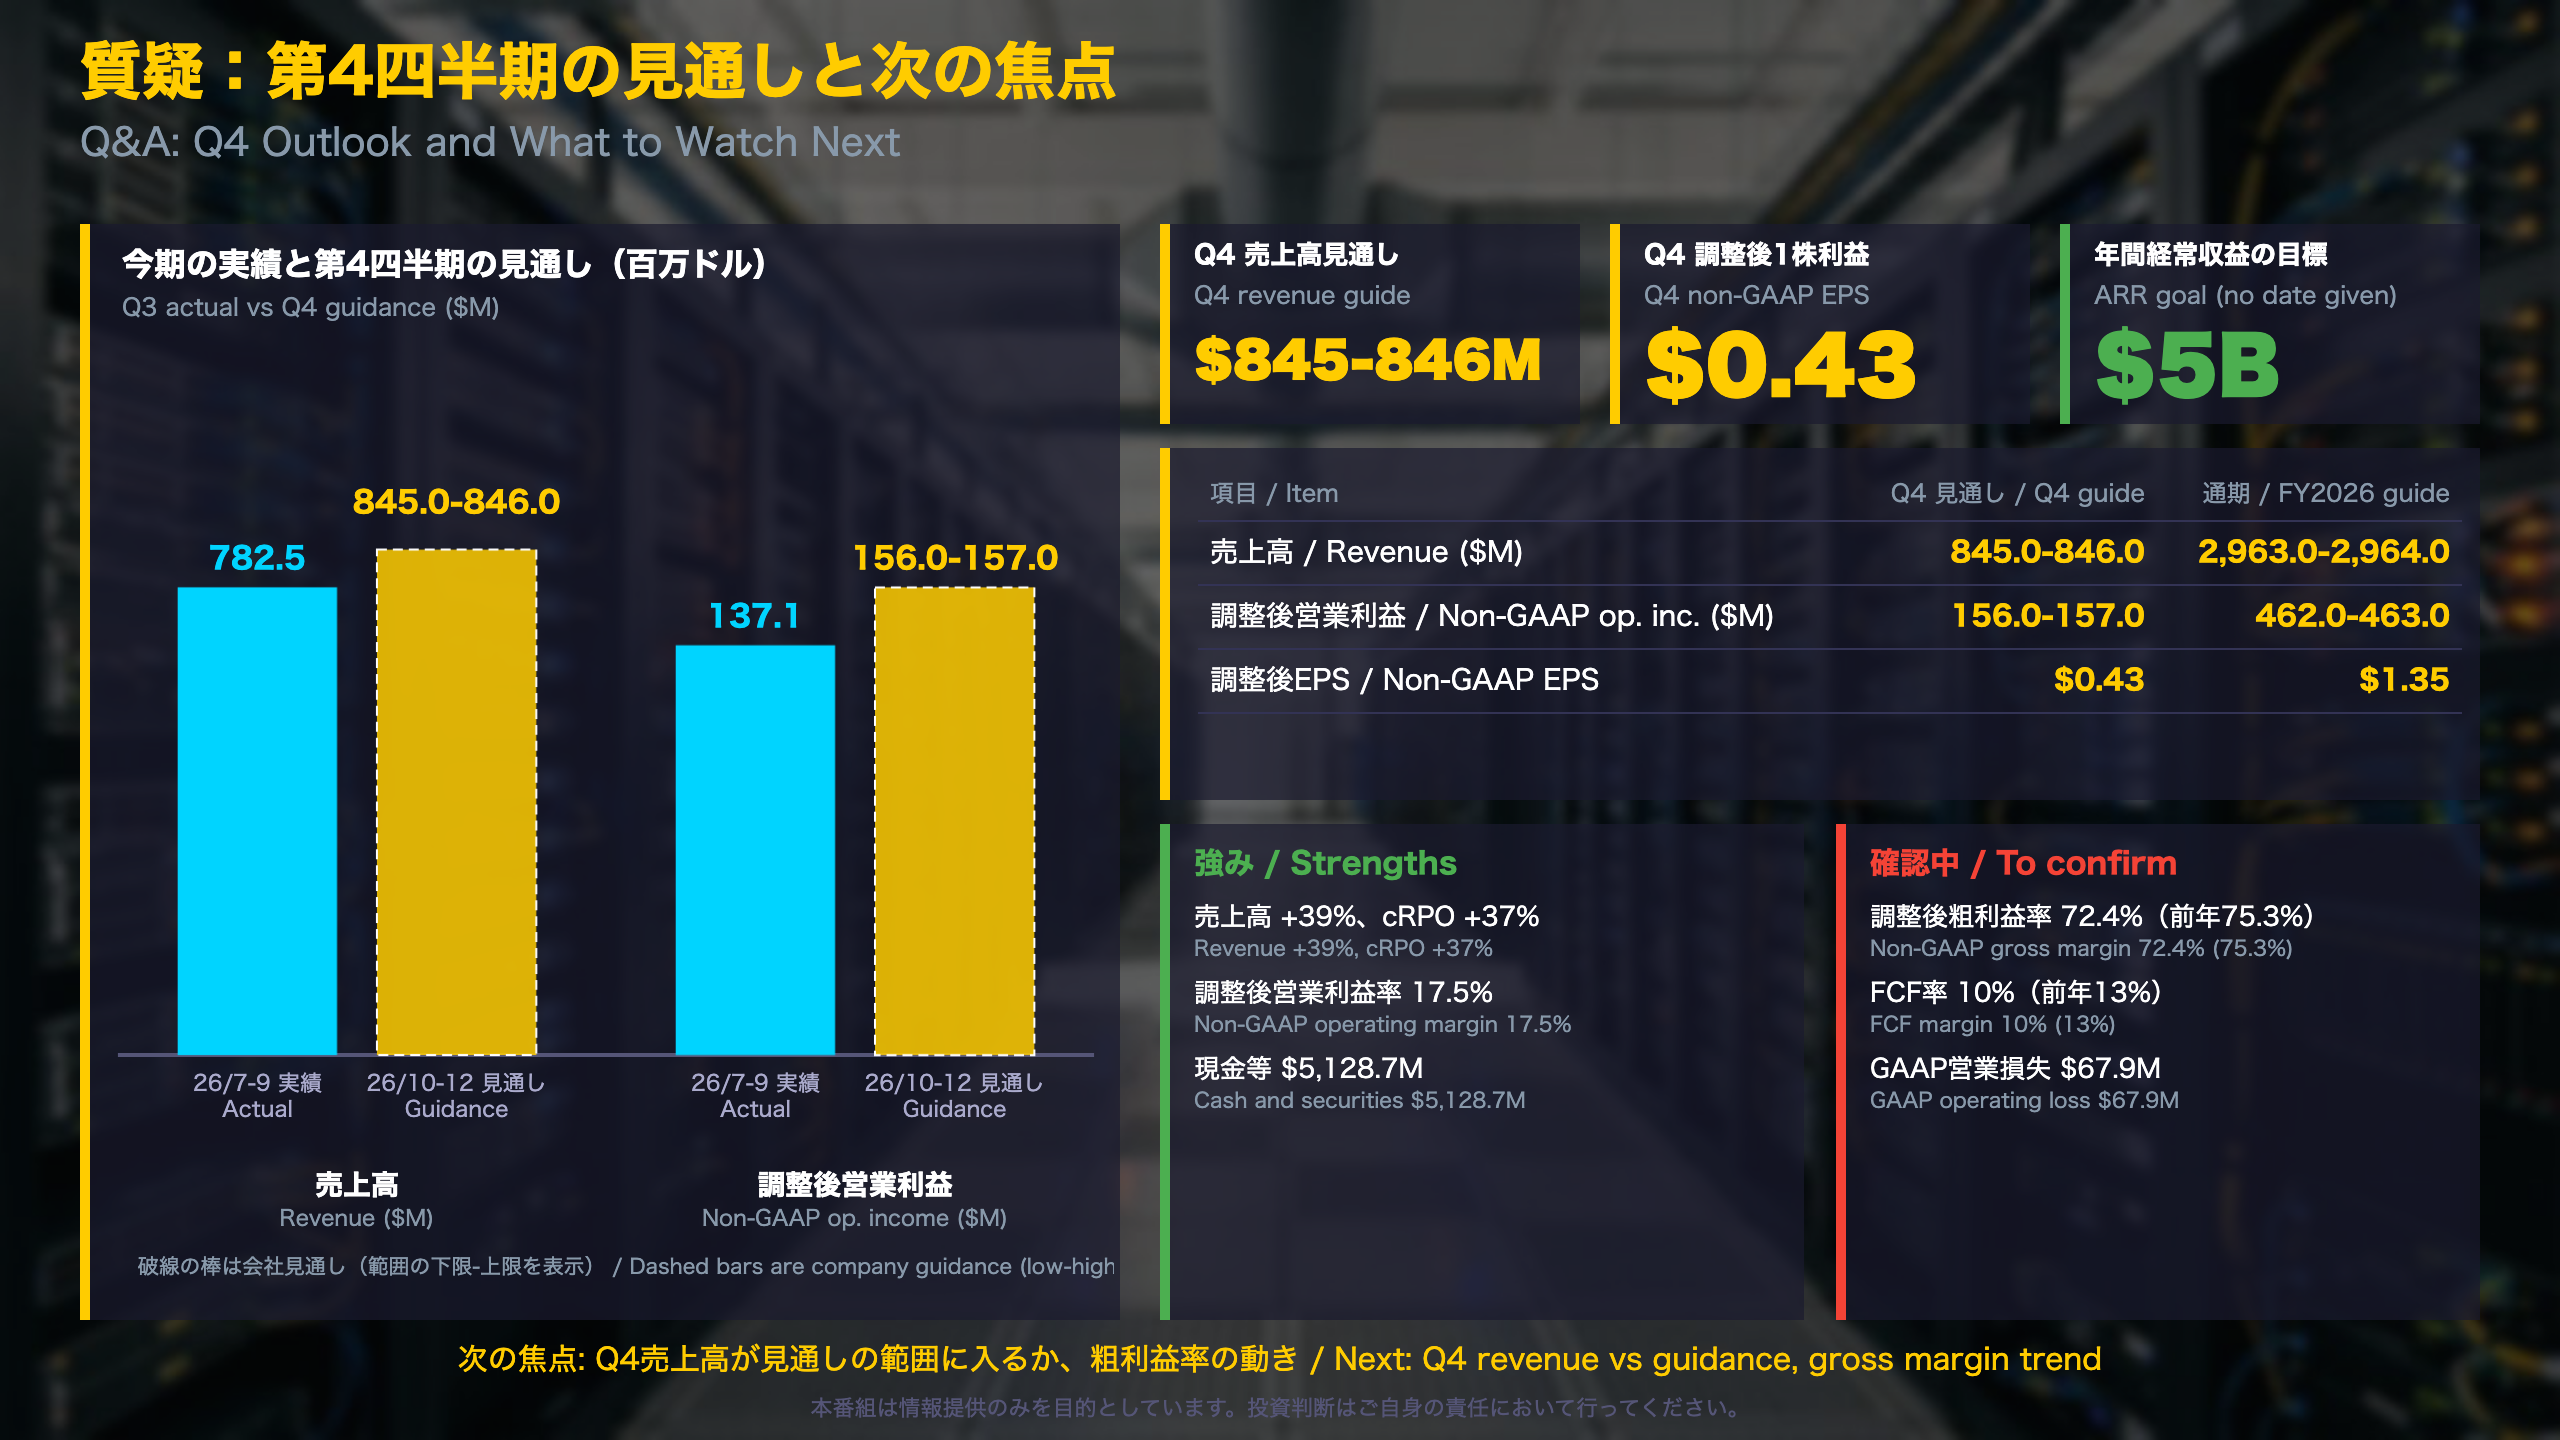
| Item | Q4 2026 | Full year 2026 |
|---|---|---|
| Revenue | 845.0-846.0 | 2,963.0-2,964.0 |
| Non-GAAP operating income | 156.0-157.0 | 462.0-463.0 |
| Non-GAAP EPS | $0.43 | $1.35 |
Adding the nine-month actuals (revenue $2,118.3 million, non-GAAP operating income $306.3 million, non-GAAP EPS $0.92) to the Q4 guidance reproduces the full-year range. At the midpoints, the implied non-GAAP operating margin is about 18.5% for Q4 and 15.6% for the year (our calculation), compared with 17.5% in Q3. This is company guidance only; we do not use analyst consensus.
Leadership change
On the same day Cloudflare named Christian Smith President of Revenue, leading global sales and revenue operations. He was Chief Revenue Officer at Splunk, where annual recurring revenue (ARR, the yearly value of subscription contracts) scaled to more than $4 billion before the Cisco acquisition. He succeeds Mark Anderson, who retires from his full-time role at the end of 2026 and stays as an advisor through December. The release cites a goal of reaching ‘$5 billion in annual recurring revenue and beyond’ without a date.
Two readings
- Constructive: guidance points to higher revenue and a higher adjusted margin than Q3, and a seasoned go-to-market leader joins before the next phase.
- Cautious: no gross margin guidance is given, and the release does not compare the outlook with the prior one.
What to watch
The release gives no date for the next earnings report. Key checks will be whether Q4 revenue lands within $845.0-846.0 million, and the direction of gross margin and free cash flow margin.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.