📺 Watch the Full Video Analysis
This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-11-18 06:38 JST)
📊 NVIDIA reported fiscal Q3 2027 results on Nov. 17, 2026.
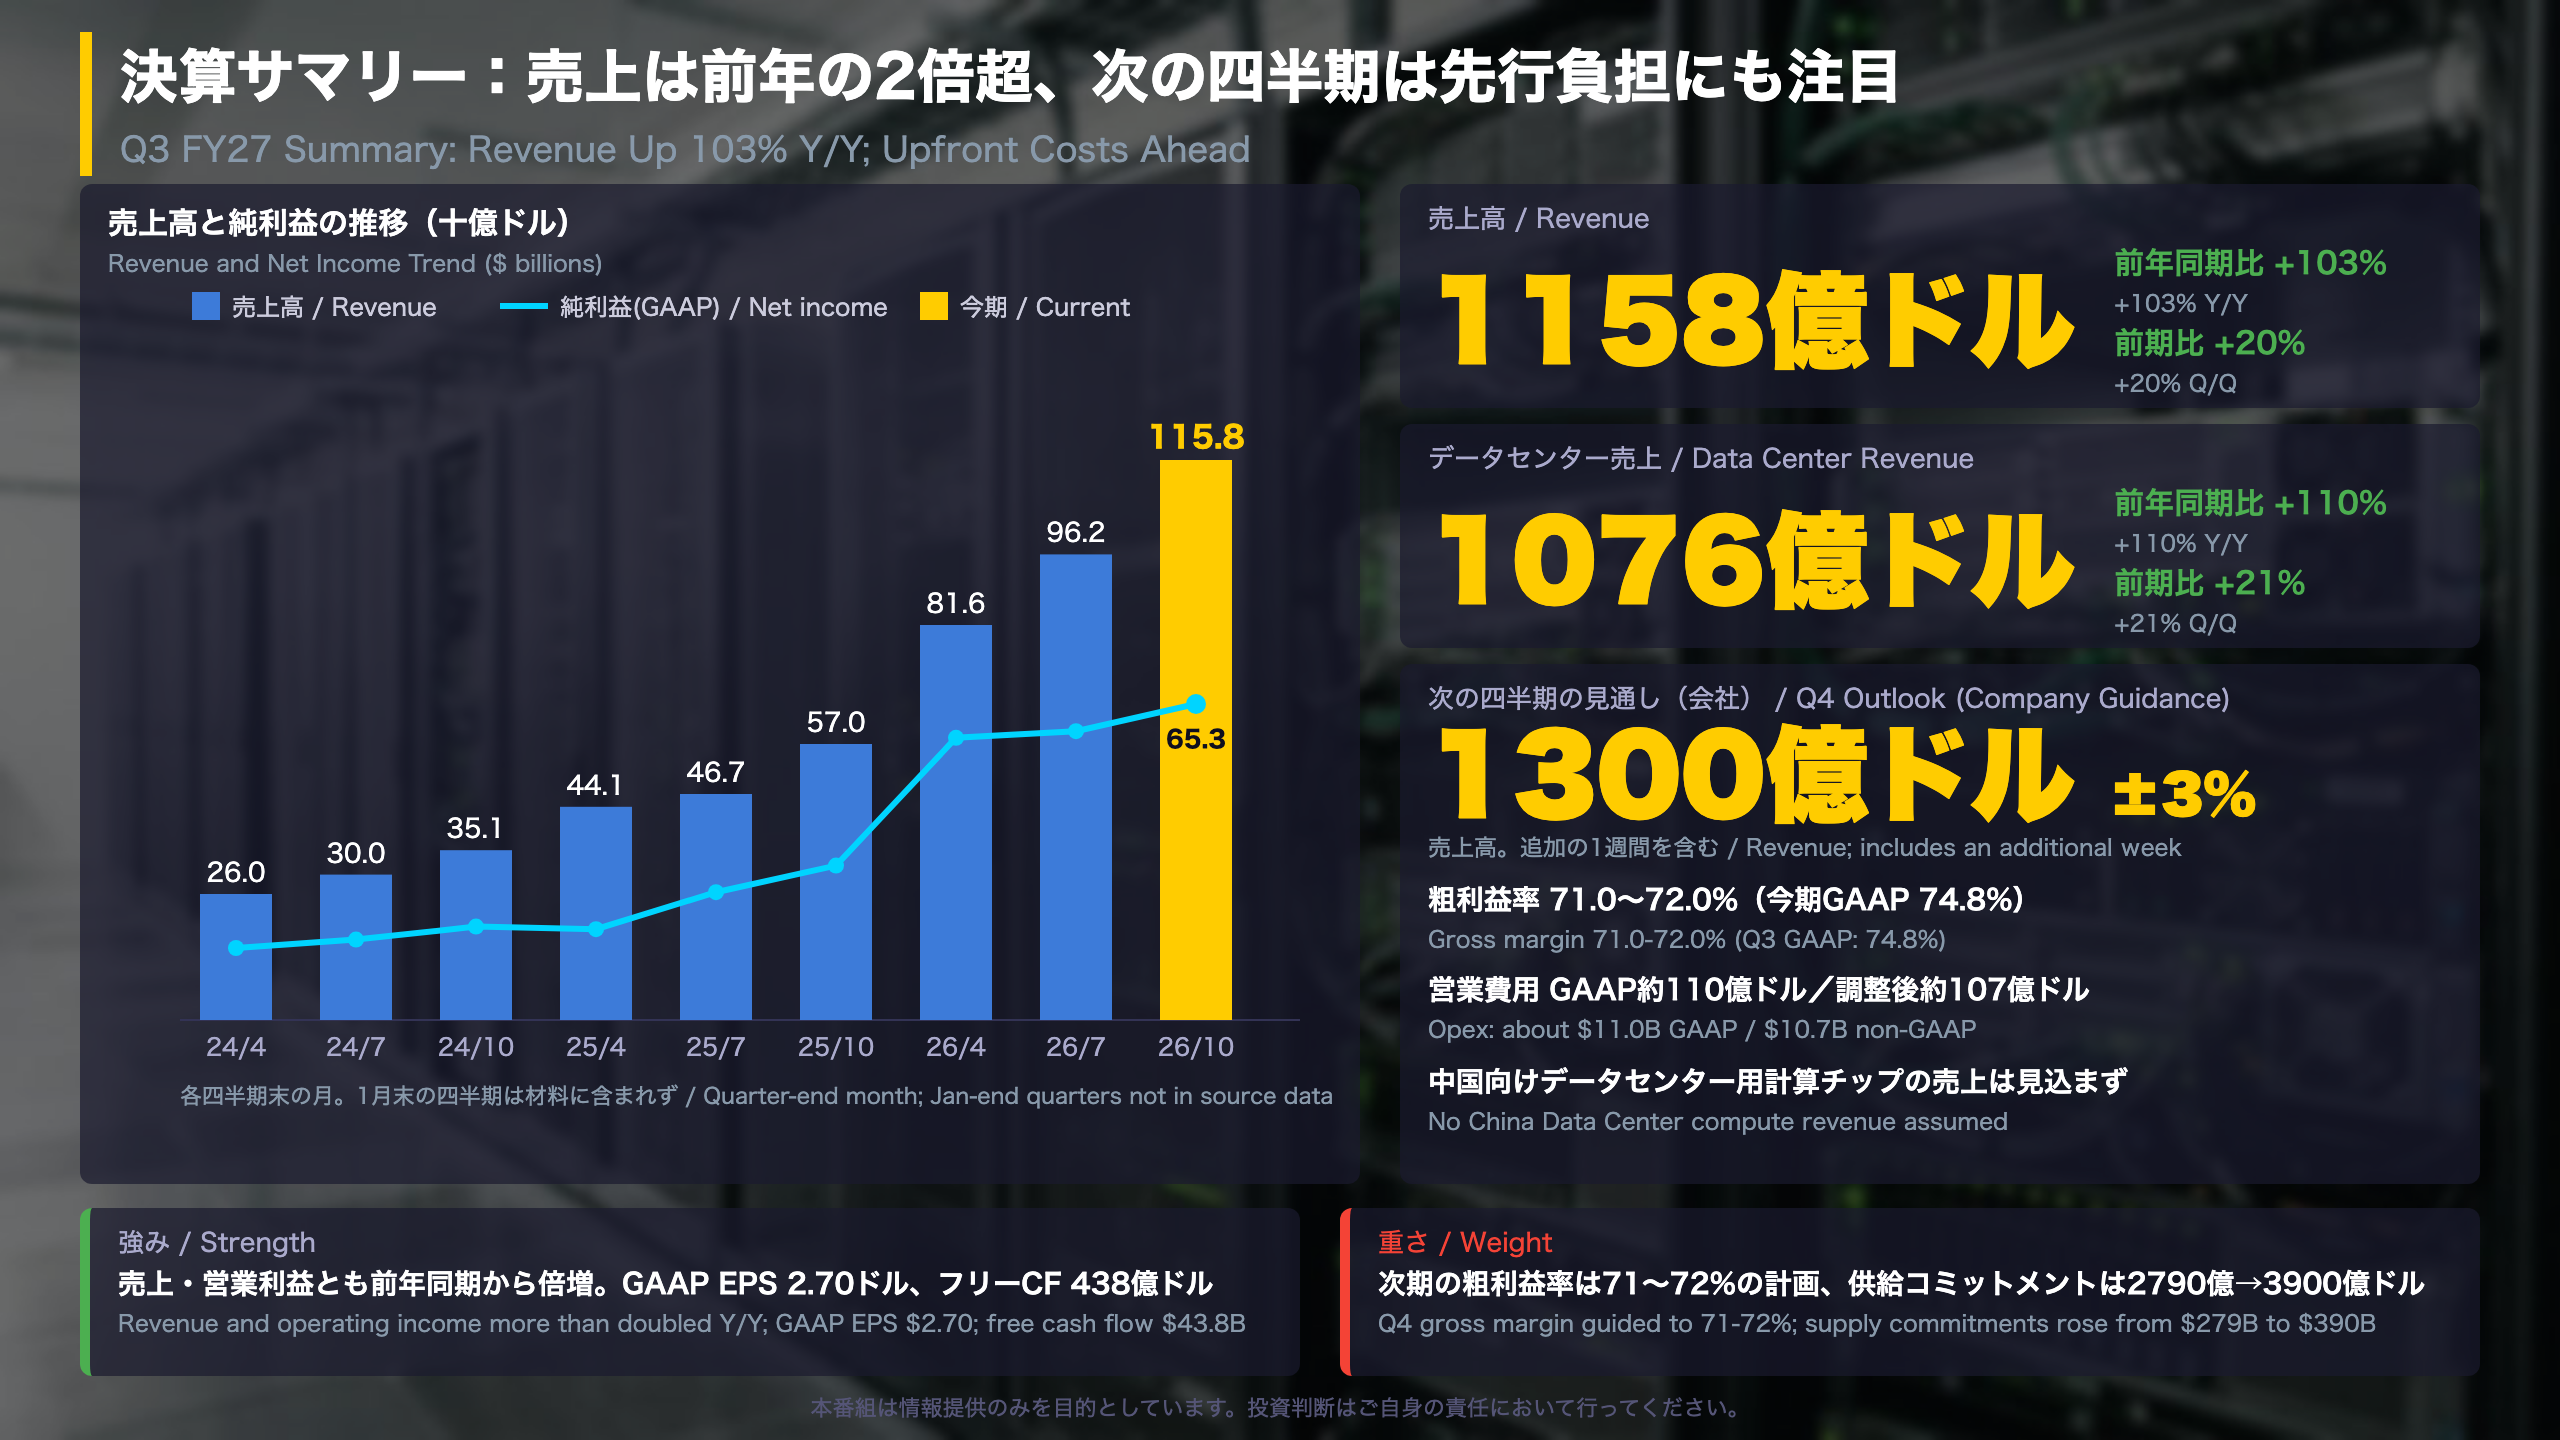
Revenue was $115.8B (+103% Y/Y) and Data Center revenue was $107.6B (+110%). GAAP EPS was $2.70 and non-GAAP EPS was $2.68.
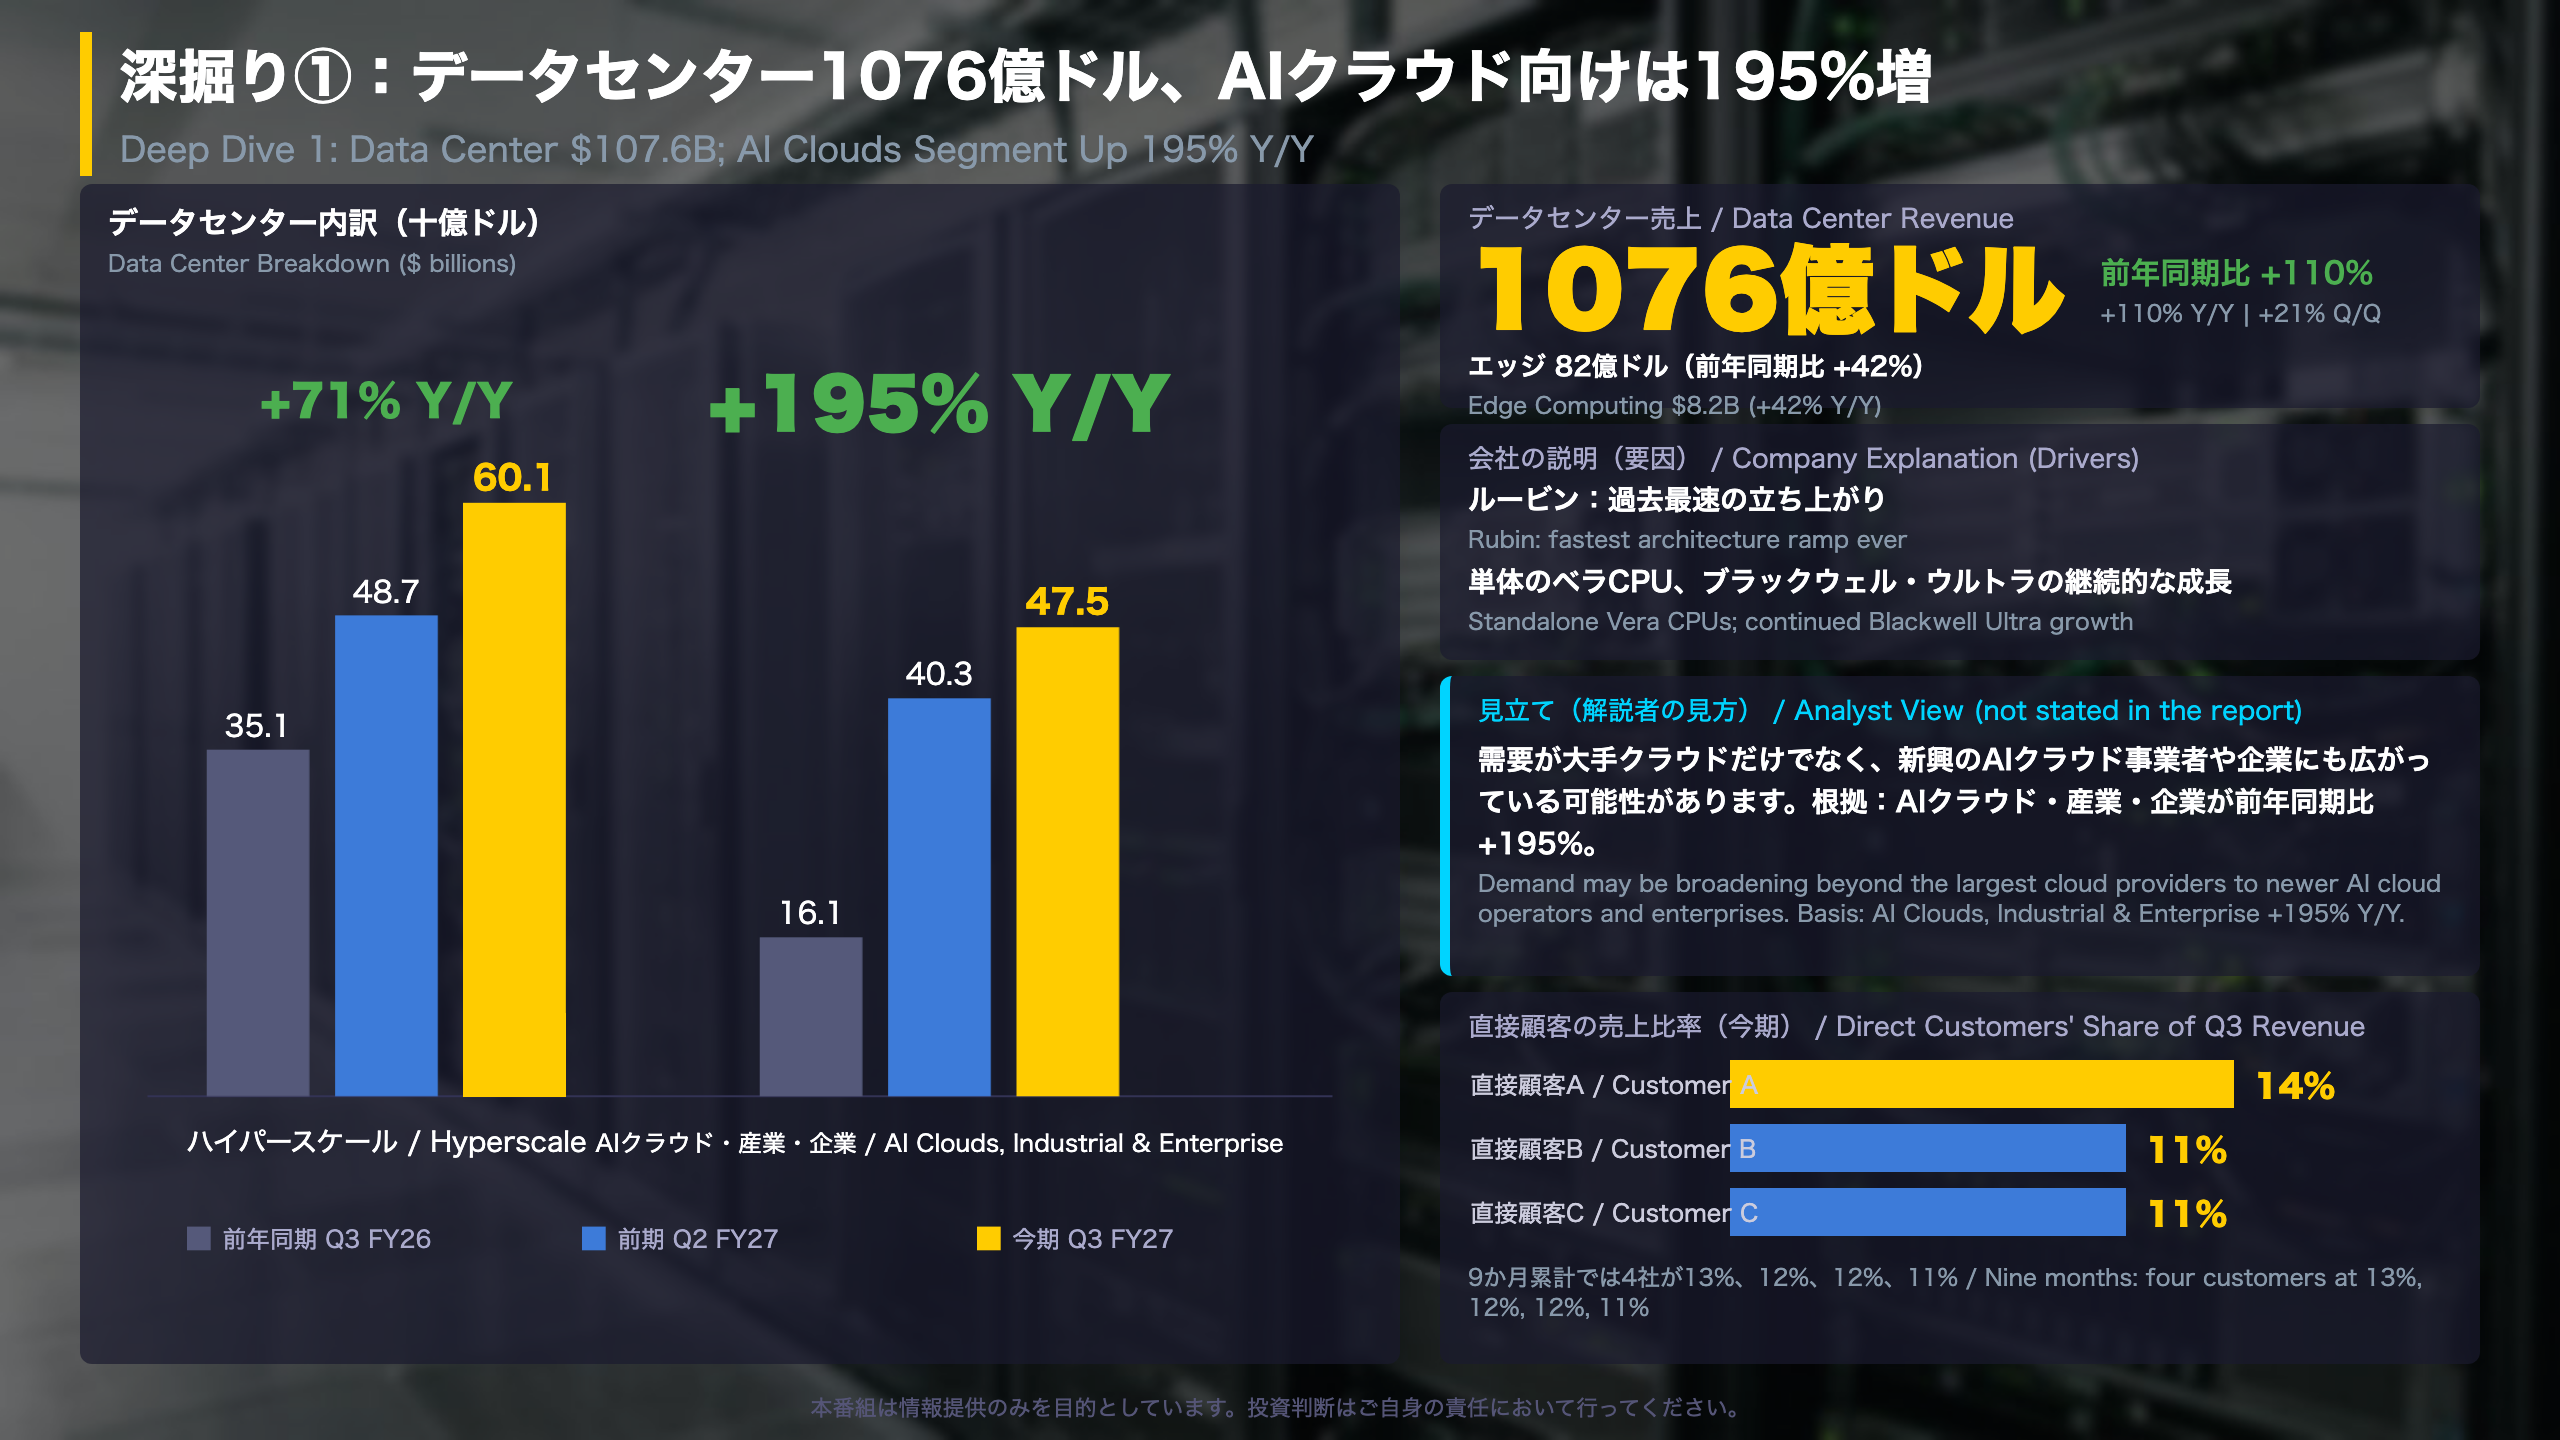
📈 AI Clouds, Industrial & Enterprise revenue rose 195% Y/Y.
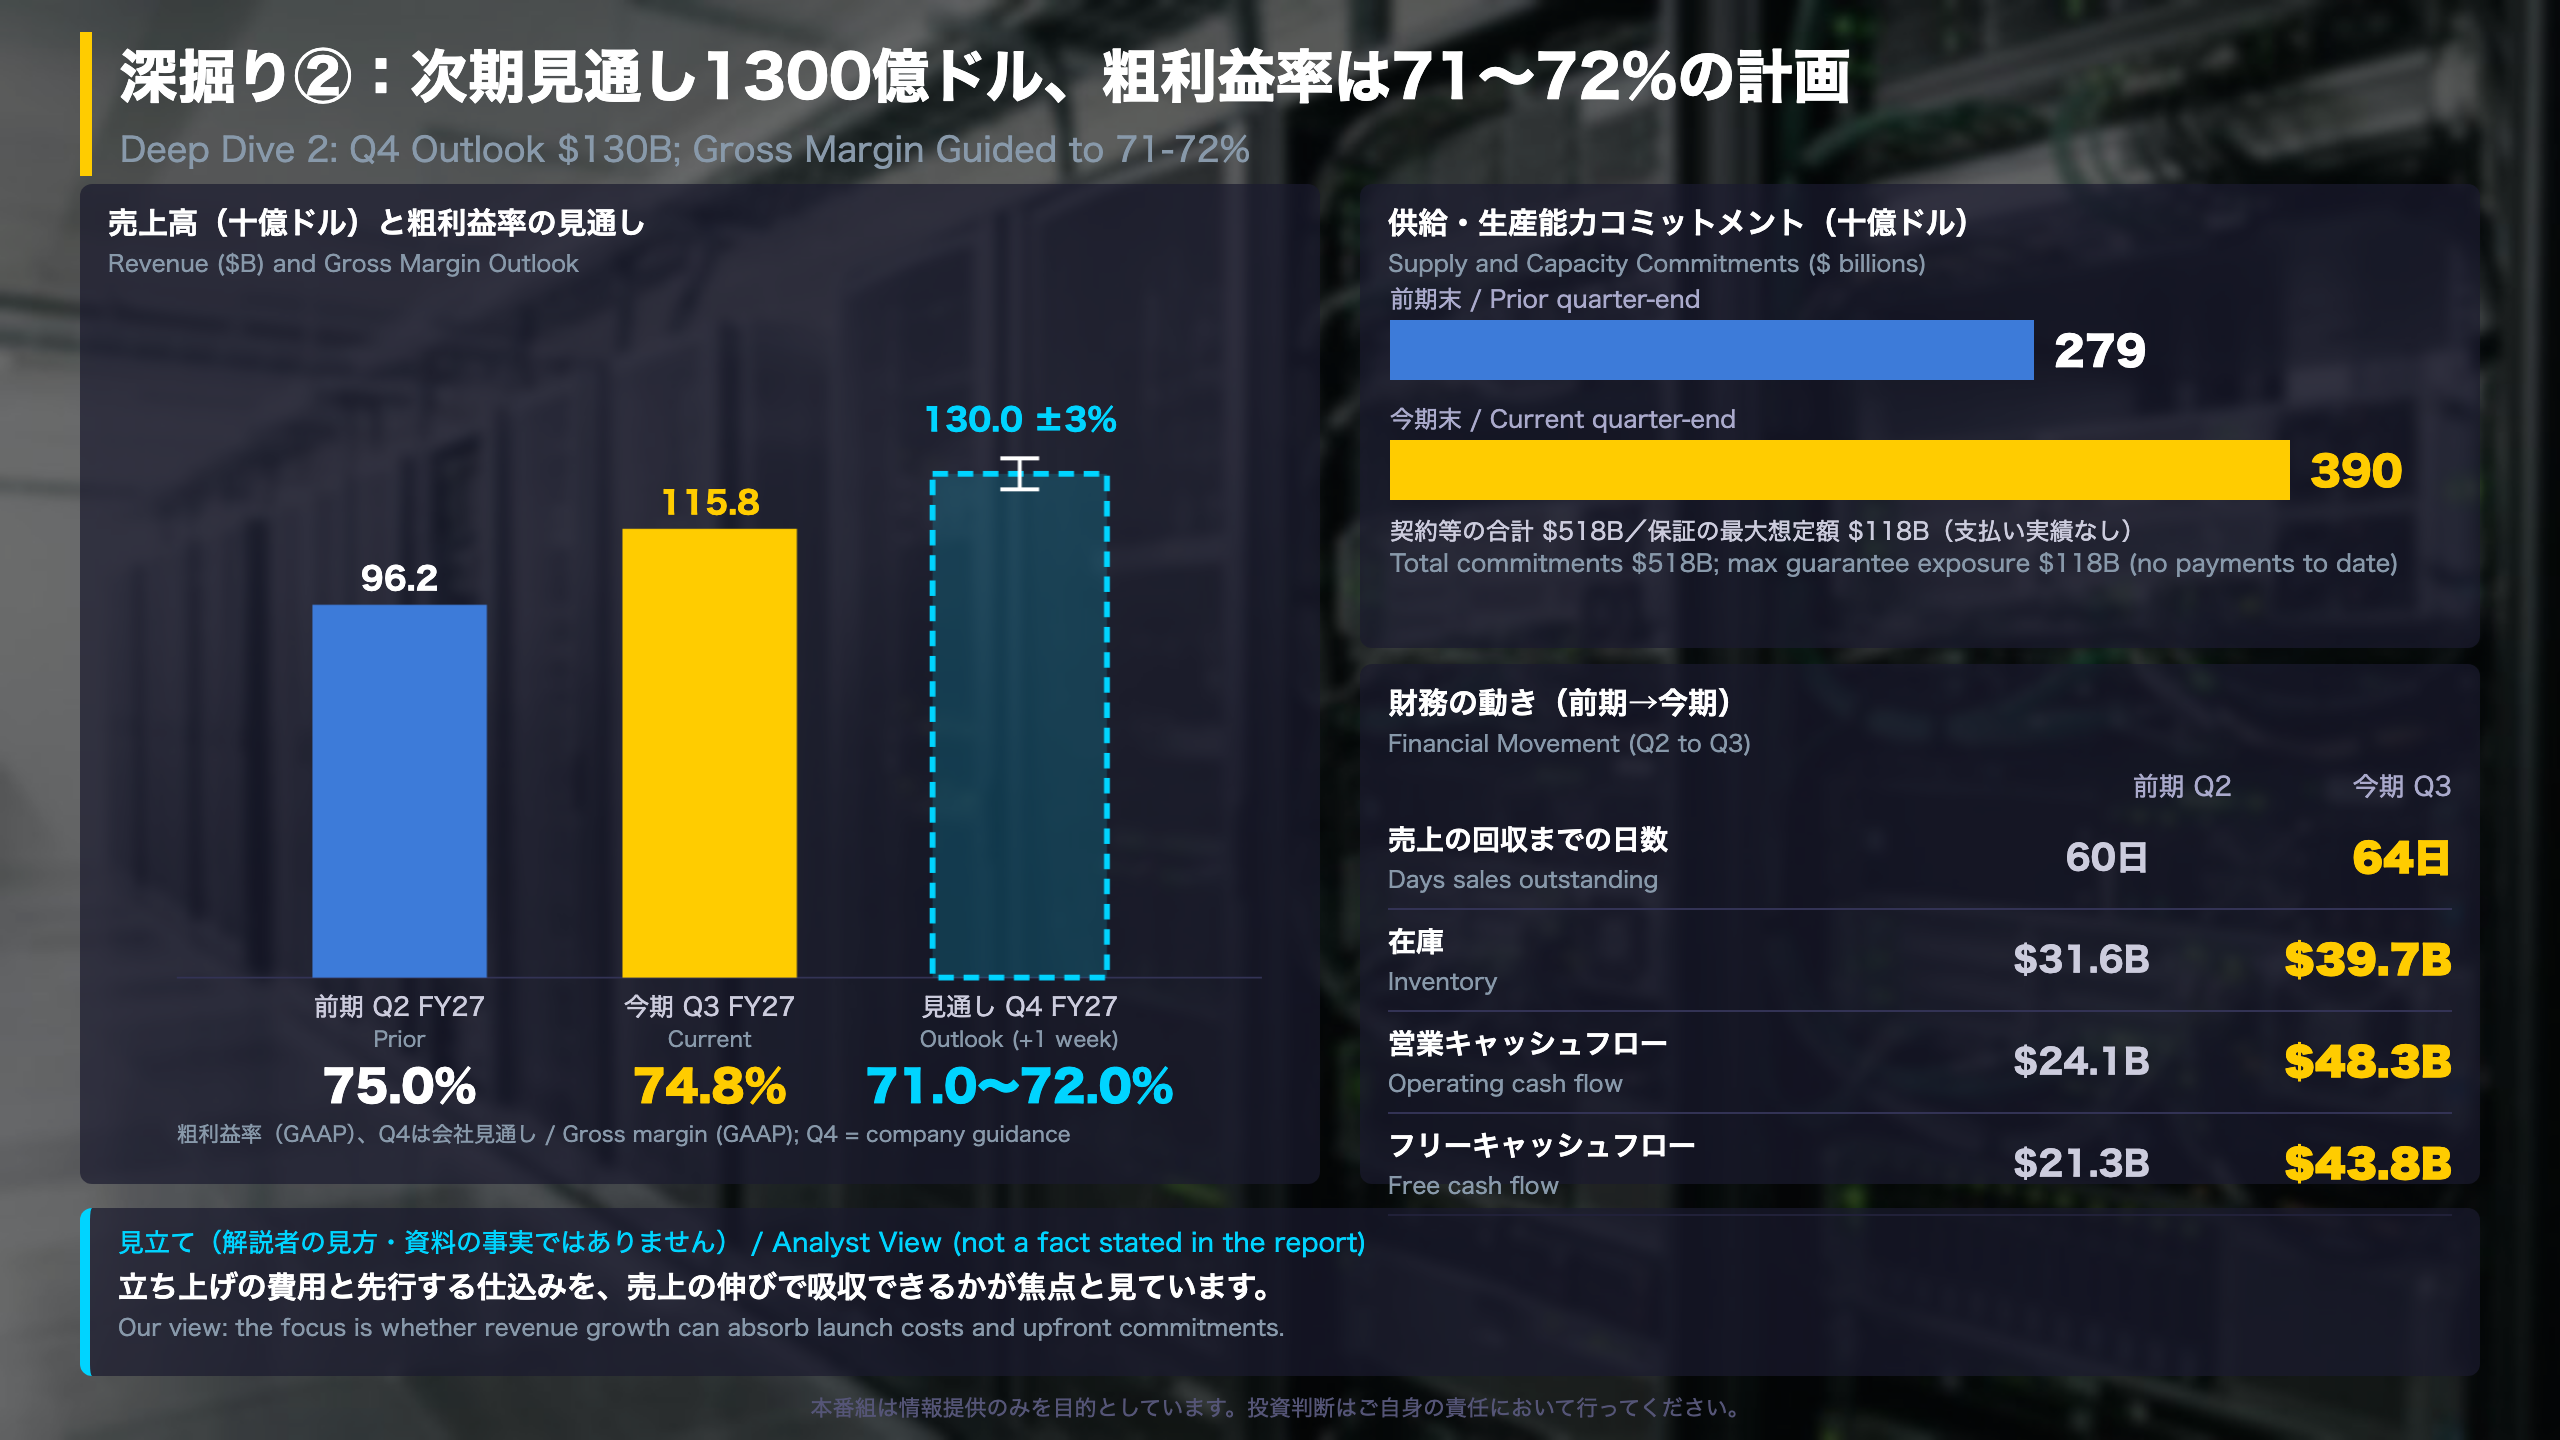
⚠️ The Q4 outlook is revenue of $130.0B ±3% with gross margin of 71.0-72.0%, below Q3’s GAAP 74.8%. Supply commitments rose to $390B.
💡 We walk through both the strengths and the upfront costs, using only the company’s own figures.
決算サマリー:売上は前年の2倍超、次の四半期は先行負担にも注目
What happened
NVIDIA released its fiscal Q3 2027 results (quarter ended Oct. 25, 2026) on Nov. 17 through an SEC Form 8-K. Its fiscal year ends in late January, so this quarter runs roughly from late July to late October.
- Revenue: $115.8B, +103% Y/Y and +20% Q/Q
- GAAP EPS: $2.70; non-GAAP EPS: $2.68
- GAAP gross margin: 74.8% (75.0% last quarter)
- Q4 outlook: revenue $130.0B ±3%, gross margin 71.0-72.0%, with no China Data Center compute revenue assumed
Reading the numbers
GAAP follows US accounting rules. Non-GAAP excludes items such as acquisition-related costs and gains on equity securities. From fiscal 2027, NVIDIA’s non-GAAP measures no longer exclude stock-based compensation, so they sit closer to GAAP than before. Nine-month revenue is $293.7B versus $147.8B a year earlier, and nine-month GAAP net income includes sizable equity-securities gains.
A balanced view
The growth and $43.8B of free cash flow are clear strengths. The forward-looking-statement section also lists a CEO search (CFO Colette Kress is interim CEO) and an ongoing investigation by an independent board committee, with no further detail in the text provided.
What to watch
The Form 10-Q, which the company says it will file within weeks, and the Q4 results. The source does not state the Q4 reporting date.
深掘り①:データセンター1076億ドル、AIクラウド向けは195%増
Segment detail
| Segment | Q3 FY27 | Q2 FY27 | Q3 FY26 |
|---|---|---|---|
| Data Center | $107.6B | $89.0B | $51.2B |
| Hyperscale | $60.1B | $48.7B | $35.1B |
| AI Clouds, Industrial & Enterprise | $47.5B | $40.3B | $16.1B |
| Edge Computing | $8.2B | $7.2B | $5.8B |
Hyperscale refers to the largest public-cloud operators. The second group covers newer AI cloud providers (often called neoclouds), industrial users and enterprises. CFO Colette Kress credits Rubin (“our fastest architecture ramp ever”), standalone Vera CPUs and continued Blackwell Ultra growth.
Geography and concentration
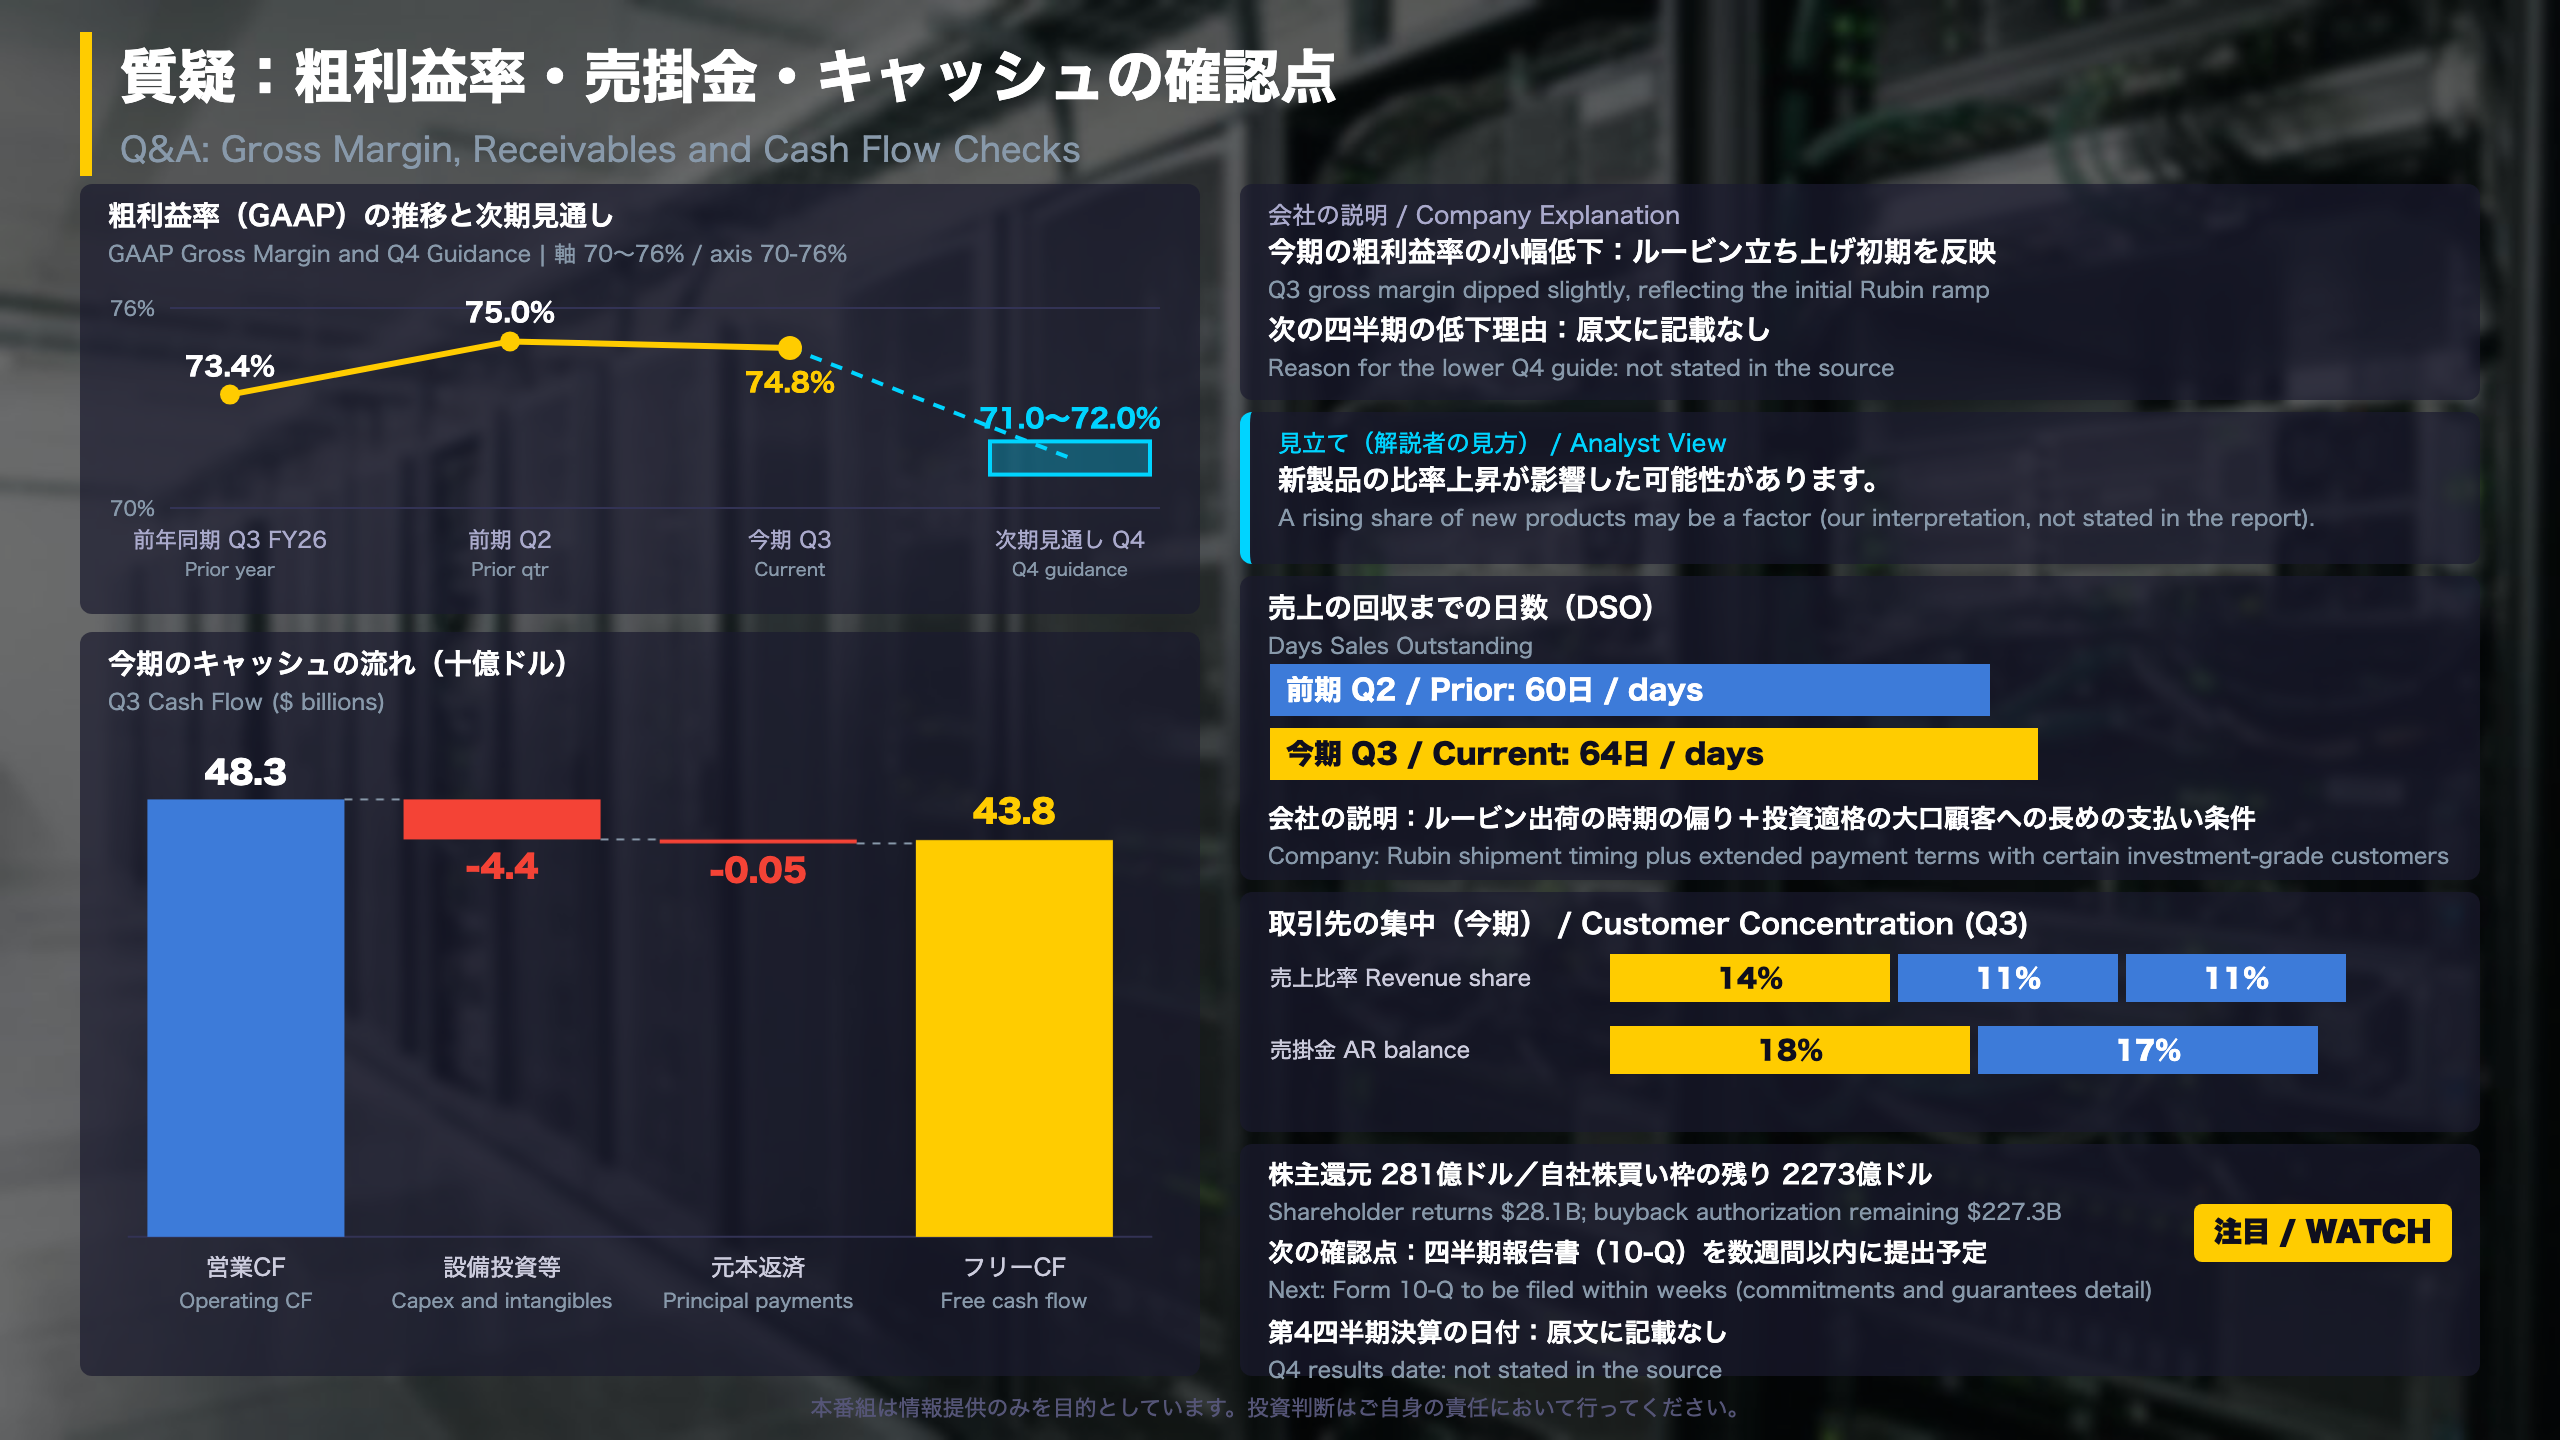
By customer headquarters: US $72.9B, Taiwan $30.3B, and China including Hong Kong about $11.1B (versus $3.0B a year ago). Data Center Hopper shipments to China were $2.4B, and the Q4 outlook assumes no China Data Center compute revenue. Three direct customers accounted for 14%, 11% and 11% of revenue. Direct customers are the parties that buy from NVIDIA, such as system builders and cloud providers, not necessarily the end users.
Two readings
Constructive: 195% Y/Y growth in AI Clouds, Industrial & Enterprise suggests demand beyond the biggest clouds. Cautious: revenue depends on a small number of buyers, so one customer’s plans can matter. The company itself says revenue is concentrated among a limited number of customers.
What to watch
The 10-Q’s customer-concentration disclosure and the Q4 outlook of $130.0B ±3%.
深掘り②:次期見通し1300億ドル、粗利益率は71〜72%の計画
Guidance detail
For Q4 FY27 (a quarter with an extra week) NVIDIA guides to:
– Revenue: $130.0B ±3%, with no China Data Center compute revenue assumed
– Gross margin: 71.0-72.0% (GAAP and non-GAAP)
– Operating expenses: about $11.0B GAAP and $10.7B non-GAAP
– Full-year tax rate: 16.0-18.0%
Q3 GAAP gross margin was 74.8%, down 0.2 points from 75.0%. The CFO says the dip reflects “the initial Rubin ramp.” The source gives no reason for the lower Q4 guide.
Forward commitments
Total commitments are $518B: supply and capacity $390B (up from $279B, mainly multi-year memory procurement), cloud service agreements $28B, data center leases not yet commenced $74B, equity investments $20B and capital expenditures $6B. Separately, neocloud agreements total up to $32B, and maximum guarantee exposure is $118B, of which SB Energy credit support is up to $105B. Neoclouds are newer AI cloud operators; NVIDIA says its commitments to them take effect only if they secure financing and the capacity is deployed and accepted. NVIDIA reports no payments under the guarantees to date.
Two readings
Constructive: $43.8B of free cash flow and $48.3B of operating cash flow show capacity to fund these obligations. Cautious: the commitments assume demand keeps growing, and the source does not allow us to judge the effect if it does not.
What to watch
The 10-Q’s detail on commitments and guarantees, and whether Q4 gross margin lands within 71.0-72.0%.
質疑:粗利益率・売掛金・キャッシュの確認点
Receivables and inventory
Accounts receivable were $81.0B at quarter-end ($38.5B at the January fiscal year-end). Days sales outstanding (DSO), the average days needed to collect cash after a sale, rose to 64 from 60 last quarter. The CFO commentary cites shipment timing from the Rubin launch and “extended payment terms on large, multi-quarter agreements with certain investment-grade customers.” Two direct customers represent 18% and 17% of the receivables balance.
Inventory was $39.7B versus $31.6B last quarter, supporting the Rubin ramp. Raw materials rose to $15.8B (from $3.8B in January) and work in process to $17.8B, while finished goods fell to $6.2B (from $8.8B).
Cash and capital returns
Operating cash flow was $48.3B ($24.1B last quarter, $23.8B a year ago); the sequential gain was also affected by the timing of federal cash tax payments. Free cash flow was $43.8B. NVIDIA returned a record $28.1B to shareholders and has $227.3B of buyback authorization left, which it plans to use through fiscal 2028. The next dividend is $0.25 per share (record date Dec. 2, payable Dec. 23).
Two readings
Constructive: DSO rose by four days and cash generation is strong. Cautious: receivables and inventory both increased and are concentrated in a few customers.
What to watch
The Form 10-Q due within weeks. The source gives no date for the Q4 results.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.