📺 Watch the Full Video Analysis
This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-11-16 20:46 JST)
📄 Primary Source
Banco Central do Brasil
https://www.bcb.gov.br/content/focus/focusmarketreadout/R20261113.pdf
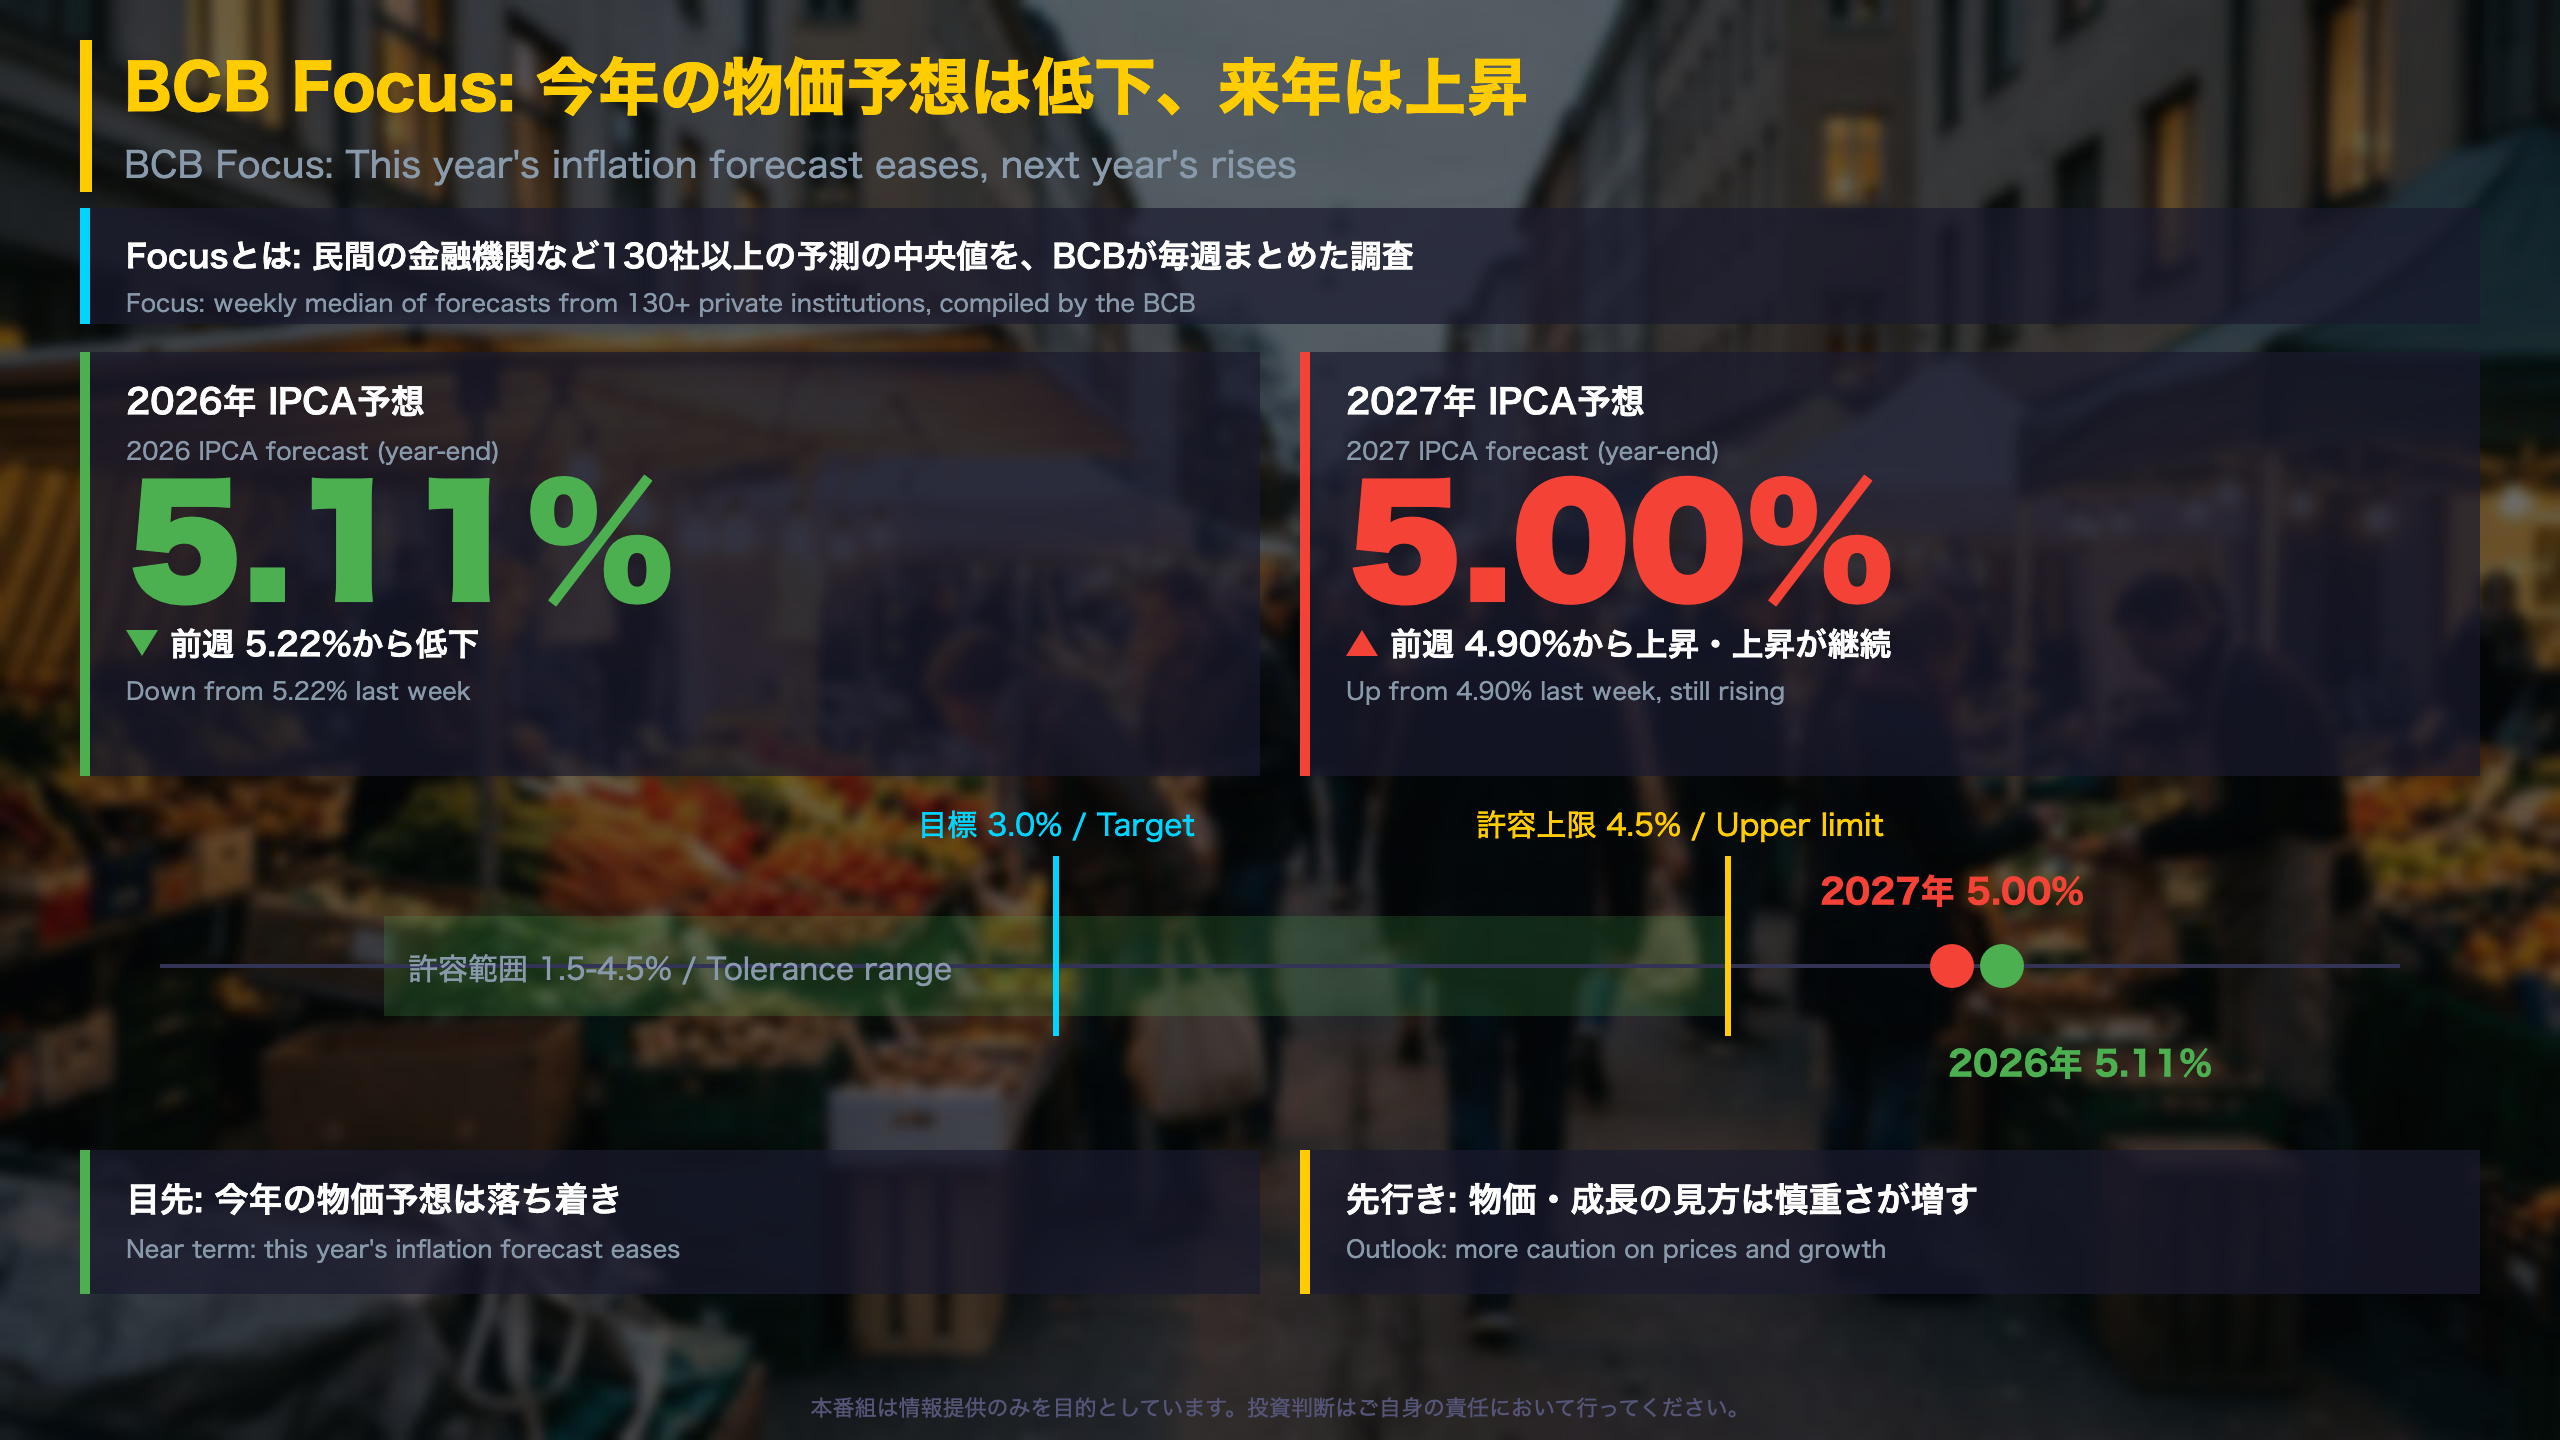
📊 The Central Bank of Brazil’s Focus survey (data as of Nov 13) shows the 2027 IPCA forecast at 5.00%, up for a fifth straight week.
📉 The 2026 IPCA forecast eased to 5.11%, and 2028-2029 growth forecasts were unchanged from last week.
💡 The end-2027 Selic forecast rose to 12.75% and the R$/US$ forecast to 5.45.
⚠️ The report states no cause, so any link between them is our interpretation. We also compare the Selic path with Japan’s 1.04% policy rate (Sep 2026) and review currency and fiscal risks.
サマリー: 今年の物価予想は低下、来年は上昇
What the Focus Survey Is
The Focus Market Readout is a weekly summary published by the Central Bank of Brazil (BCB) each Monday. It reports the median forecasts of private-sector institutions for inflation (IPCA), GDP, the exchange rate and the policy rate (Selic), and the BCB itself looks at it when assessing the policy outlook. The nearest US analogue is the Survey of Professional Forecasters, but Focus is far more frequent: weekly rather than quarterly.
Key Moves (data as of Nov 13, 2026)
| Item | 4 wks ago | 1 wk ago | Latest |
|---|---|---|---|
| 2026 IPCA (%) | 5.22 | 5.22 | 5.11 |
| 2027 IPCA (%) | 4.32 | 4.90 | 5.00 |
| 2026 IGP-M (%) | 5.26 | 6.10 | 6.22 |
- Resilience: this year’s inflation forecast eased; 2028 and 2029 growth forecasts (1.80% and 2.00%) were unchanged; the 2026 foreign direct investment forecast stands at US$85 billion, up from US$80 billion four weeks ago.
- Risks: next year’s inflation forecast has risen five weeks in a row and sits above the 4.5% upper limit of the target range (target: 3.0%).
Why It Matters Internationally
Brazil’s target is a 3.0% center with a 1.5-point tolerance band on each side, versus the Fed’s 2% goal. Because these are medians of private forecasts rather than official guidance, they describe how respondents see conditions, not what the BCB will do. This is one week’s reading and should not be treated as a confirmed trend.
物価予想とSelicパス: 先行きの見方が上方へ
Inflation Expectations and the Selic Path
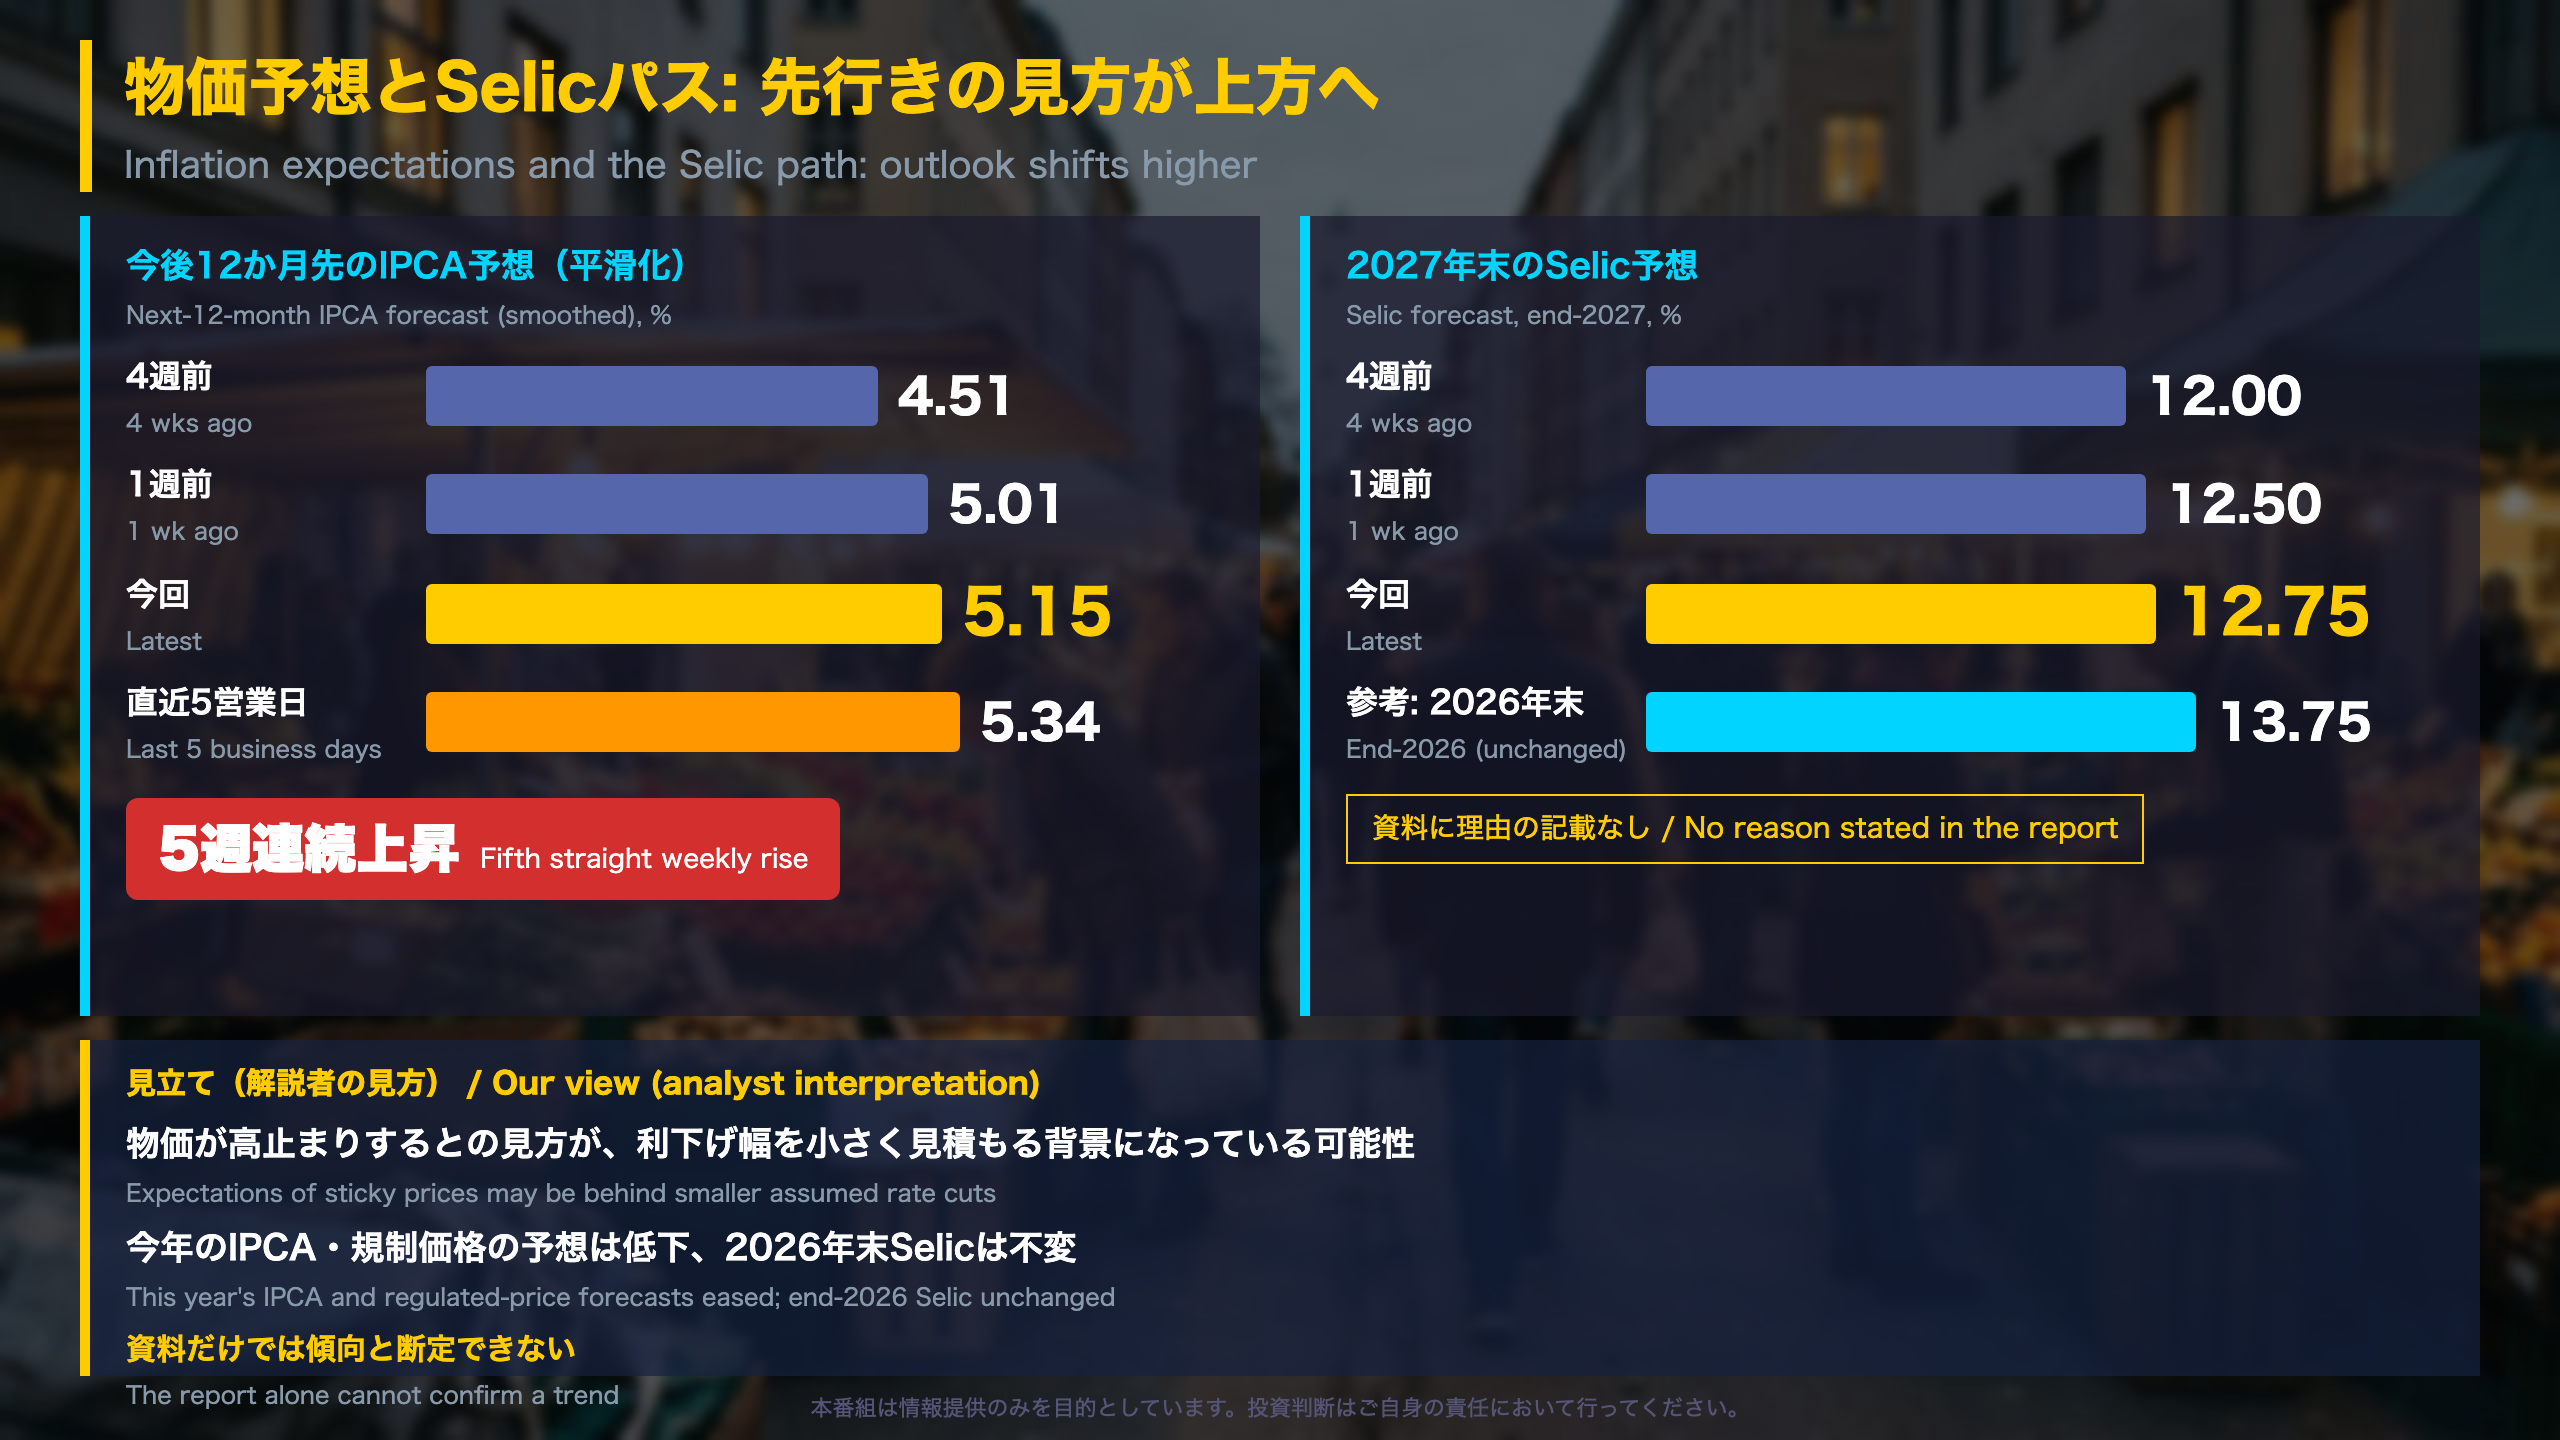
Next-12-month inflation (smoothed) moved from 4.51% four weeks ago to 5.01% one week ago and now 5.15%, a fifth consecutive weekly rise. The median among the last five business days of responses is higher still, at 5.34%.
Monthly IPCA forecasts (%)
| Month | 1 wk ago | Latest |
|---|---|---|
| Nov 2026 | 0.35 | 0.35 |
| Dec 2026 | 0.60 | 0.61 |
| Jan 2027 | 0.57 | 0.60 |
Selic path (year-end, %)
| Year | 4 wks ago | Latest |
|---|---|---|
| 2026 | 13.25 | 13.75 |
| 2027 | 12.00 | 12.75 |
| 2028 | 10.50 | 11.00 |
| 2029 | 10.00 | 10.50 |
Two Readings
- Cautious: inflation and rate forecasts moved in the same direction, which may mean respondents see less room for rate cuts. The report states no reason, so this is our interpretation.
- Balanced: this year’s IPCA forecast (5.11%) and regulated-price forecast (4.46%) both fell, and the end-2026 Selic median is unchanged from last week at 13.75%.
What to Watch
Whether the end-2027 Selic median moves from 12.75% in next Monday’s release. For context, the Selic target is the policy rate set by the BCB’s monetary policy committee (Copom), comparable to the Fed’s federal funds target range.
BRL/JPY視点: 金利差・為替・リスク要因
Carry, Currency and Risk: A Japanese Investor’s Lens
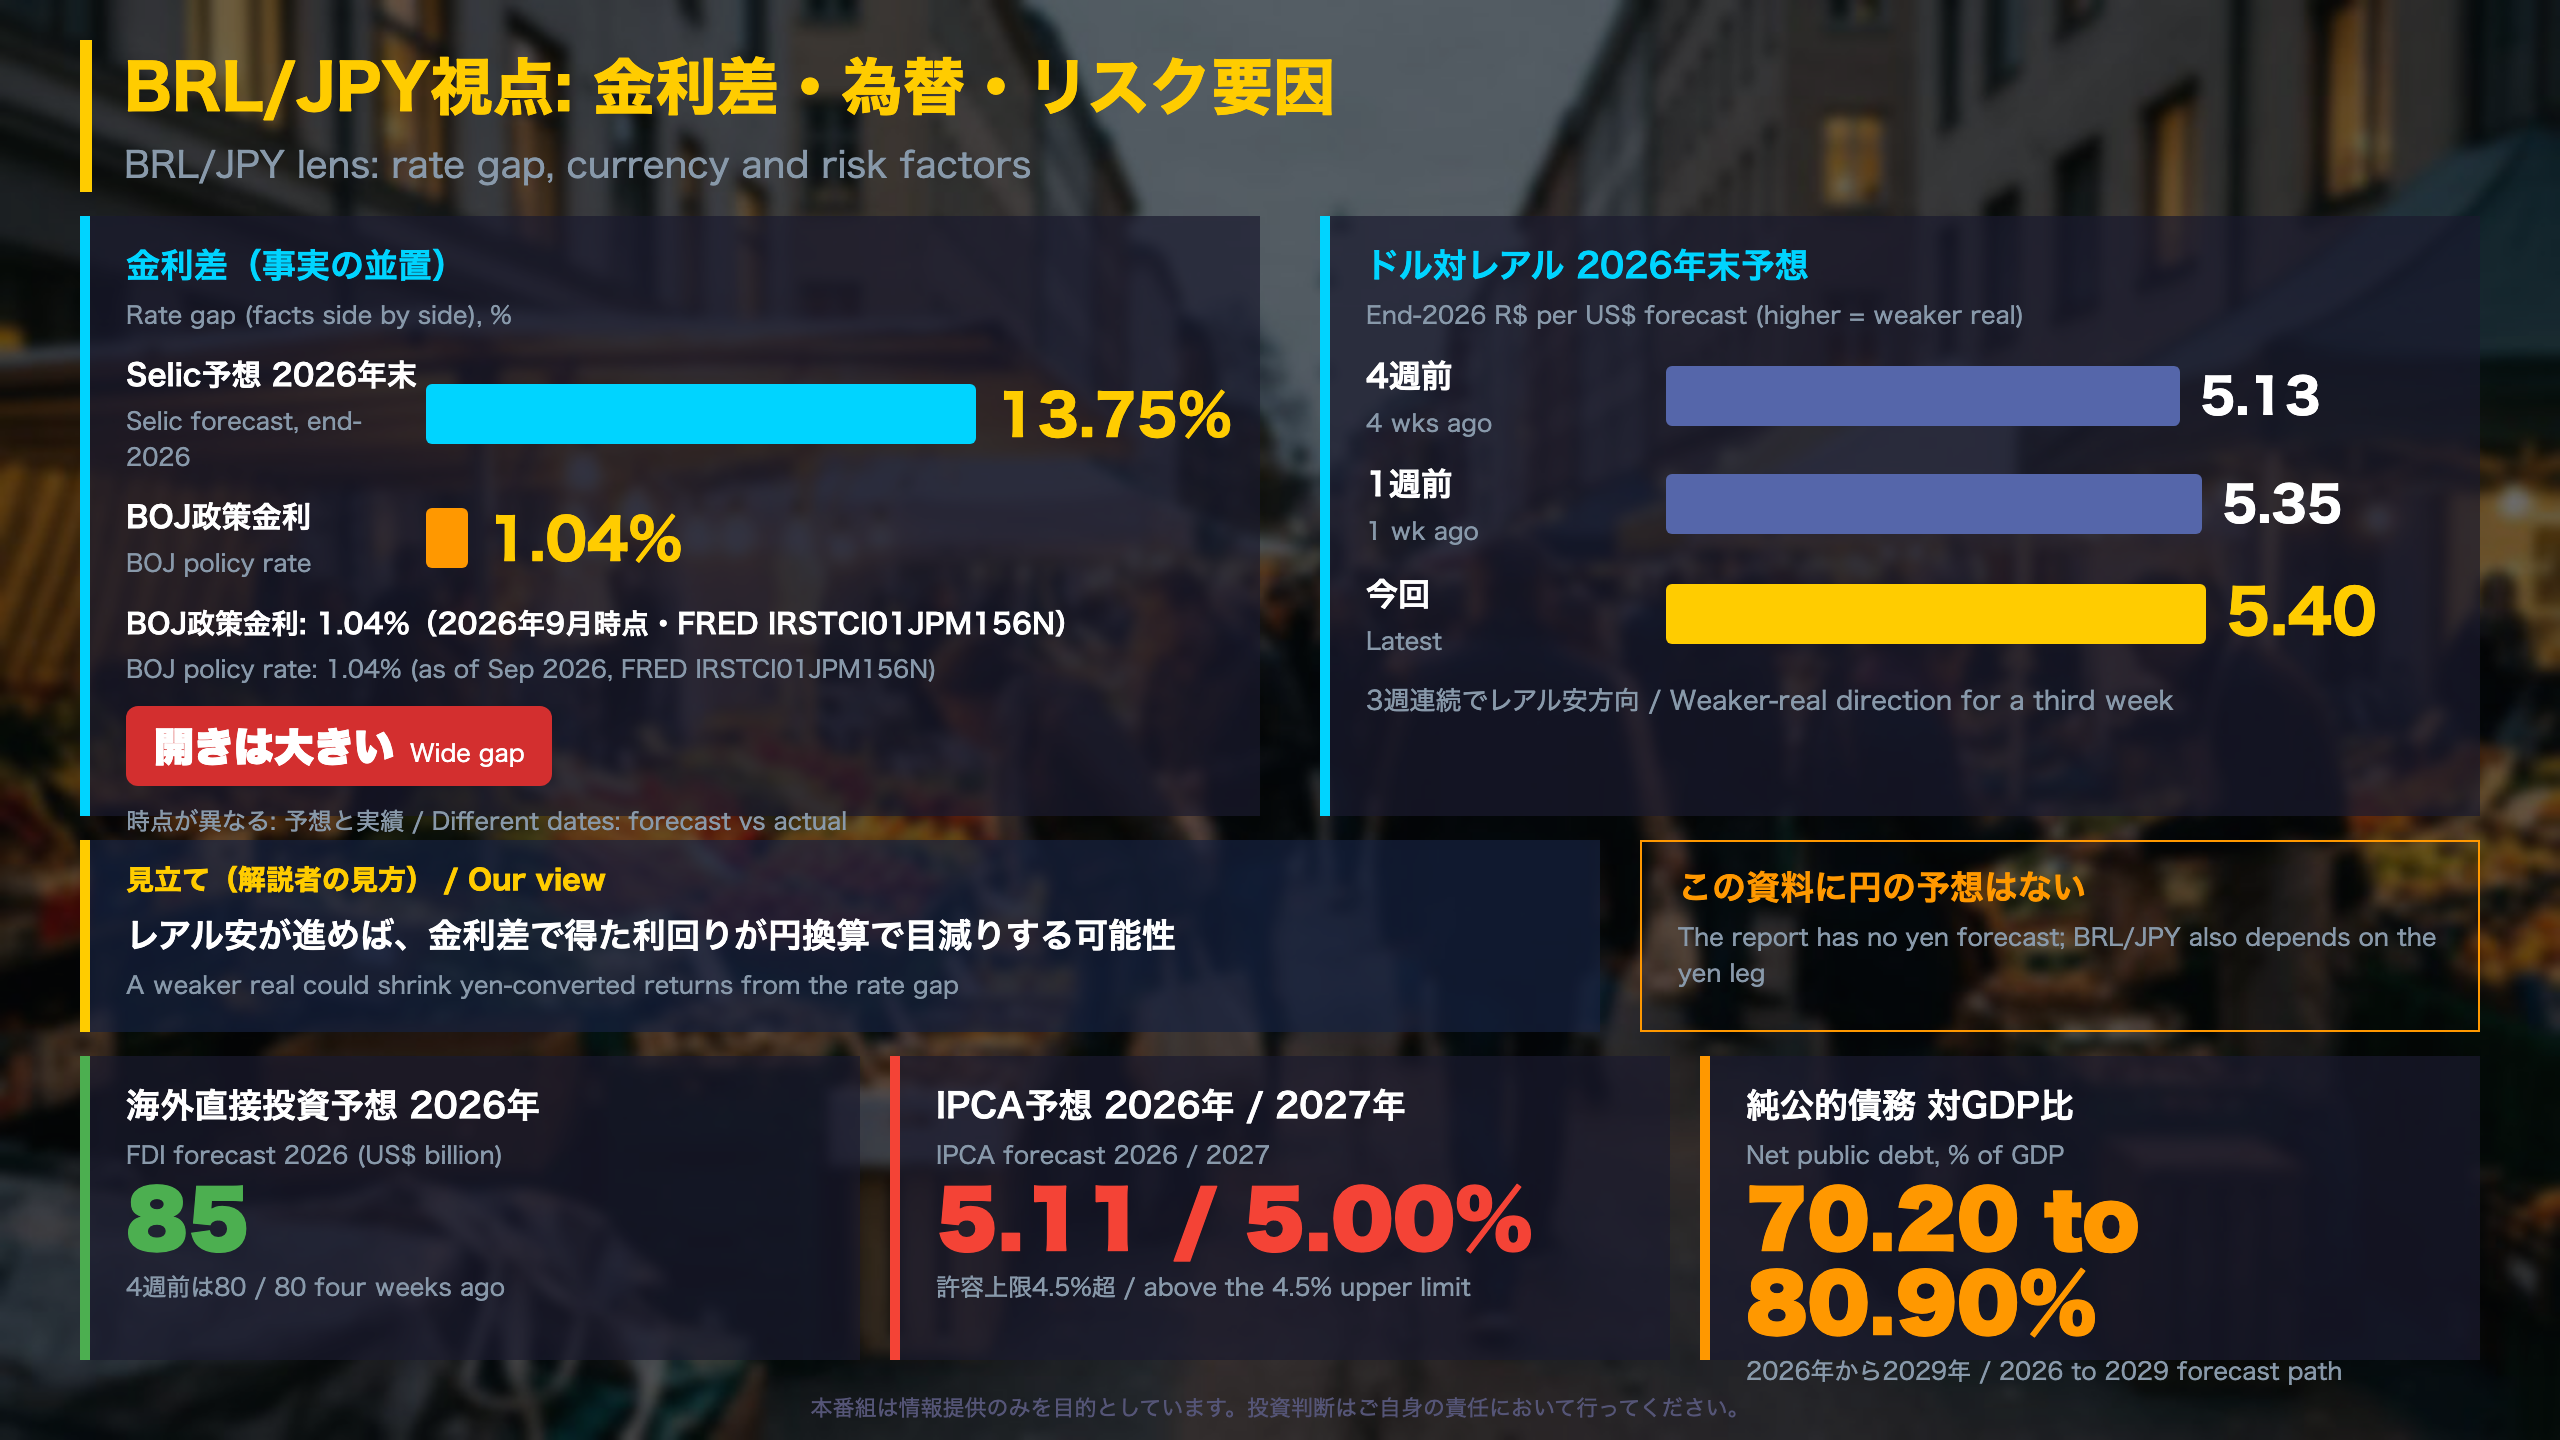
The rate gap. The median Selic forecast for end-2026 is 13.75%. Japan’s policy rate was 1.04% as of September 2026 (FRED IRSTCI01JPM156N). The two numbers come from different dates (a forecast versus a reading), so the 12.71-point gap is a simple comparison only.
The currency. Focus covers R$/US$, not the yen. The end-2026 forecast is 5.40, up from 5.13 four weeks ago and 5.35 one week ago, a third straight weekly rise (a higher number means a weaker real). The 2027 figure is 5.45 and 2028 is 5.48. If the real weakens further, yen-converted returns on BRL assets could shrink, and BRL/JPY also depends on the yen leg.
Risk factors in the data
- Inflation forecasts (5.11% for 2026, 5.00% for 2027) are above the 4.5% upper limit of the target range.
- Net public debt as a share of GDP is forecast to rise from 70.20% (2026) to 80.90% (2029).
- The 2029 primary balance forecast slipped to -0.12% of GDP from -0.10%.
Stabilizers
- The 2026 foreign direct investment forecast is US$85 billion, versus US$80 billion four weeks ago.
- The 2026 current account forecast has held at -US$60 billion for 19 weeks.
This is a summary of facts in the report, not a market forecast.
質疑: 同じ方向に動いた指標と、動かなかった指標
Q&A Addendum: What Moved Together, What Did Not
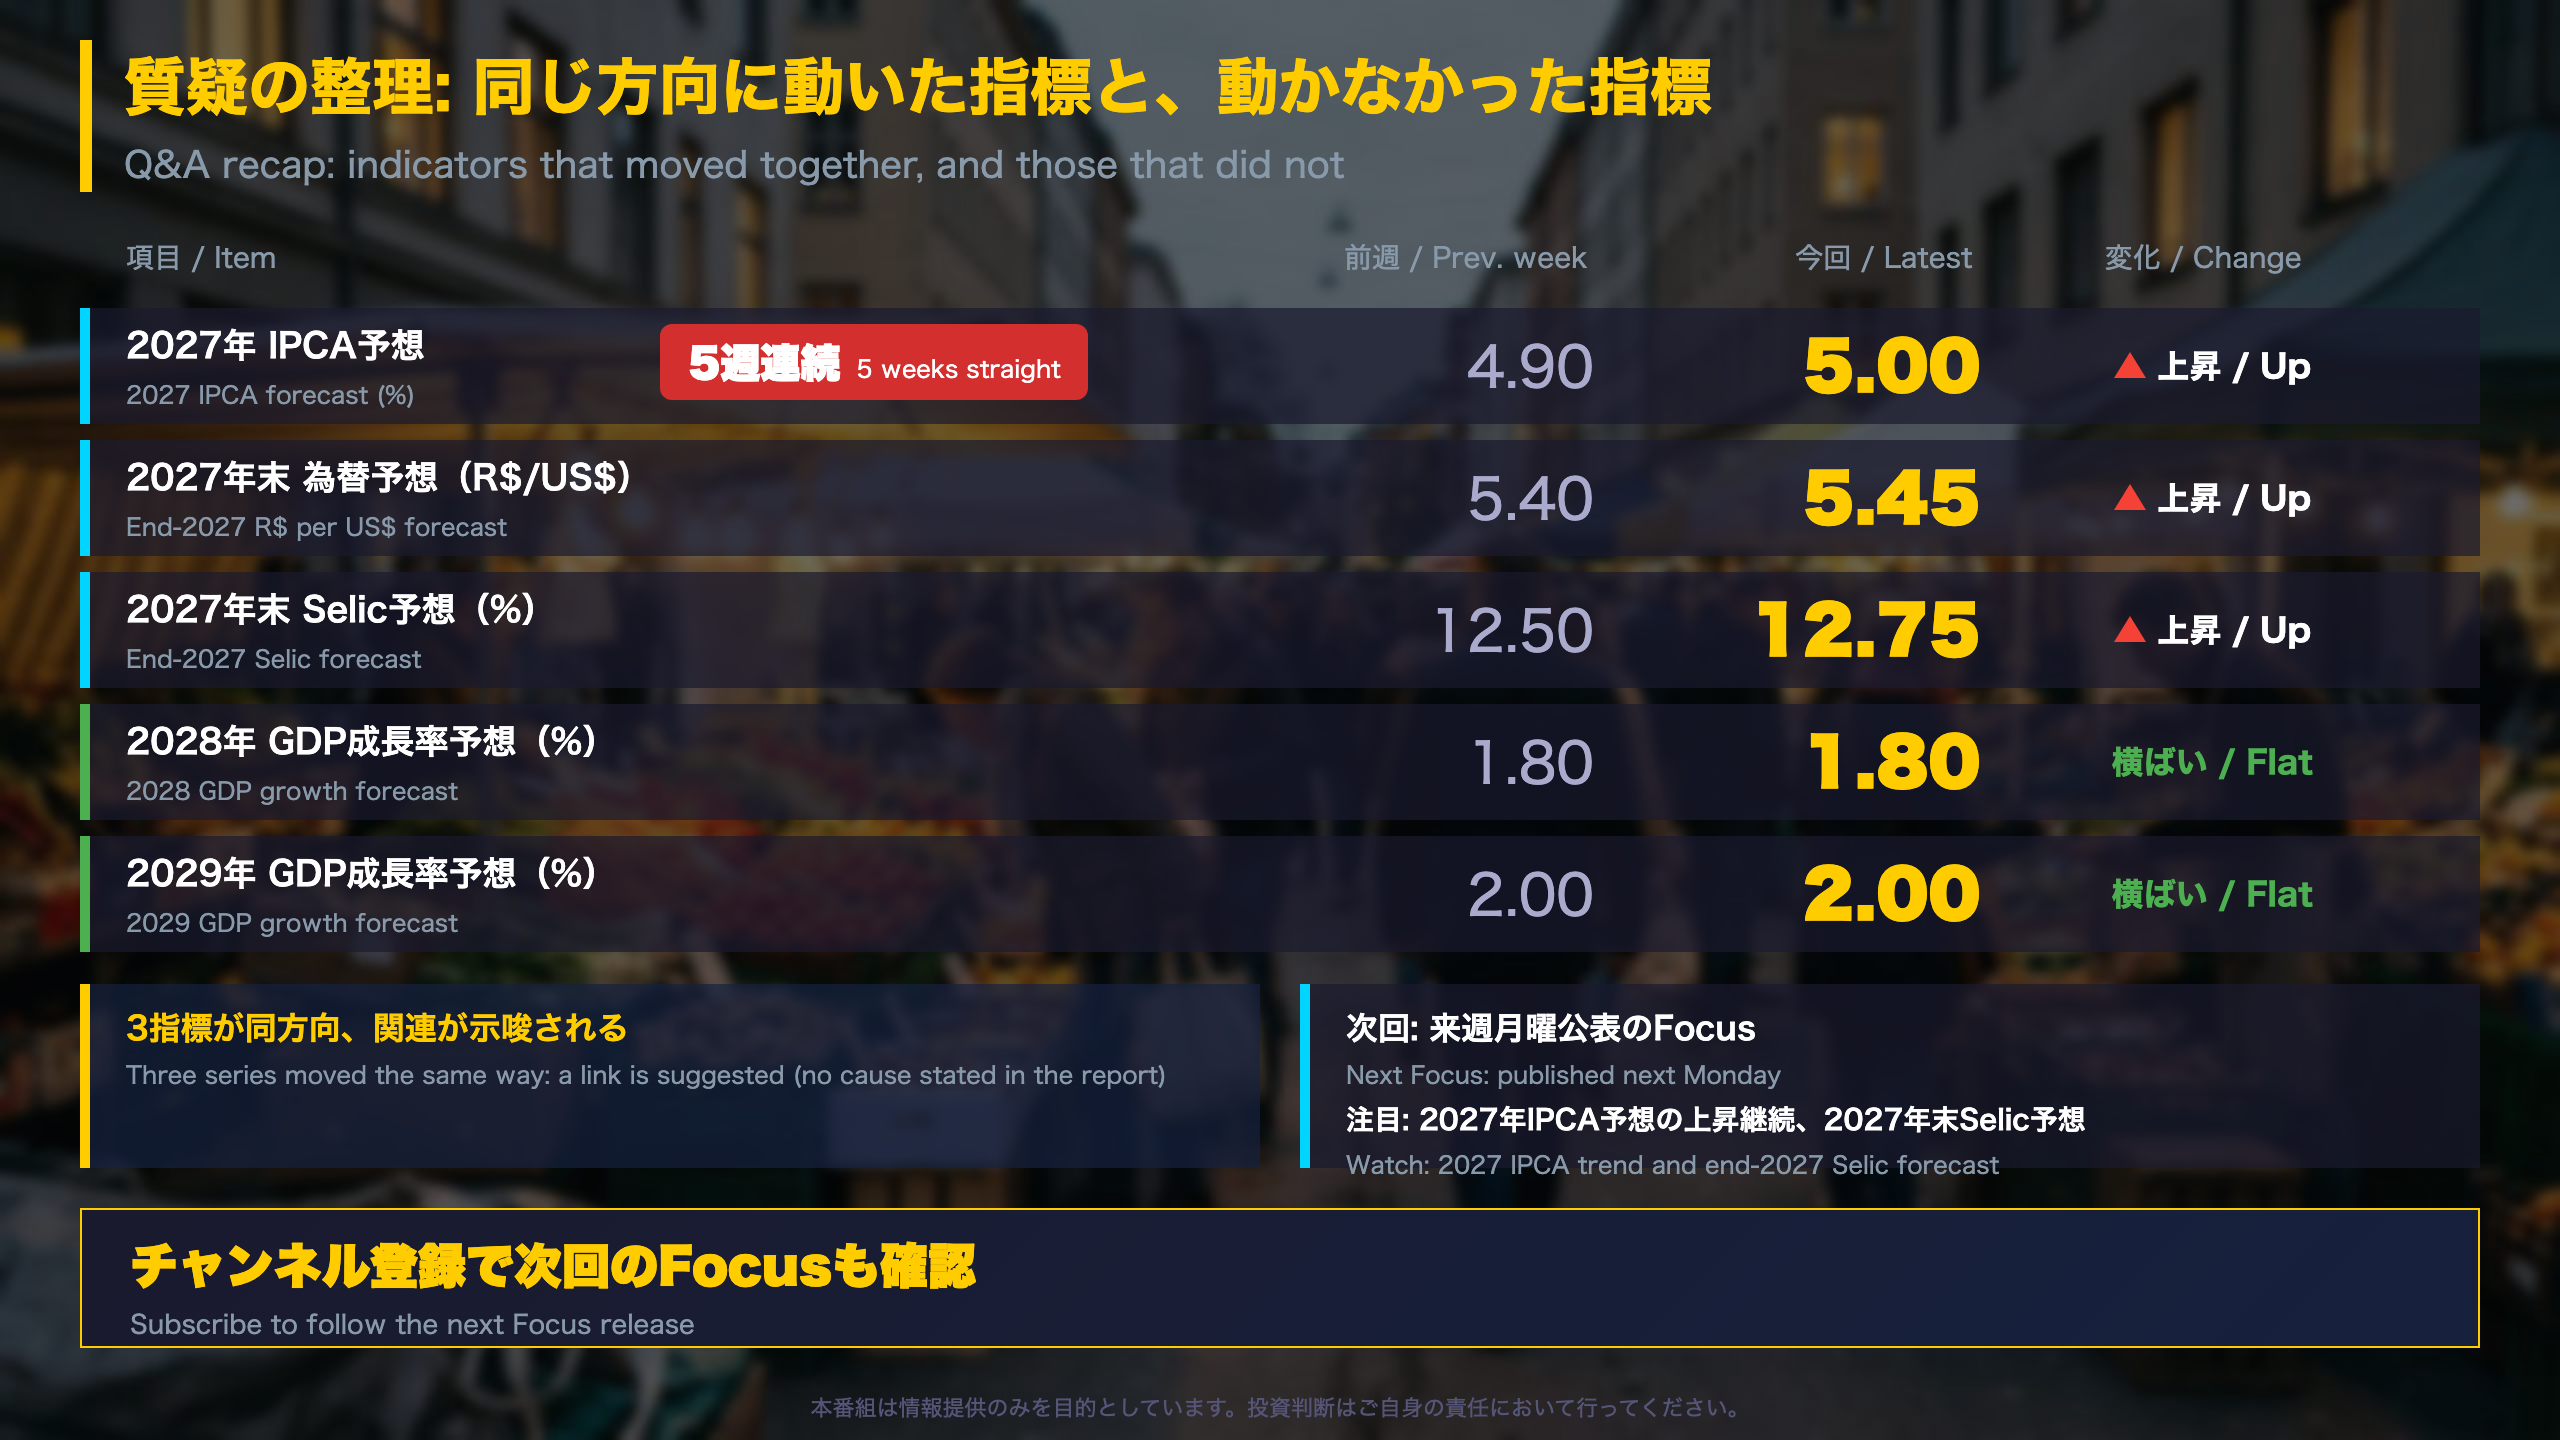
| Item | 1 wk ago | Latest |
|---|---|---|
| 2027 IPCA (%) | 4.90 | 5.00 |
| 2027 year-end R$/US$ | 5.40 | 5.45 |
| 2027 year-end Selic (%) | 12.50 | 12.75 |
| 2028 GDP (%) | 1.80 | 1.80 |
| 2029 GDP (%) | 2.00 | 2.00 |
Causality is not in the report. Focus lists medians; it does not say whether prices, the currency or rates moved first. That three series rose together is a fact; a link between them is our hypothesis, supported by the fact that several indicators point the same way.
Alternative readings
- Cautious: a weaker real and higher inflation expectations may be narrowing the room for rate cuts.
- Neutral: medians can shift when the mix of respondents changes, so a one-week change contains noise.
Next Focus (next Monday)
- Does the 2027 IPCA forecast rise for a sixth week?
- Does the end-2027 Selic median move from 12.75%?
- Is 13.75% for end-2026 maintained?
Stable readings matter too: the 2026 current account forecast has stayed at -US$60 billion for 19 weeks, and the 2027 nominal fiscal balance at -8.50% of GDP for 11 weeks.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.