📺 Watch the Full Video Analysis
This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-11-05 06:21 JST)
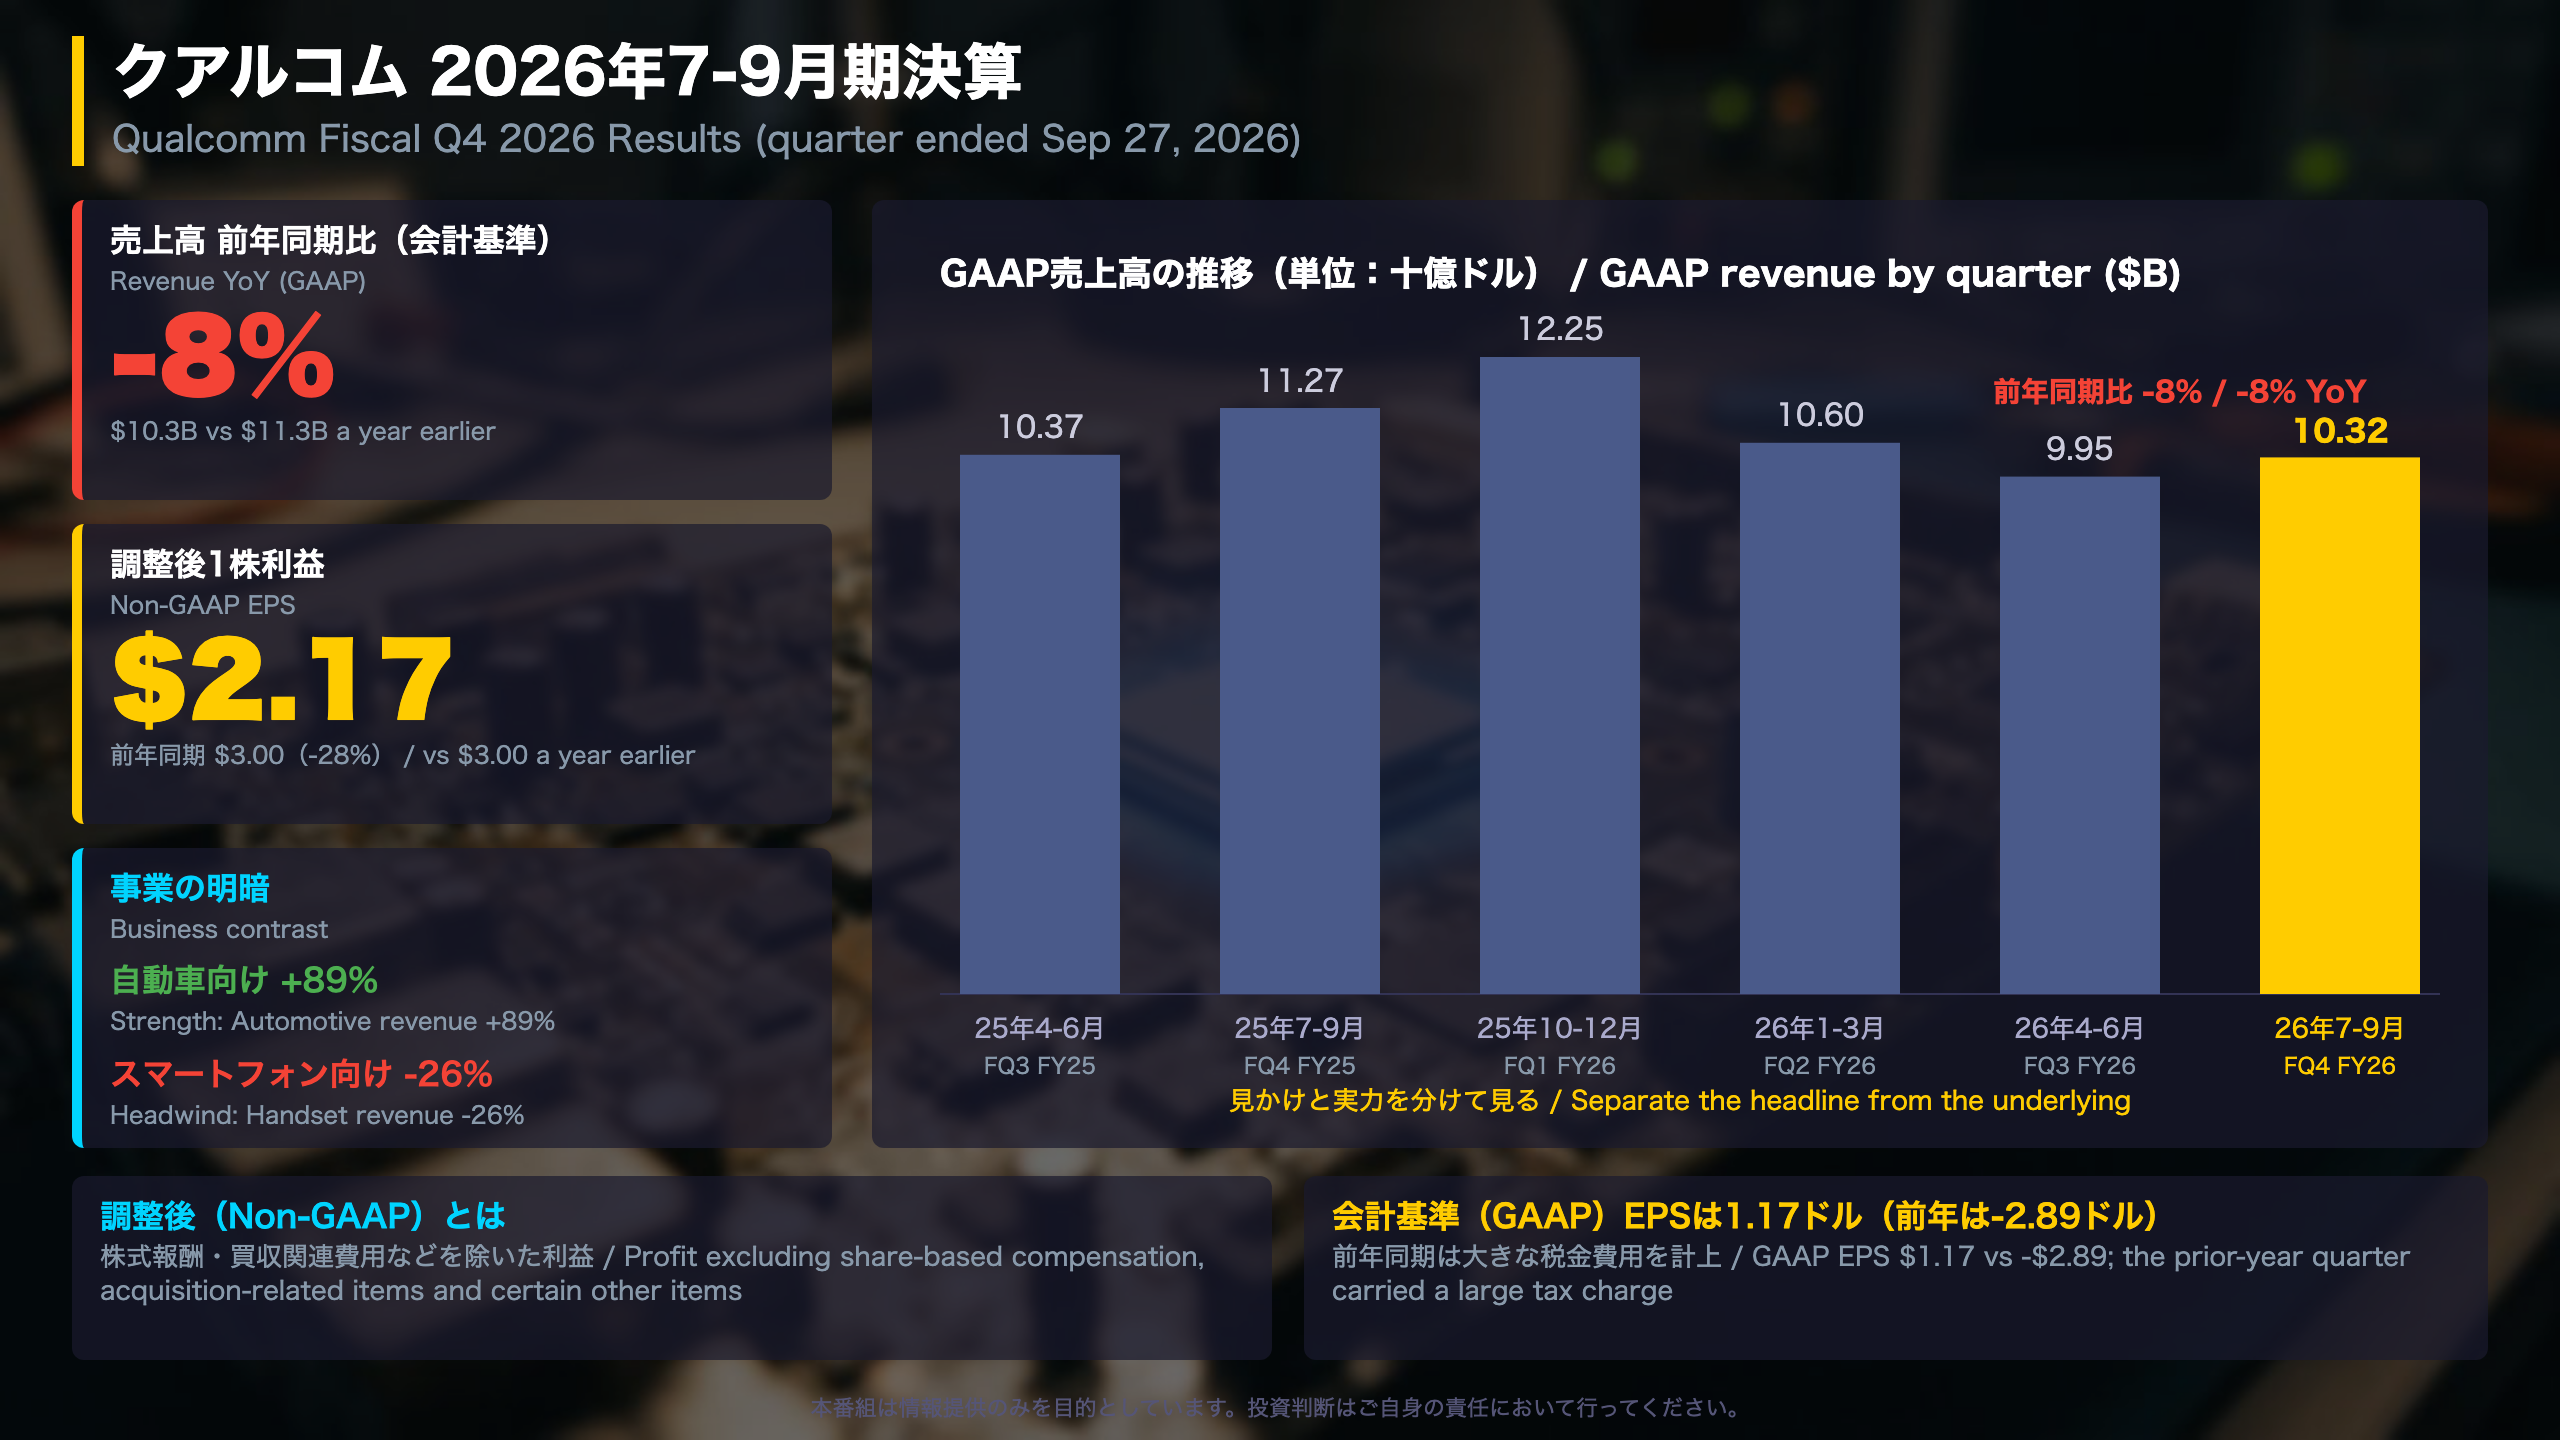
📊 Qualcomm (QCOM) reported fiscal Q4 2026 (Jul-Sep): revenue $10.3B, down 8% YoY; non-GAAP EPS $2.17 vs $3.00 a year ago.
📈 Automotive revenue jumped 89% to a quarterly record, and the company projects non-handset revenue to grow more than 60% next fiscal year, reiterating its $5B Data Center target.
⚠️ Handset revenue fell 26%. GAAP EPS of $1.17 looks better only because last year’s quarter carried a large tax charge.
💡 Q1 FY27 guidance: revenue $10.4B-$11.2B, non-GAAP EPS $2.15-$2.35. A balanced look at strengths and headwinds.
サマリー:売上8%減、調整後EPSは2.17ドル
Qualcomm FQ4 2026: Headline vs. Underlying Picture
Who reports and when: Qualcomm (NASDAQ: QCOM) closed fiscal 2026 on September 27, 2026 and published results on November 4. Its fiscal year ends in late September, so ‘fiscal Q4’ covers roughly July to September.
Key numbers
- GAAP revenue: $10.32B, -8% YoY; non-GAAP revenue $10.44B (-7%)
- GAAP EPS $1.17 vs. a loss of $2.89; non-GAAP EPS $2.17, -28%
- Full year: GAAP EPS $12.70 (+153%), lifted by a $5.7B tax benefit ($5.32/share); non-GAAP EPS $10.54 (-12%)
GAAP vs. non-GAAP: GAAP is the accounting-standard measure. Qualcomm’s non-GAAP figure strips out share-based compensation, acquisition-related items and certain tax items, and from fiscal 2026 applies a fixed non-GAAP tax rate (12.5% in Q4). The prior-year quarter carried a large tax charge tied to a valuation allowance, so the GAAP year-over-year swing looks far better than the operating trend.
Context for global investors
Qualcomm is a hybrid of a chip designer and a patent licensor. Its QCT unit sells chips, while QTL collects royalties on its patent portfolio at roughly 70% pre-tax margins. The release itself says revenue landed at the high end of the company’s own guidance; no third-party consensus is used here.
Balanced read: Automotive and IoT growth (+36% combined, per the CEO) is a genuine positive, while the handset decline and lower adjusted profit are real headwinds. Market-impact judgments are outside the scope of the release.
深掘り1:事業ごとの明暗(自動車+89%、スマホ-26%)
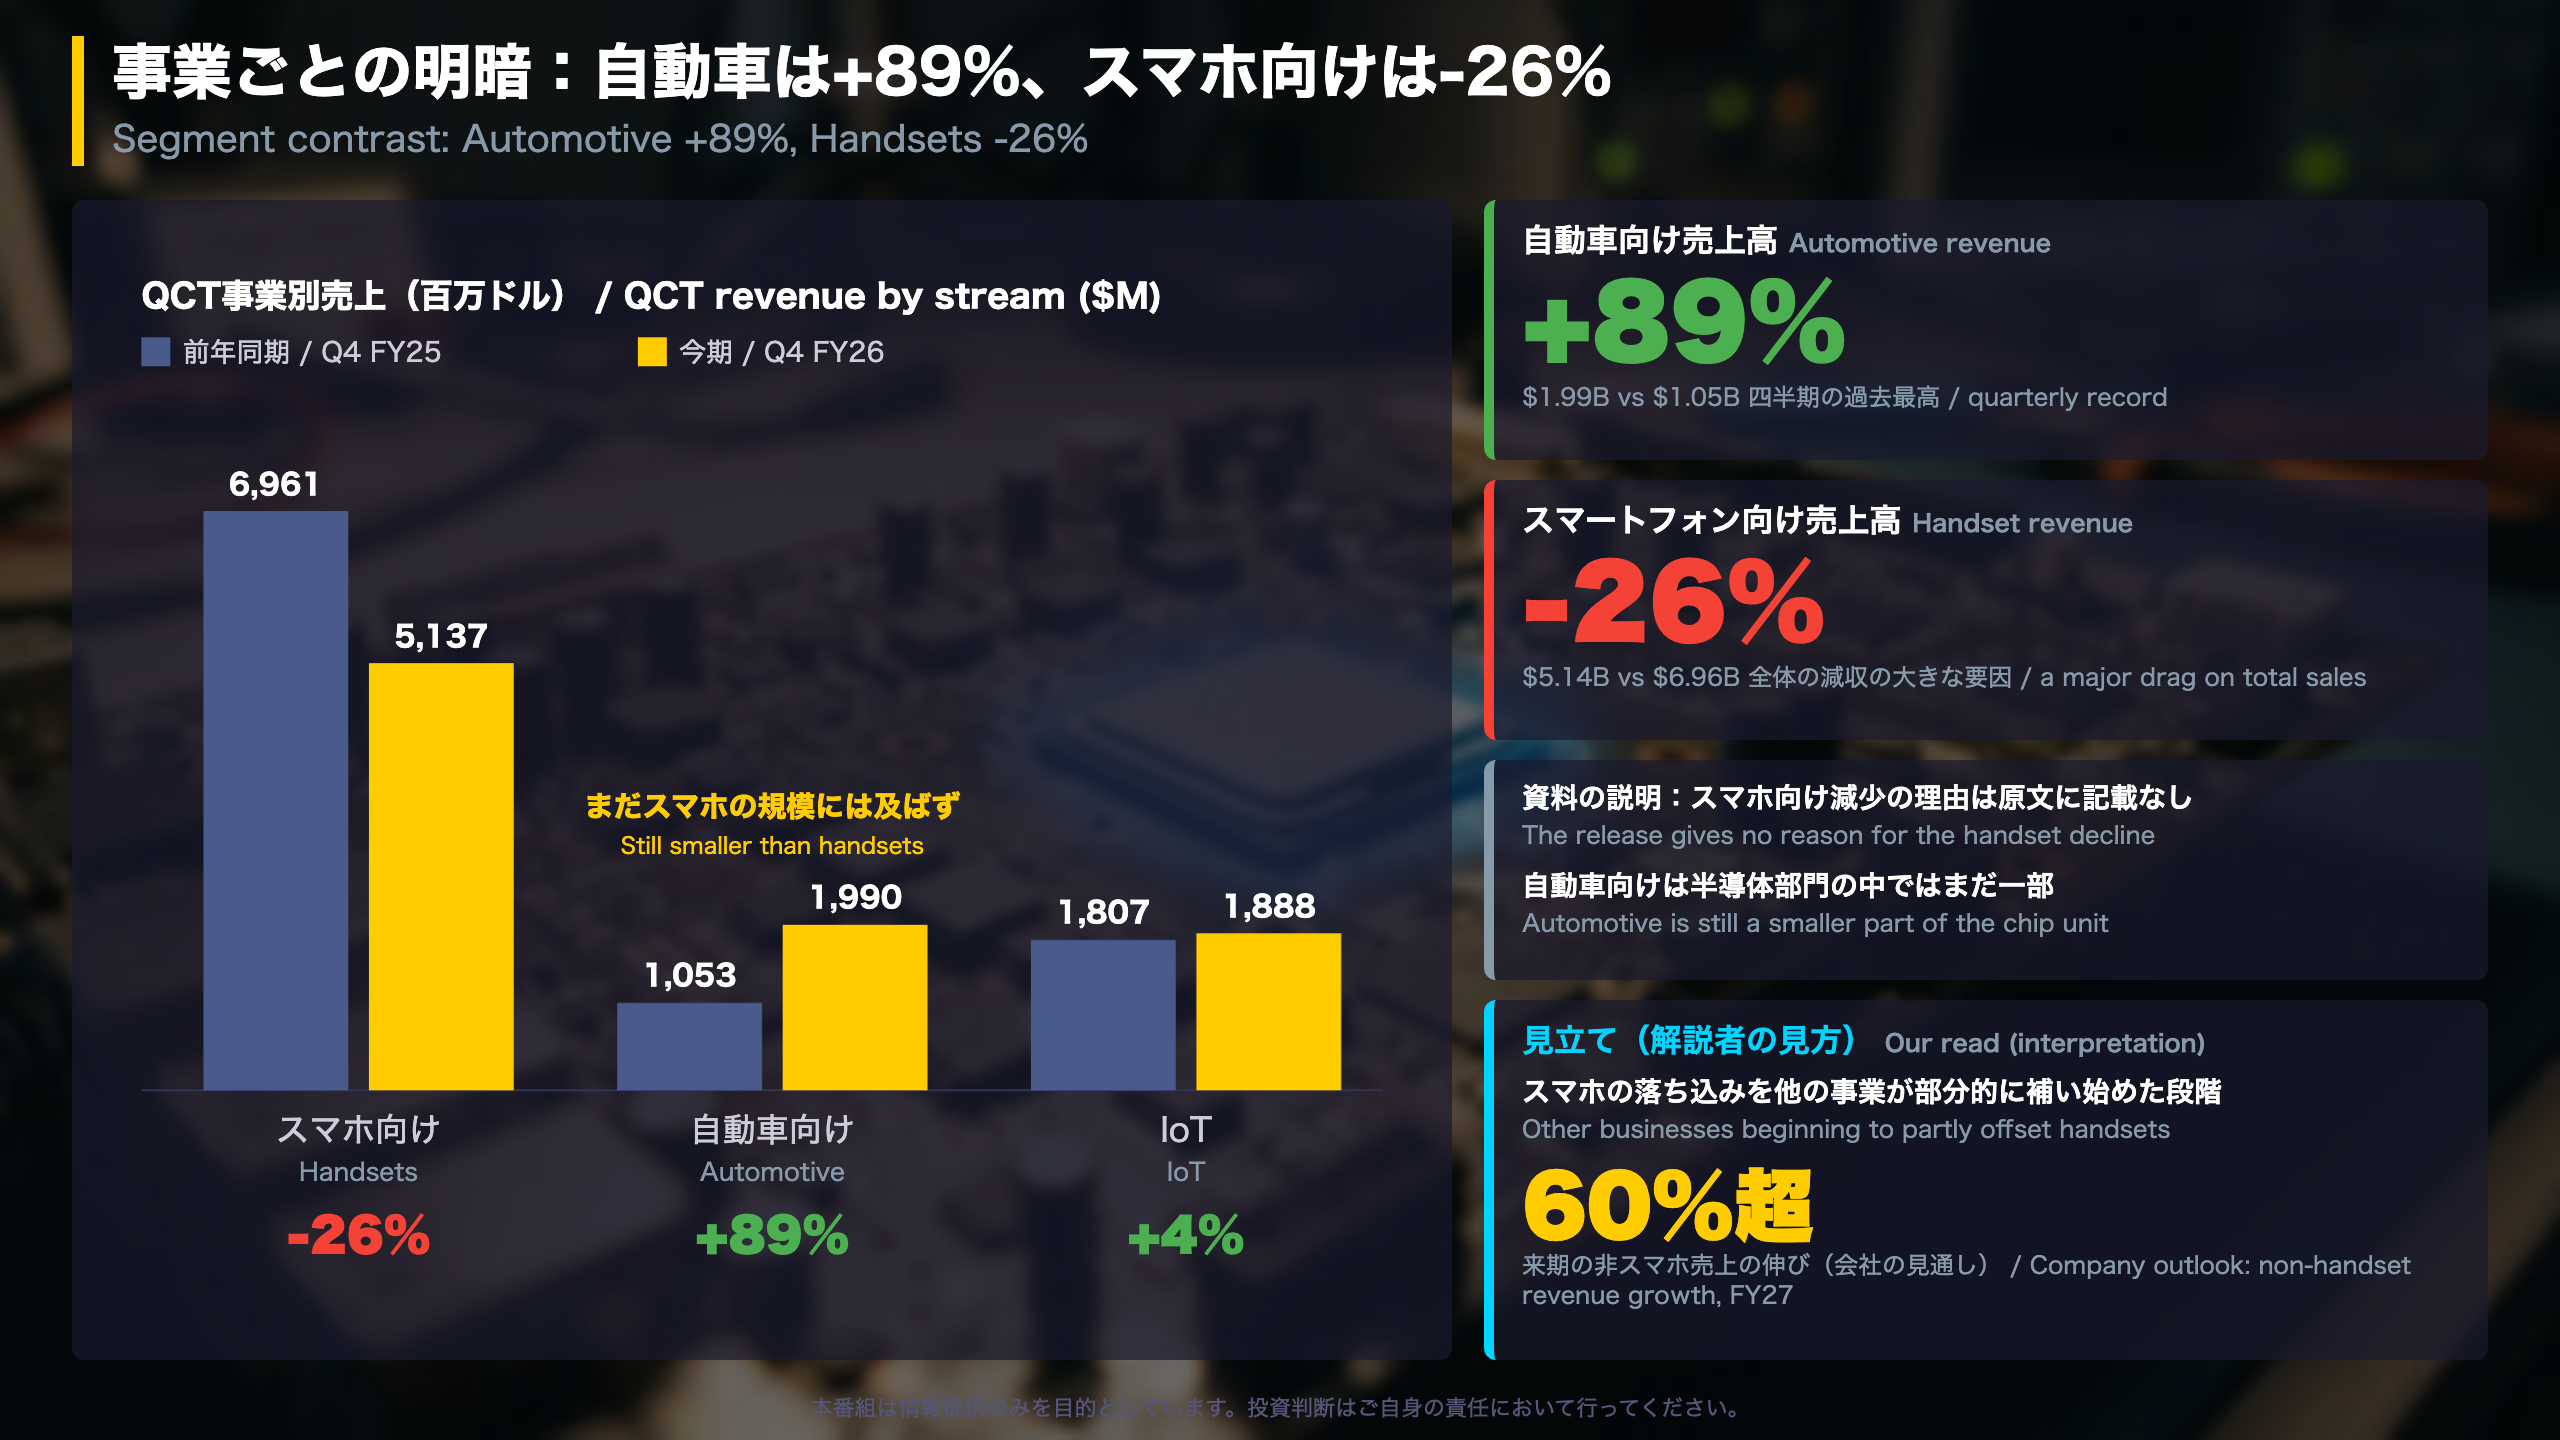
Inside QCT: Where the Revenue Comes From
Business structure for readers new to Qualcomm: QCT (Qualcomm CDMA Technologies) is the chip business, split here into handsets, automotive and IoT. QTL (Qualcomm Technology Licensing) collects patent royalties and is far more profitable per dollar of revenue.
Q4 FY26 vs Q4 FY25 ($M)
- Handsets: 5,137 vs 6,961 (-26%); full year -13%
- Automotive: 1,990 vs 1,053 (+89%); full year 6,004 vs 3,957 (+52%)
- IoT: 1,888 vs 1,807 (+4%); full year +8%
Margins
QCT pre-tax margin was 24% vs 29%; QTL stayed near 70% (72% a year ago). R&D rose to $2.68B from $2.37B, but the release does not link it to the margin decline.
International comparison
The handset-to-automotive shift resembles other chip suppliers diversifying beyond smartphones, but the release gives no peer data, so no cross-company comparison is drawn here. The company also renewed long-term license agreements with Apple, Huawei and Transsion, supporting the royalty stream.
Two readings
- Constructive: automotive growth is visible over the full year, not just one quarter.
- Cautious: the handset decline was roughly twice the size of the automotive gain in dollar terms, and the release does not explain it.
Our interpretation: other businesses are beginning to partly offset handsets. That is a view, not a stated fact, and one quarter cannot establish a structural shift.
深掘り2:来期見通しとコスト圧力
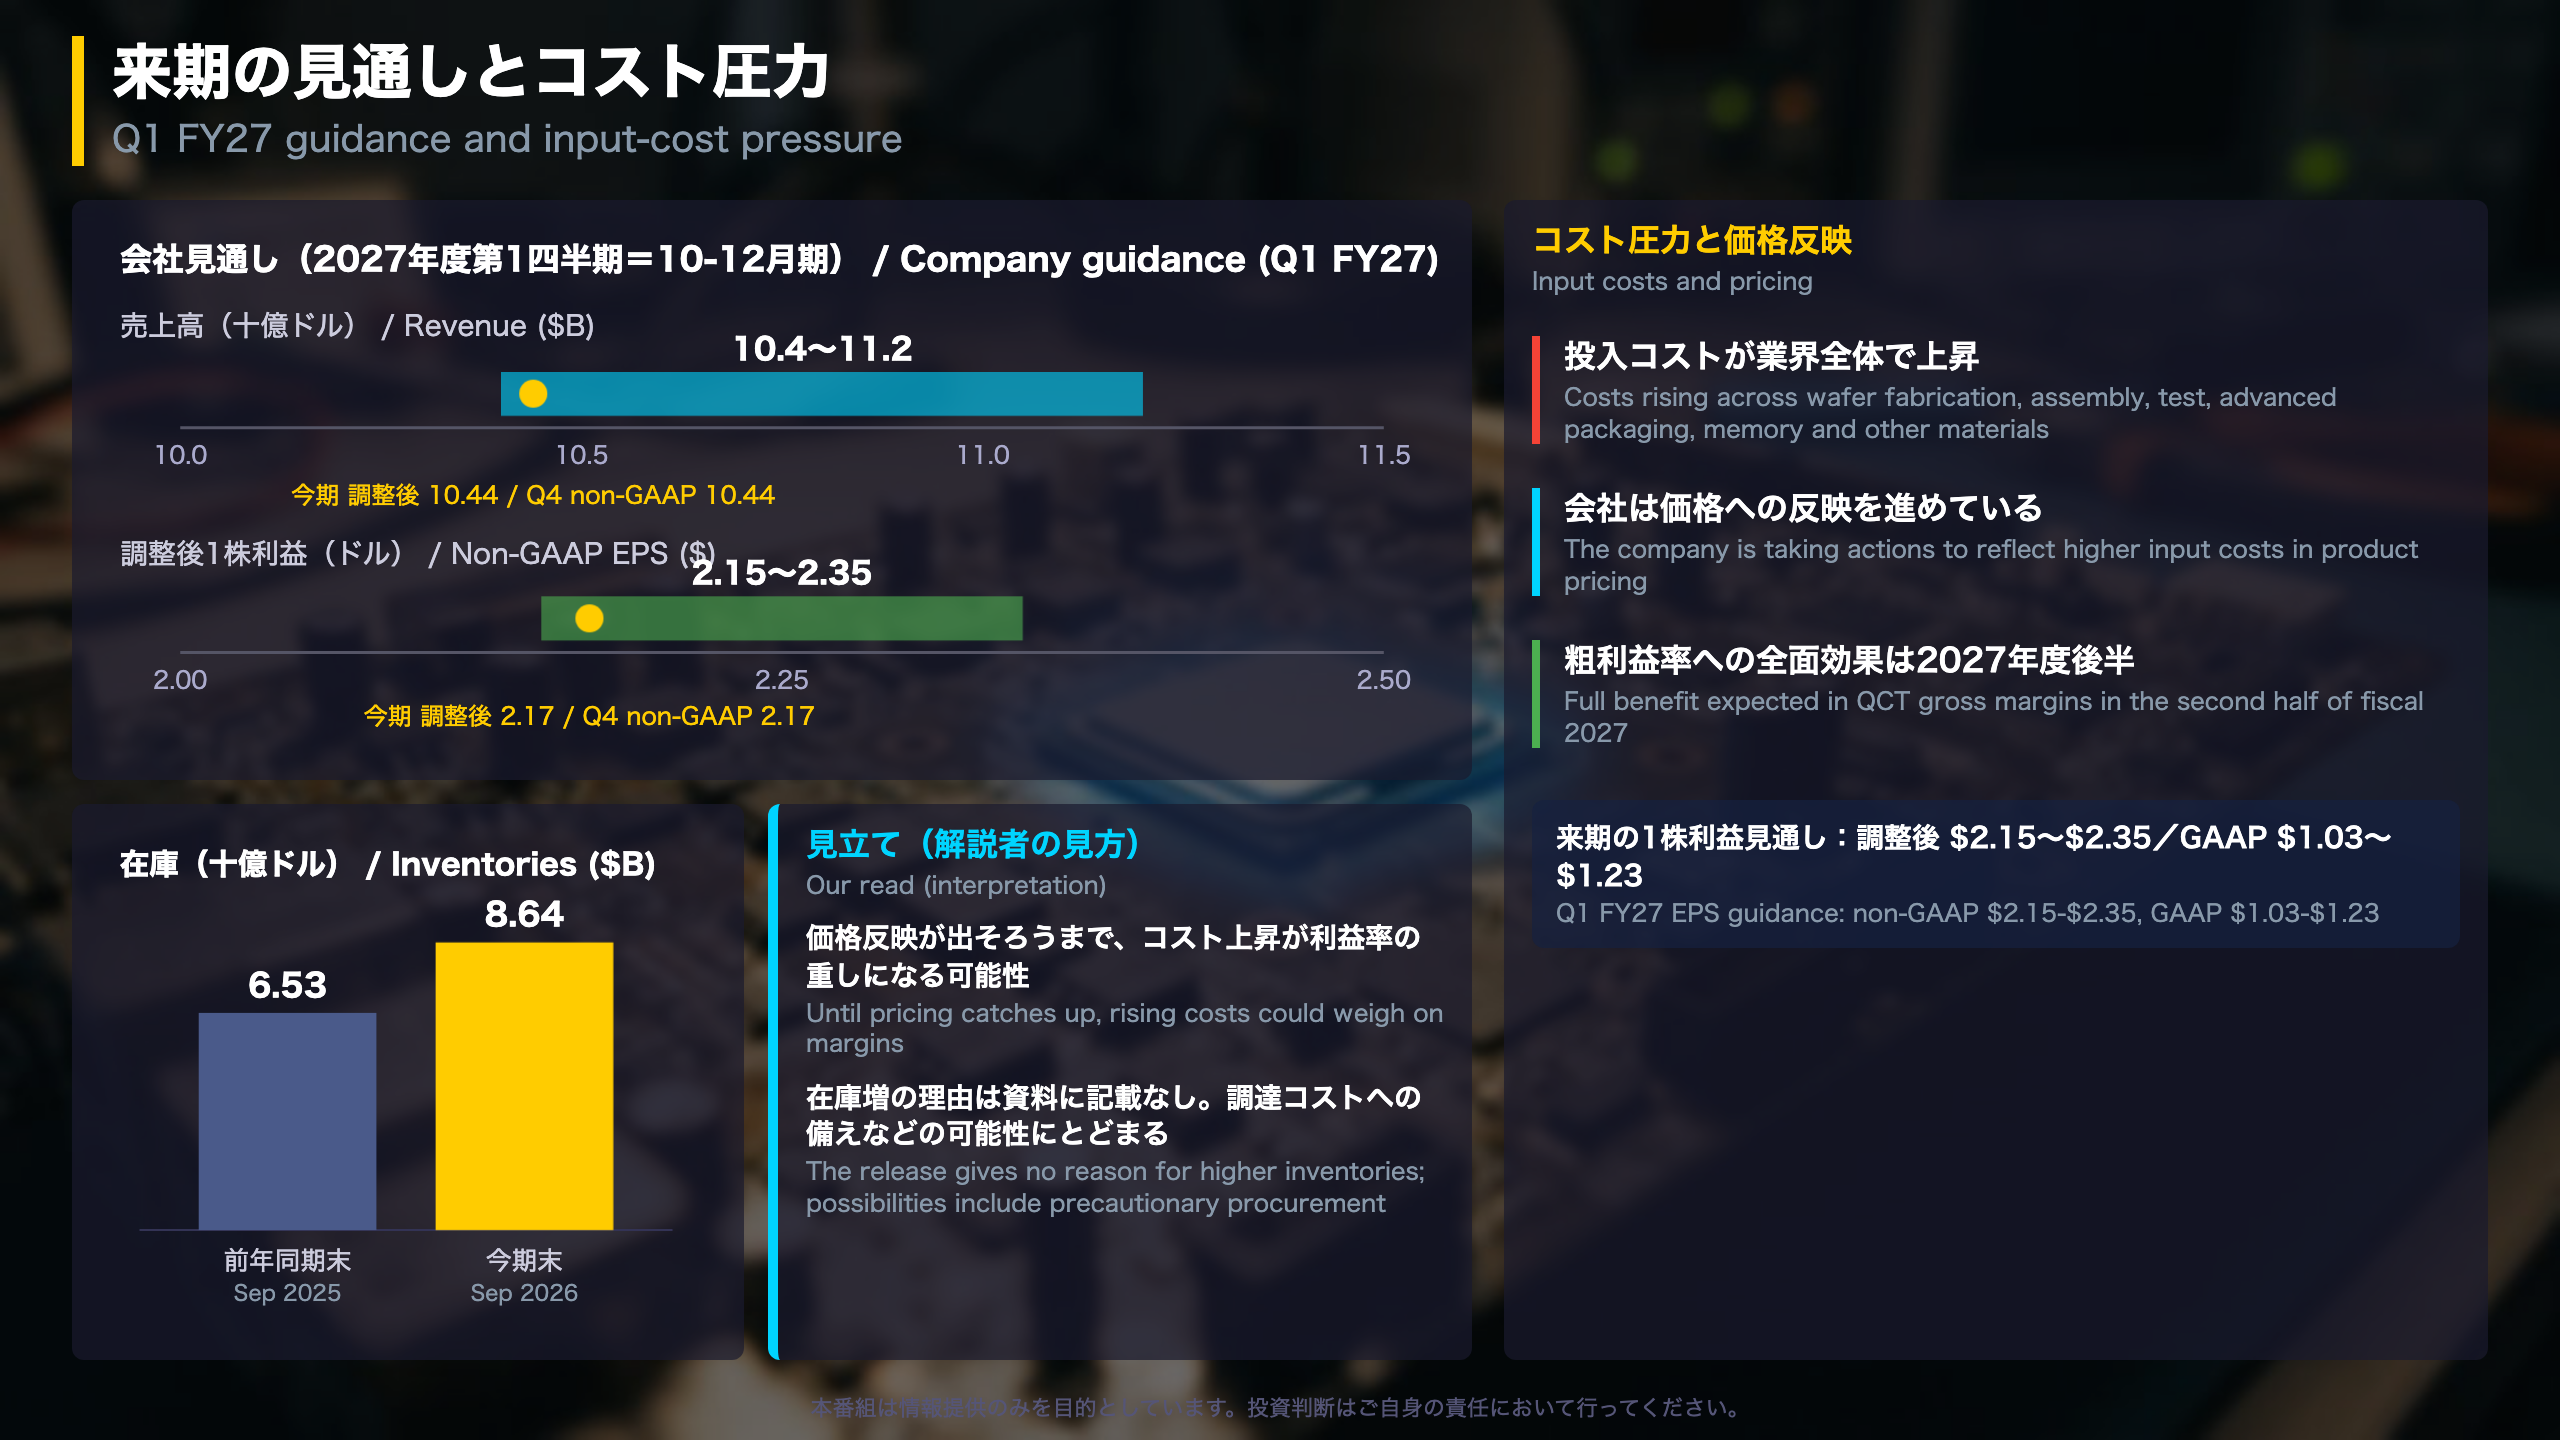
Guidance, Input Costs and the Balance Sheet
What guidance means here: Qualcomm gives a one-quarter-ahead range rather than a full-year forecast. For Q1 FY27 (Oct-Dec 2026) it guides revenue of $10.4B-$11.2B, non-GAAP EPS of $2.15-$2.35 and GAAP EPS of $1.03-$1.23. The gap between the two EPS ranges is share-based compensation ($0.99) plus acquisition-related items ($0.13).
Cost pressure
The release says semiconductor input costs are rising broadly across wafer fabrication, assembly, test, advanced packaging and memory. Qualcomm is raising prices and expects the full benefit in QCT gross margin in the second half of fiscal 2027.
Balance-sheet and cash-flow facts
- Inventories: $8.64B vs $6.53B a year earlier
- Capex (full year): $2.49B vs $1.19B
- Operating cash flow: $11.1B vs $14.0B
- Capital returned: $11.7B (buybacks $7.8B, dividends $3.9B)
Two readings
- Constructive: if pricing actions work, margin recovery is possible in the second half of FY27.
- Cautious: higher inventories and capex alongside lower operating cash flow point to a transition-period burden. The release gives no reason for the inventory increase, so this is not a conclusion.
Comparison point for global readers: unlike a Bank of Japan or Fed release, this is corporate guidance and can be revised. The release itself warns that actual results may differ materially.
質疑で深める:データセンター目標と次の確認点
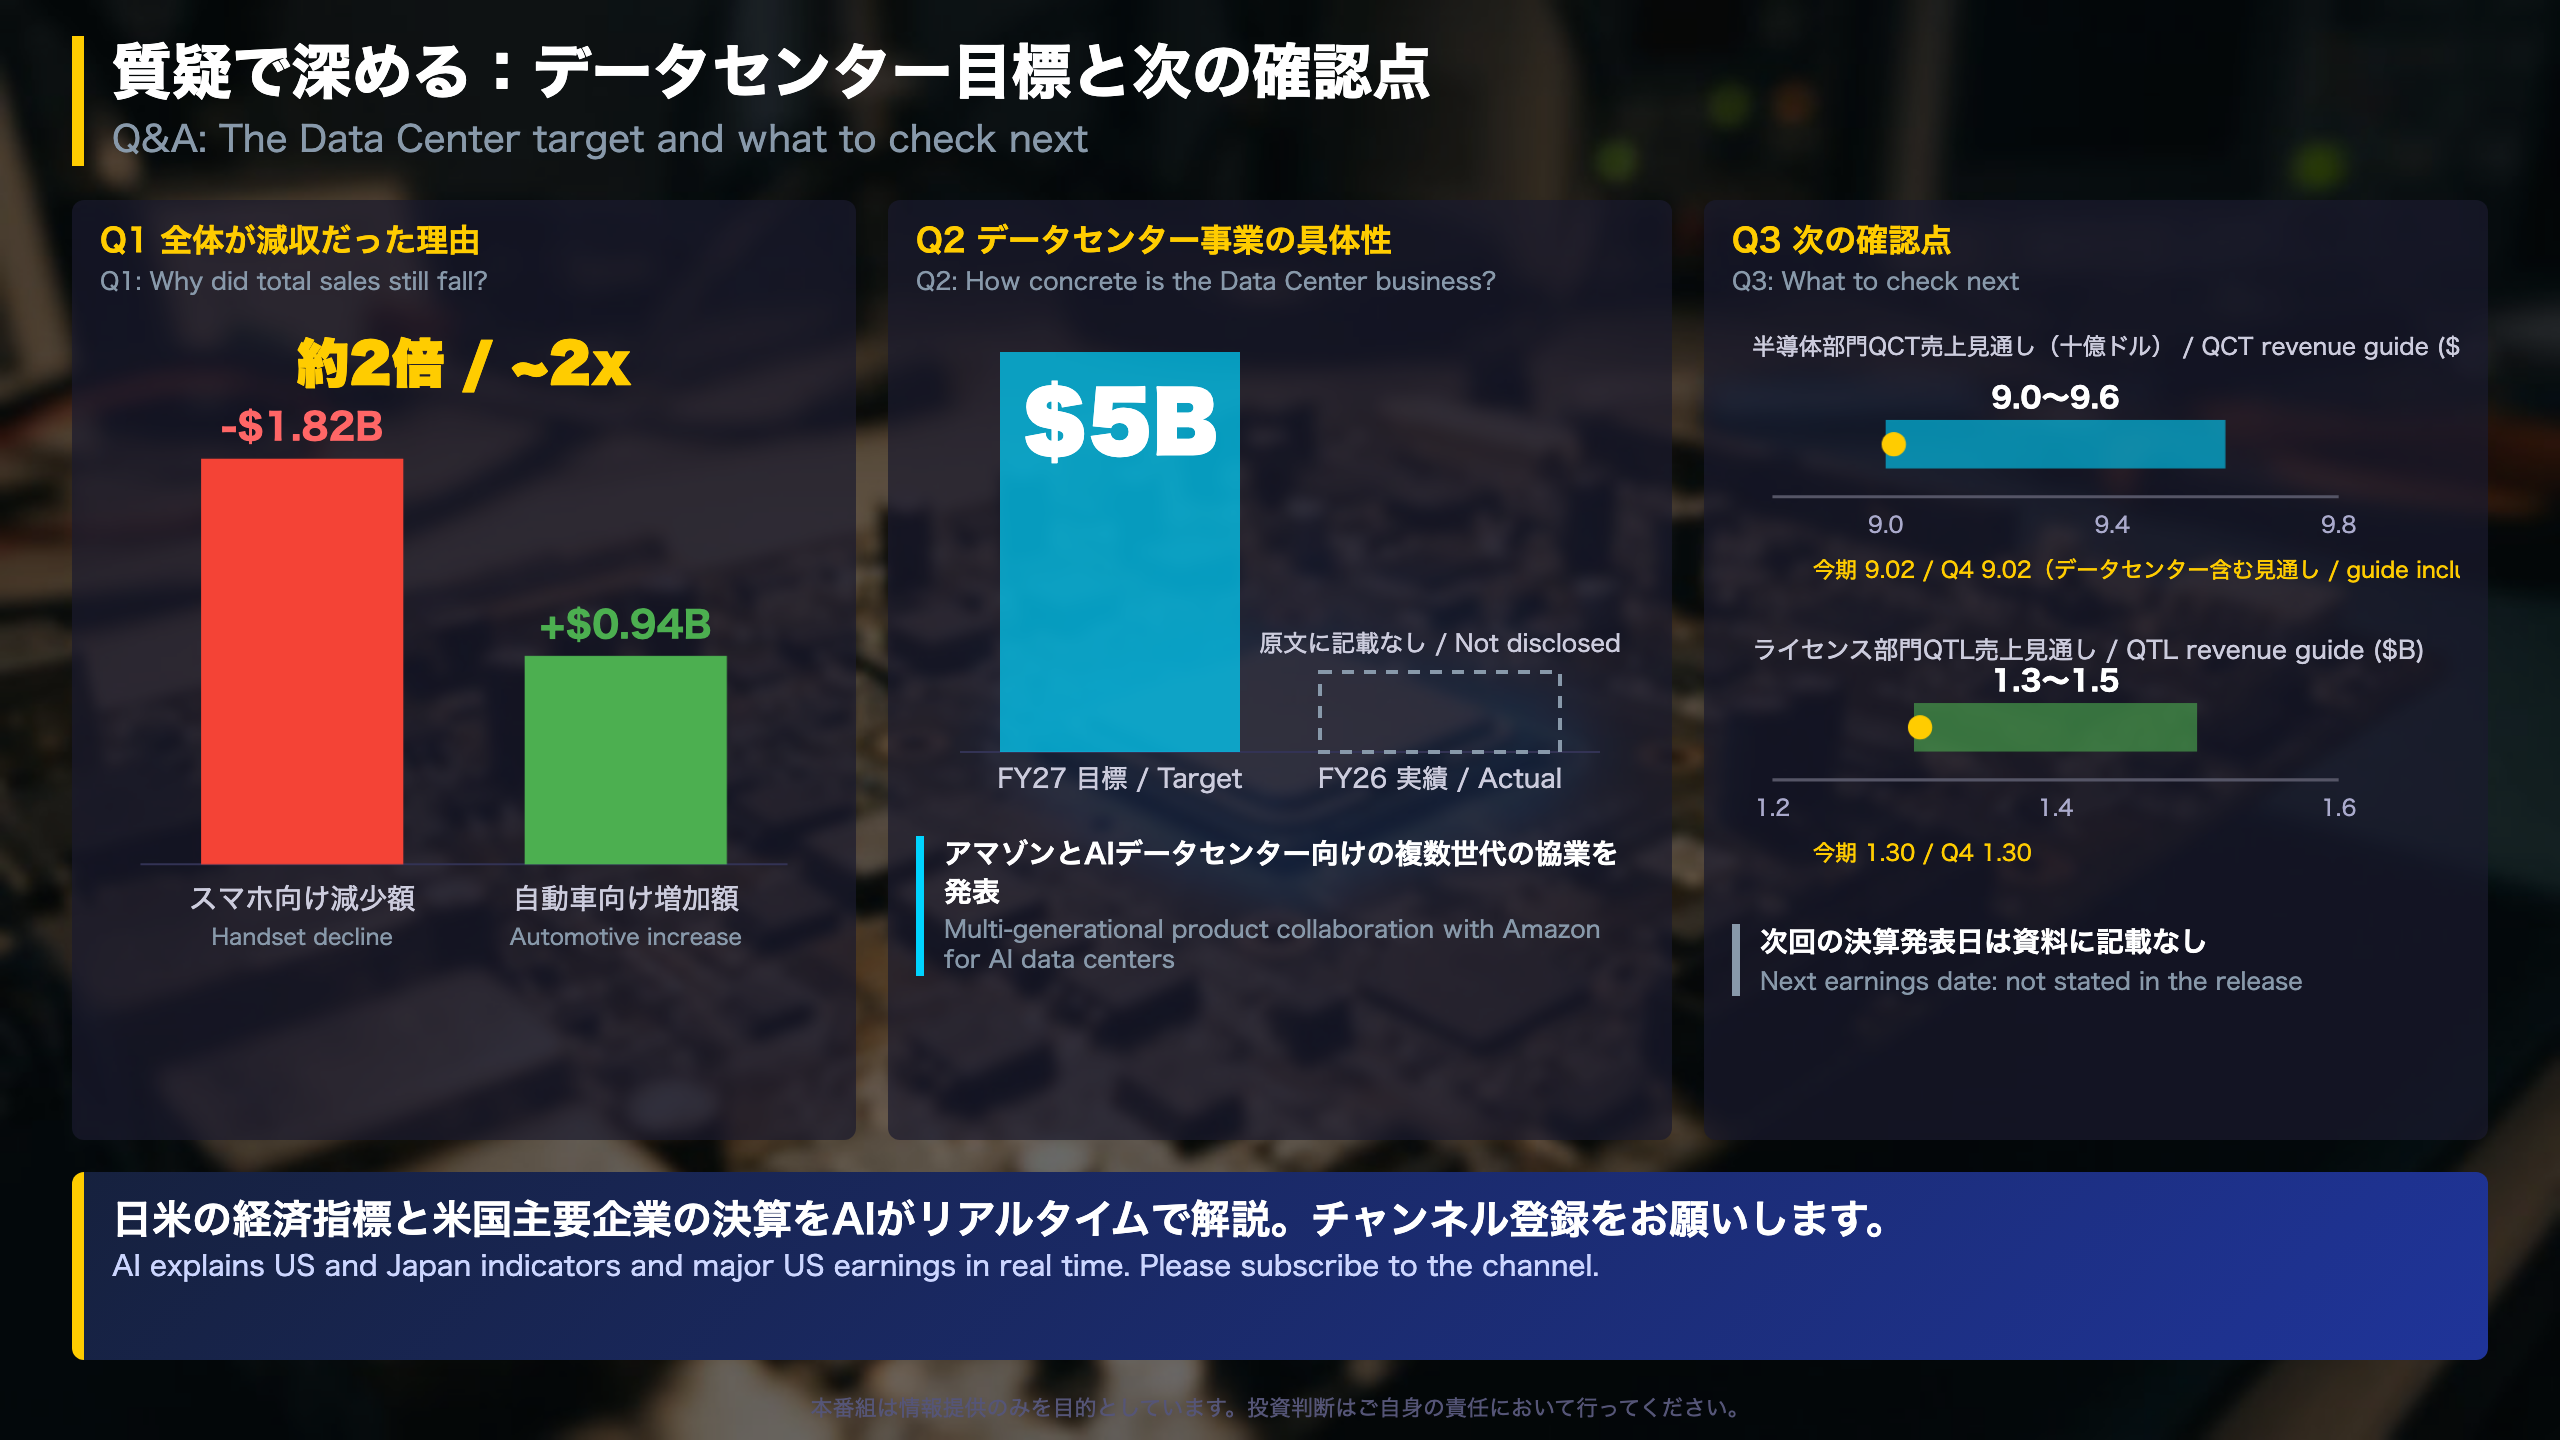
Q&A Follow-up: The Data Center Target and Capital Return
Why this matters: Qualcomm is trying to reduce its dependence on smartphones, historically its largest chip customer base. The release names Data Center as the next leg alongside automotive and IoT.
What the company stated
- FY27 Data Center revenue target of $5B, reiterated
- A multi-generational product collaboration with Amazon for AI data centers
- Non-handset revenue projected to grow more than 60% in FY27 (CEO)
The release gives no current Data Center revenue figure, so the target cannot yet be checked against results.
Dollar comparison
Handset revenue fell by about $1.82B YoY while automotive rose by about $0.94B, so the decline was roughly twice the gain (calculated from the release’s figures).
Capital return
For the year, Qualcomm returned $11.67B: $7.82B in buybacks and $3.85B in dividends. In Q4 the total was $2.0B.
Balanced view
- Constructive: renewed license agreements with Apple, Huawei and Transsion support royalty income; the Data Center target was maintained.
- Cautious: the company itself cites reliance on a small number of handset customers, China concentration and U.S.-China tensions as risks.
Next checkpoints
The Q1 FY27 QCT revenue guide of $9.0B-$9.6B (including Data Center) and growth outside handsets. The release does not state the next earnings date.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.