📺 Watch the Full Video Analysis
This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-11-01 01:25 JST)
📊 D.R. Horton, the largest US homebuilder by volume, reported fiscal Q4 2026 (July-September) results on Oct 29.
📉 Diluted EPS was $2.67 vs $3.04 a year earlier (-12%); net income fell 18%. Net orders fell 7% and the cancellation rate rose to 23%.
📈 Backlog grew year over year, the quarterly dividend was raised 11%, and debt to total capital is 20.8%.
💡 FY2027 revenue guidance of $30-32B sits below FY2026 actual of $33.0B.
⚠️ Next report: Jan 19, 2027. Orders and cancellations are the data points to watch.
決算サマリー:需要の弱さと財務の強さが同居
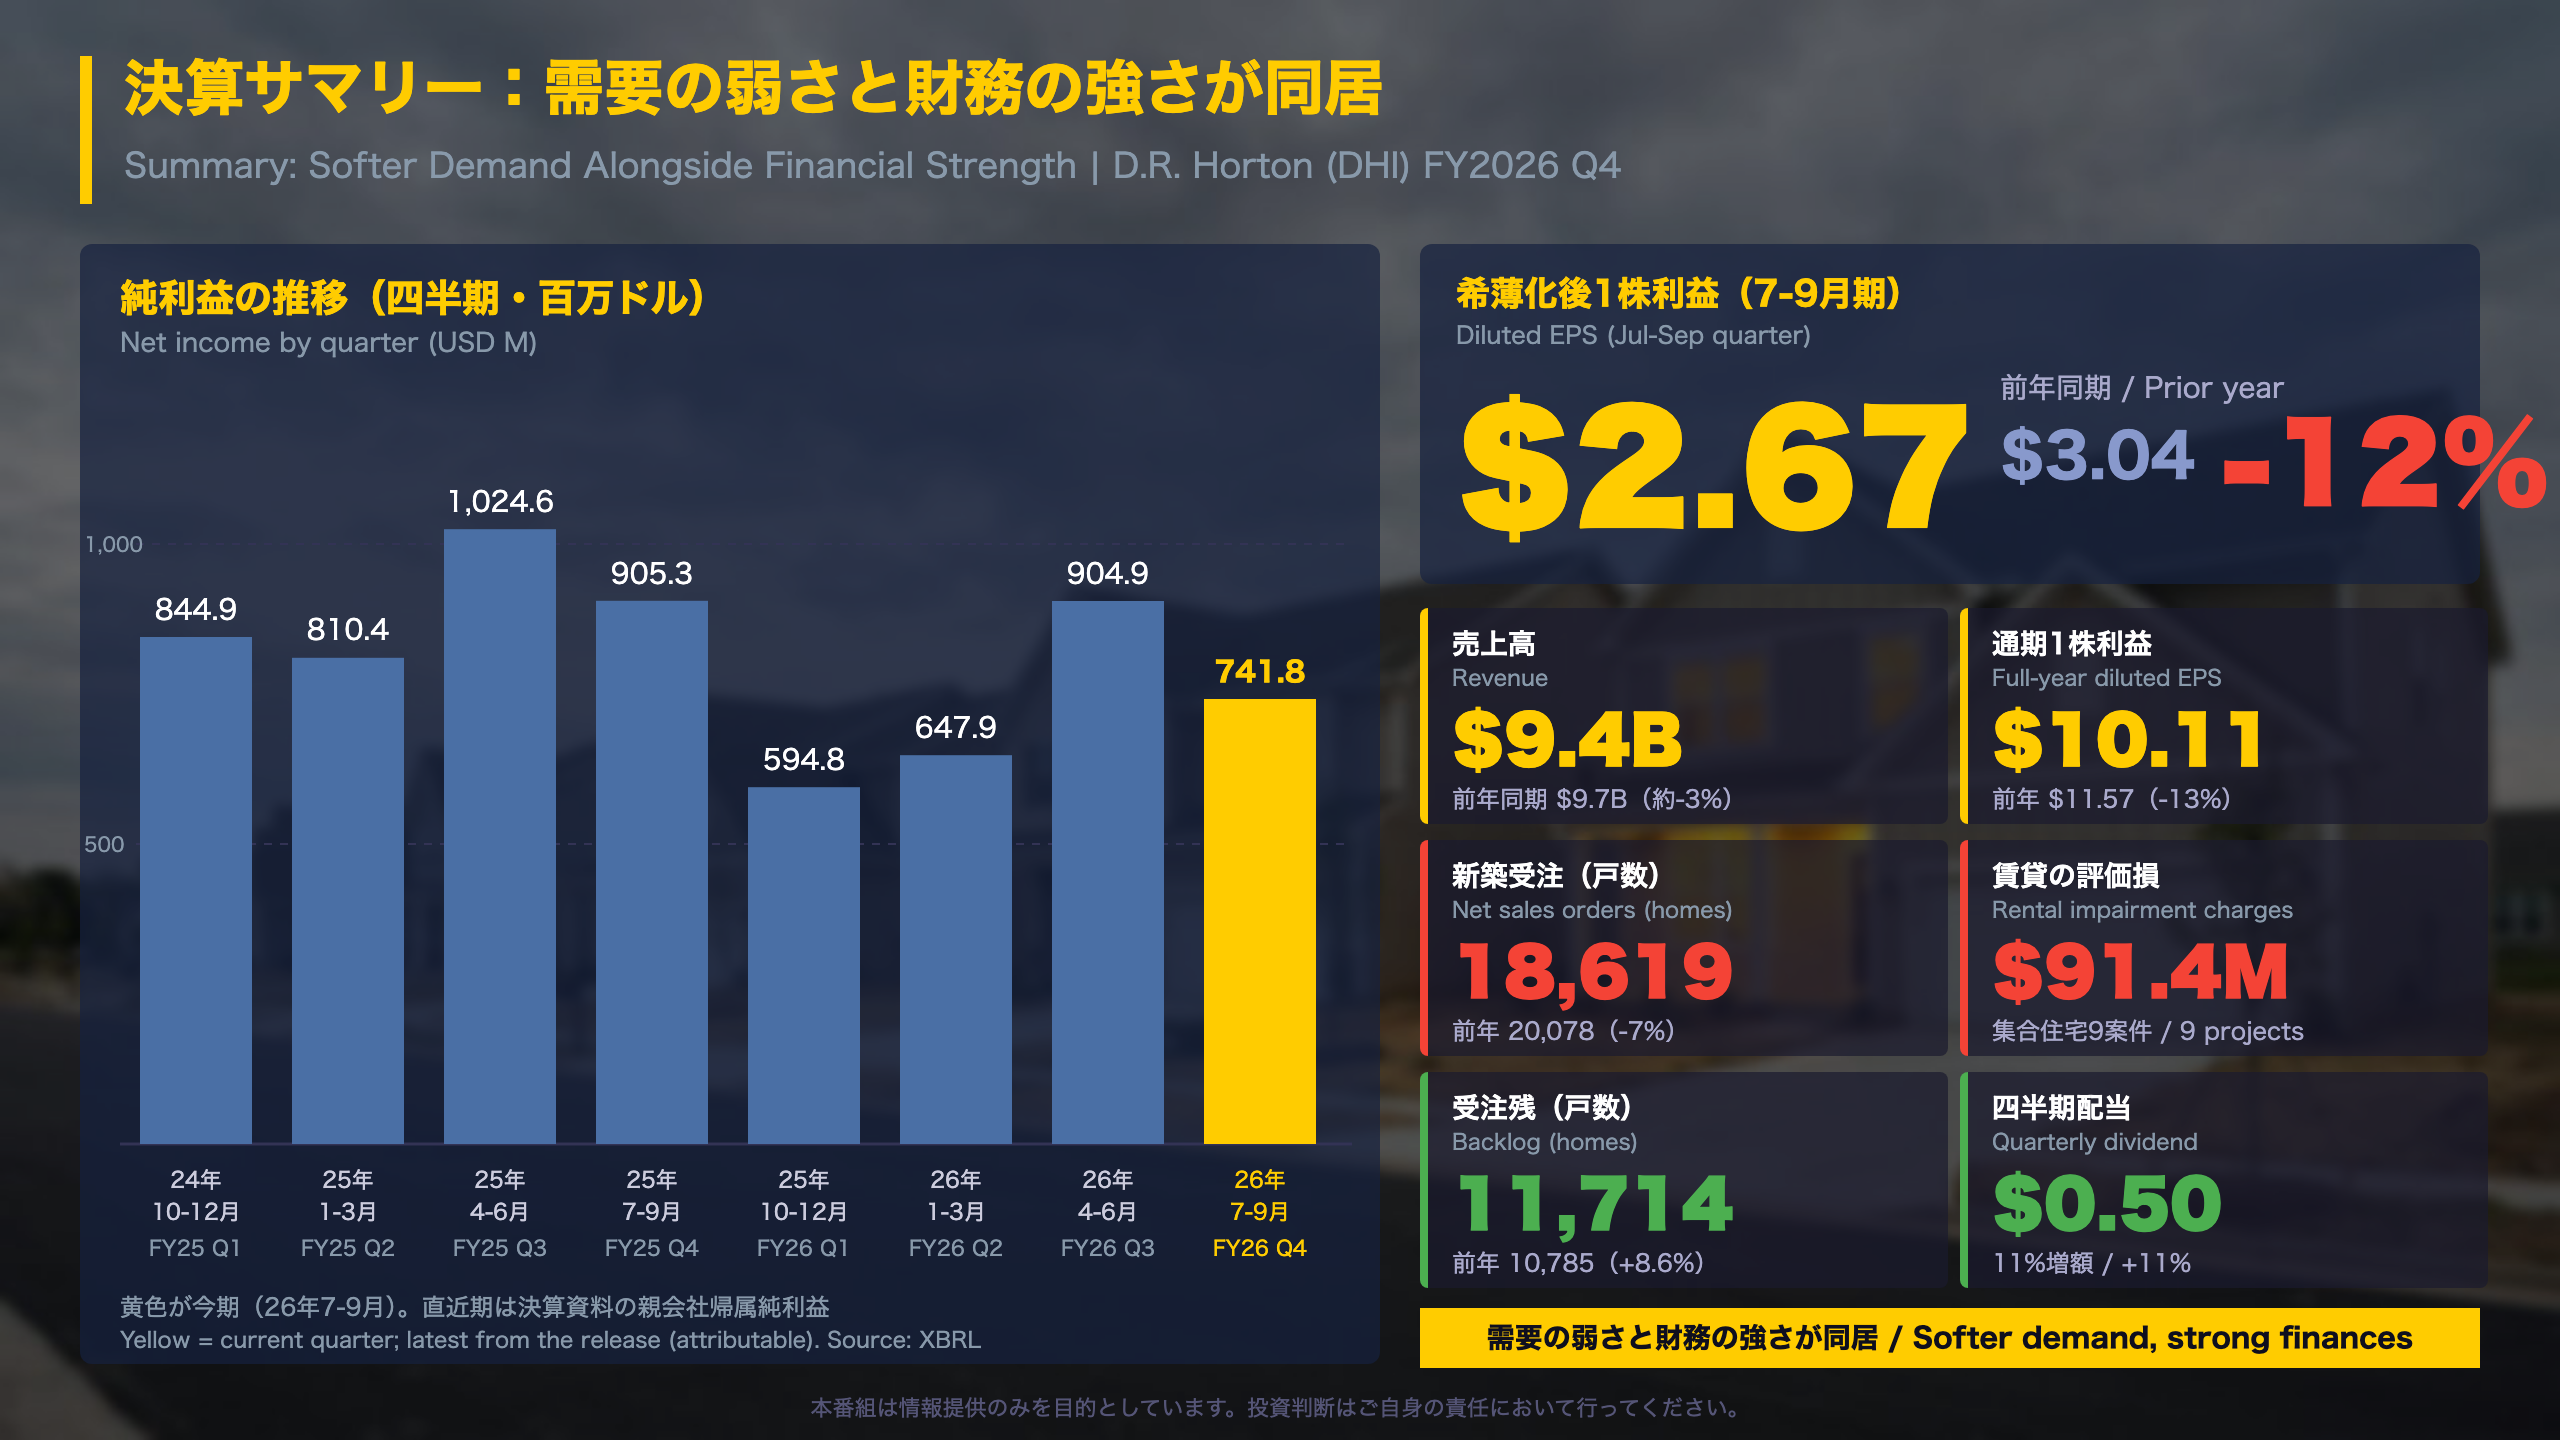
Context: who is D.R. Horton and what was reported?
D.R. Horton (NYSE: DHI) has been the largest US homebuilder by volume since 2002. Its fiscal year ends September 30, so this release covers the July-September 2026 quarter (fiscal Q4) and the full fiscal year. The figures come from the company’s 8-K Exhibit 99.1 dated October 29, 2026.
Headline numbers (vs. the prior-year period)
- Diluted EPS: $2.67 vs. $3.04 (-12%)
- Net income attributable: $741.8M (-18%)
- Revenue: $9.4B vs. $9.7B
- Fiscal-year EPS: $10.11 vs. $11.57 (-13%)
How to read it
For readers new to the sector, think of the group as a hybrid of a homebuilder, a land developer (Forestar), a rental business and a mortgage lender, so reported profit blends several cycles. US new-home demand is sensitive to mortgage rates and affordability; Executive Chairman David Auld said these factors “continued to pressure new home demand”.
Balance of evidence
Resilience: backlog rose year over year, debt to total capital is 20.8%, and the quarterly dividend was raised 11%.
Pressure: net orders fell 7%, the cancellation rate rose to 23%, and the rental segment booked impairments.
This note relies only on company-reported figures and does not reference consensus estimates. The next report is due January 19, 2027, before the US market opens.
深掘り1:新築受注と解約率
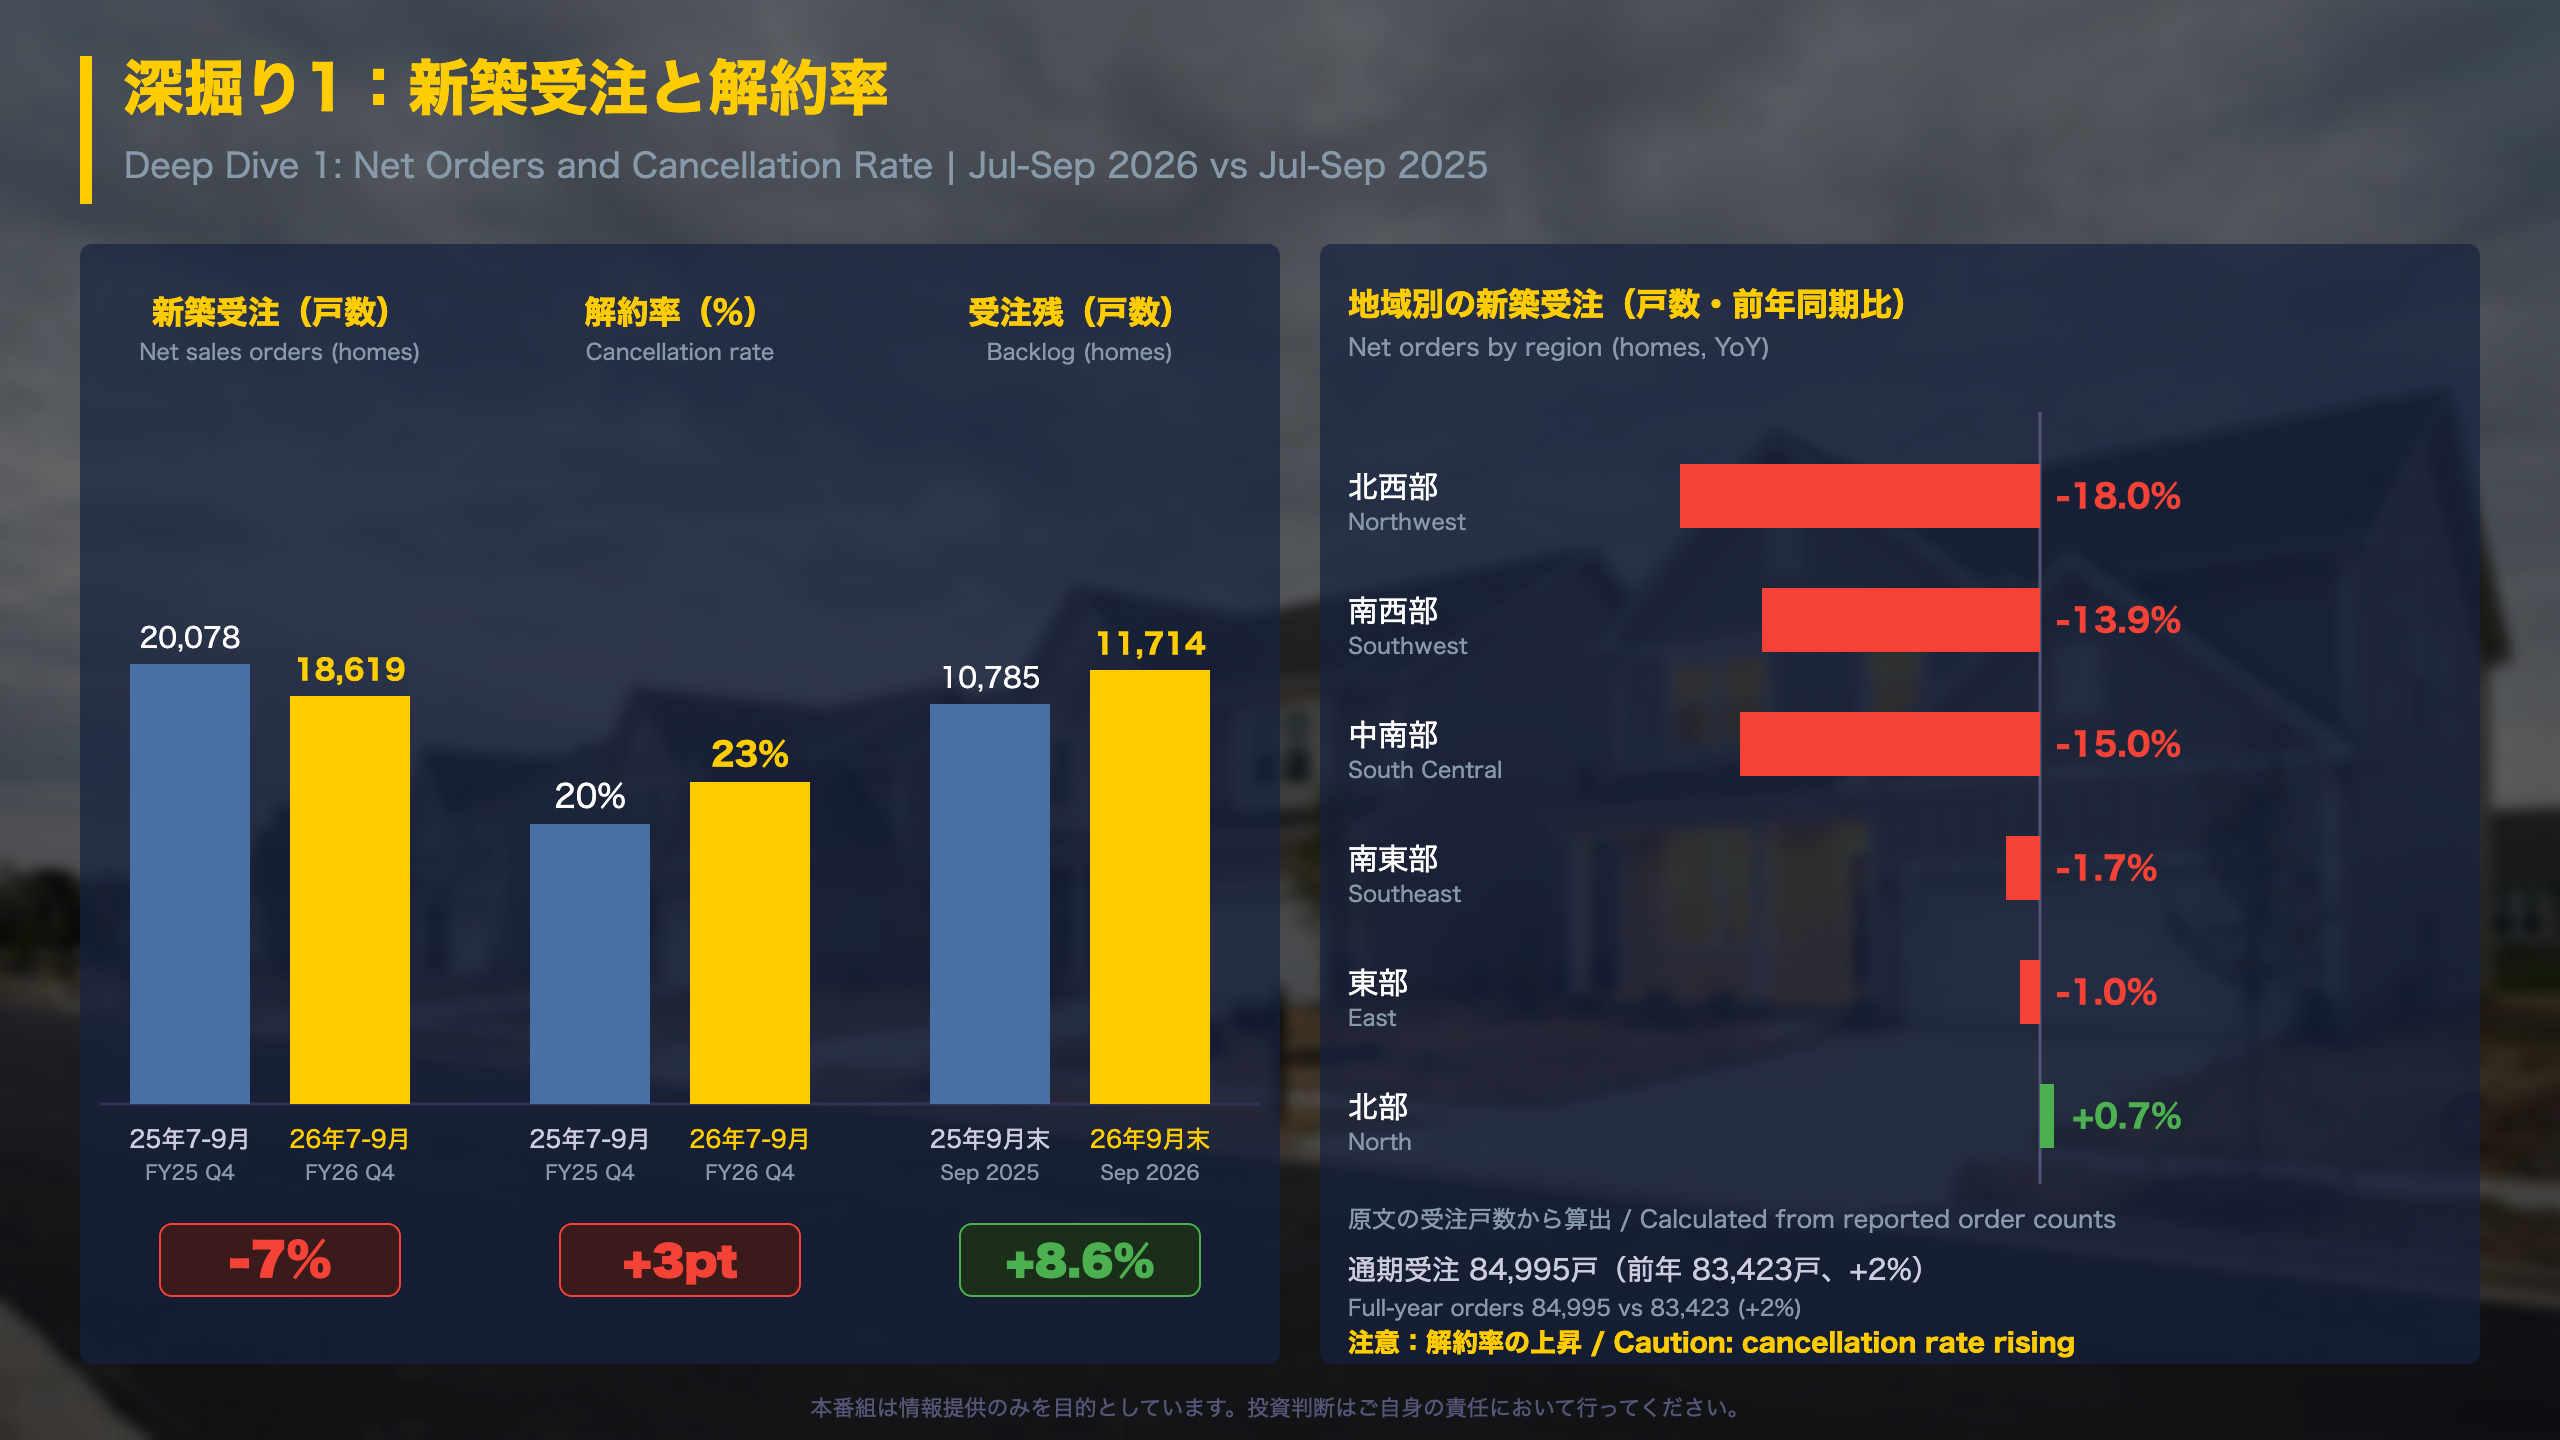
Why orders matter for a homebuilder
Net sales orders are the earliest hard signal of demand in the housing business: they show up months before revenue, when homes are closed and delivered. D.R. Horton reported 18,619 net orders in the July-September quarter, down 7% from 20,078, and 9% lower in value at $6.6B.
Regional detail (calculated from the release)
- Northwest: -18.0%; South Central: -15.0%; Southwest: -13.9%
- Southeast: -1.7%; East: -1.0%; North: +0.7%
Weakness is concentrated in the West and South Central regions, while the North was roughly flat. Backlog tells a similar story of dispersion: North 2,576 homes vs. 2,111, Northwest 343 vs. 476.
Cancellations
The cancellation rate (canceled orders divided by gross orders) rose to 23% from 20%. For the full year it was 19% vs. 18%. A higher rate means some signed contracts do not convert into closings, so backlog is a softer indicator than it looks.
Two readings
Resilient view: total backlog is 11,714 homes vs. 10,785, and full-year orders rose 2%.
Cautious view: quarterly orders fell, cancellations rose, and management expects elevated incentives in fiscal 2027, “the extent of which will depend on market conditions”. The size of the incentives is not disclosed.
US housing data are often compared with Japan’s housing starts, but D.R. Horton’s orders reflect only one builder’s mix of 128 markets across 38 states. Watch orders and cancellations on January 19, 2027.
深掘り2:減益の中身と来期の見通し
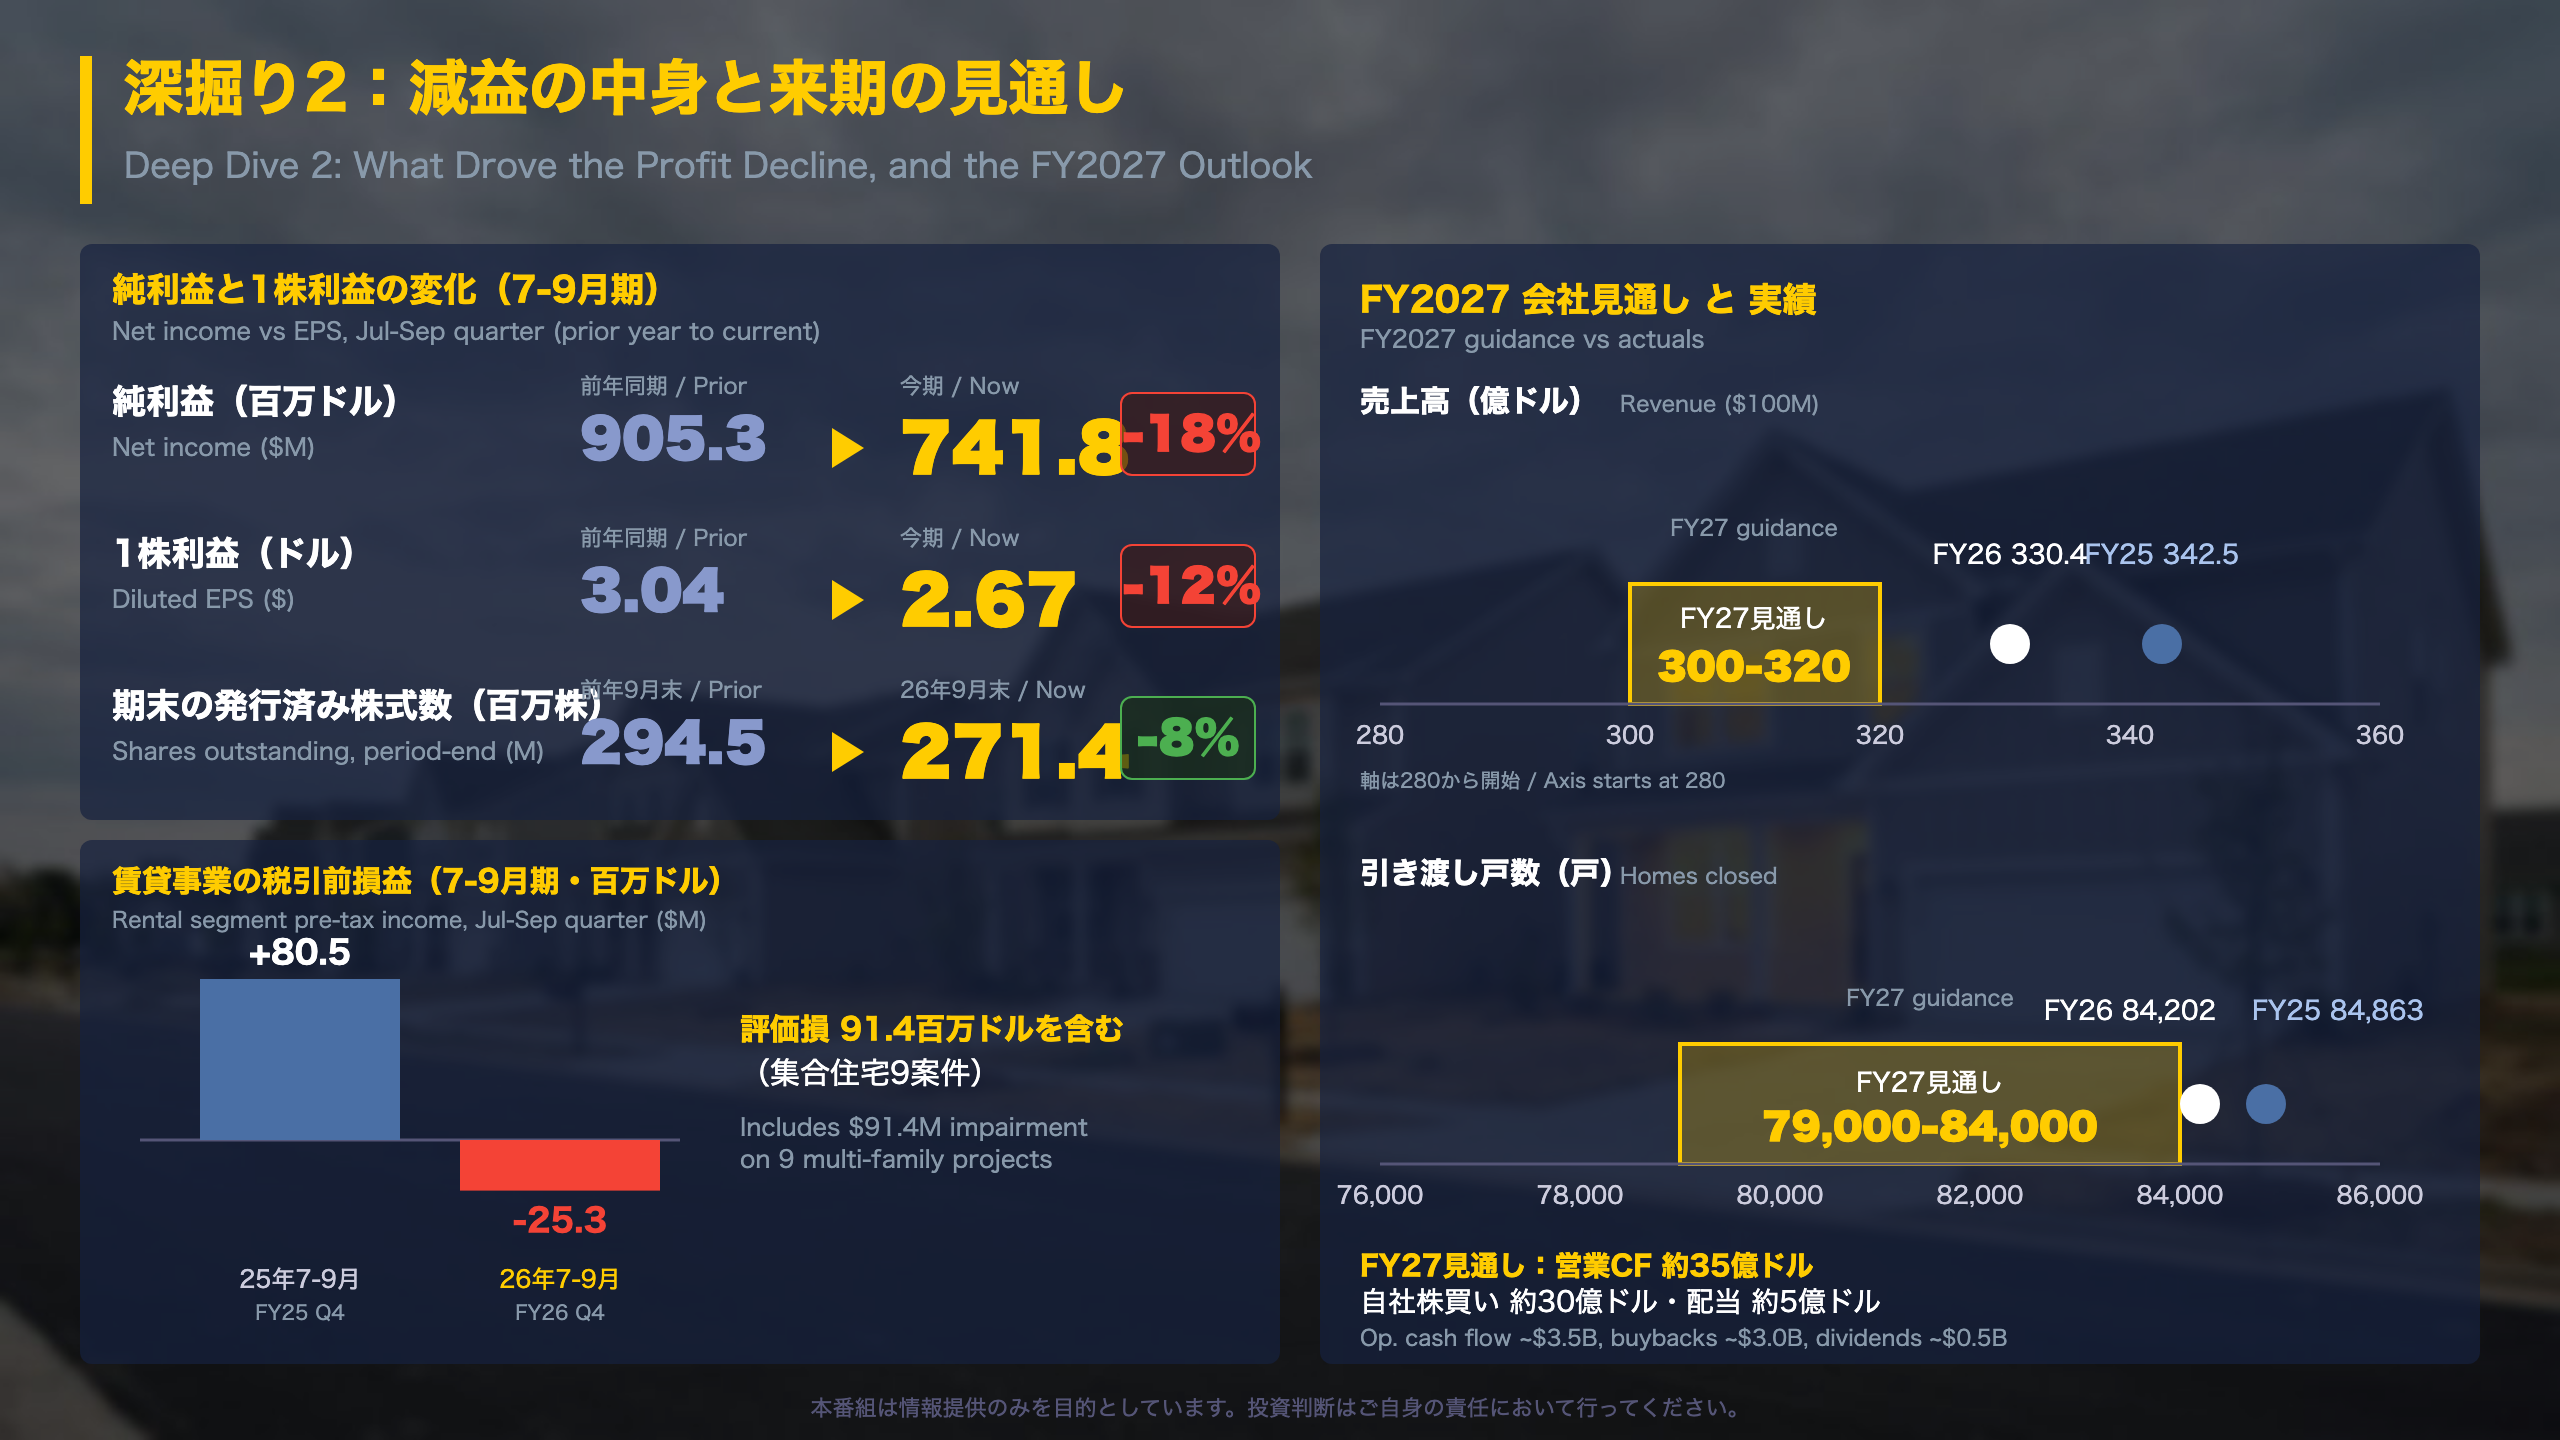
Reading the profit decline
Diluted EPS fell 12% while net income fell 18%. The gap is arithmetic: weighted diluted shares were 277.9M vs. 297.4M a year earlier, and period-end shares outstanding were 271.4M, down 8%, after the company repurchased 24.0M shares for $3.6B during the fiscal year.
Segment pre-tax income (Jul-Sep quarter)
- Homebuilding: $891.0M (margin 10.6%) vs. $1,000.7M
- Rental: -$25.3M vs. +$80.5M, including $91.4M of impairments on nine multi-family projects
- Forestar (lot developer): $78.6M vs. $113.1M
- Financial services: $78.2M (margin 35.7%) vs. $75.8M
A rental impairment is an accounting write-down of a project’s carrying value; it is non-cash in the quarter it is booked, though it reflects management’s view of recoverable value.
Fiscal 2027 guidance (first guidance of the year)
| Item | Guidance |
|---|---|
| Revenue | $30.0-32.0B (FY2026: $33.0B) |
| Homes closed | 79,000-84,000 (FY2026: 84,202) |
| Tax rate | ~25.5% |
| Operating cash flow | ~$3.5B |
| Buybacks / dividends | ~$3.0B / ~$0.5B |
Because this is the initial guide, the release provides no prior guidance to compare against.
Two readings
Share count reduction supports per-share earnings, but the planned buyback ($3.0B) is smaller than FY2026’s $3.6B, so that cushion may be thinner. Conversely, cash generation is guided flat at about $3.5B and the dividend was raised 11% to $0.50 per quarter.
質疑で深める:配当・在庫・次回の注目点
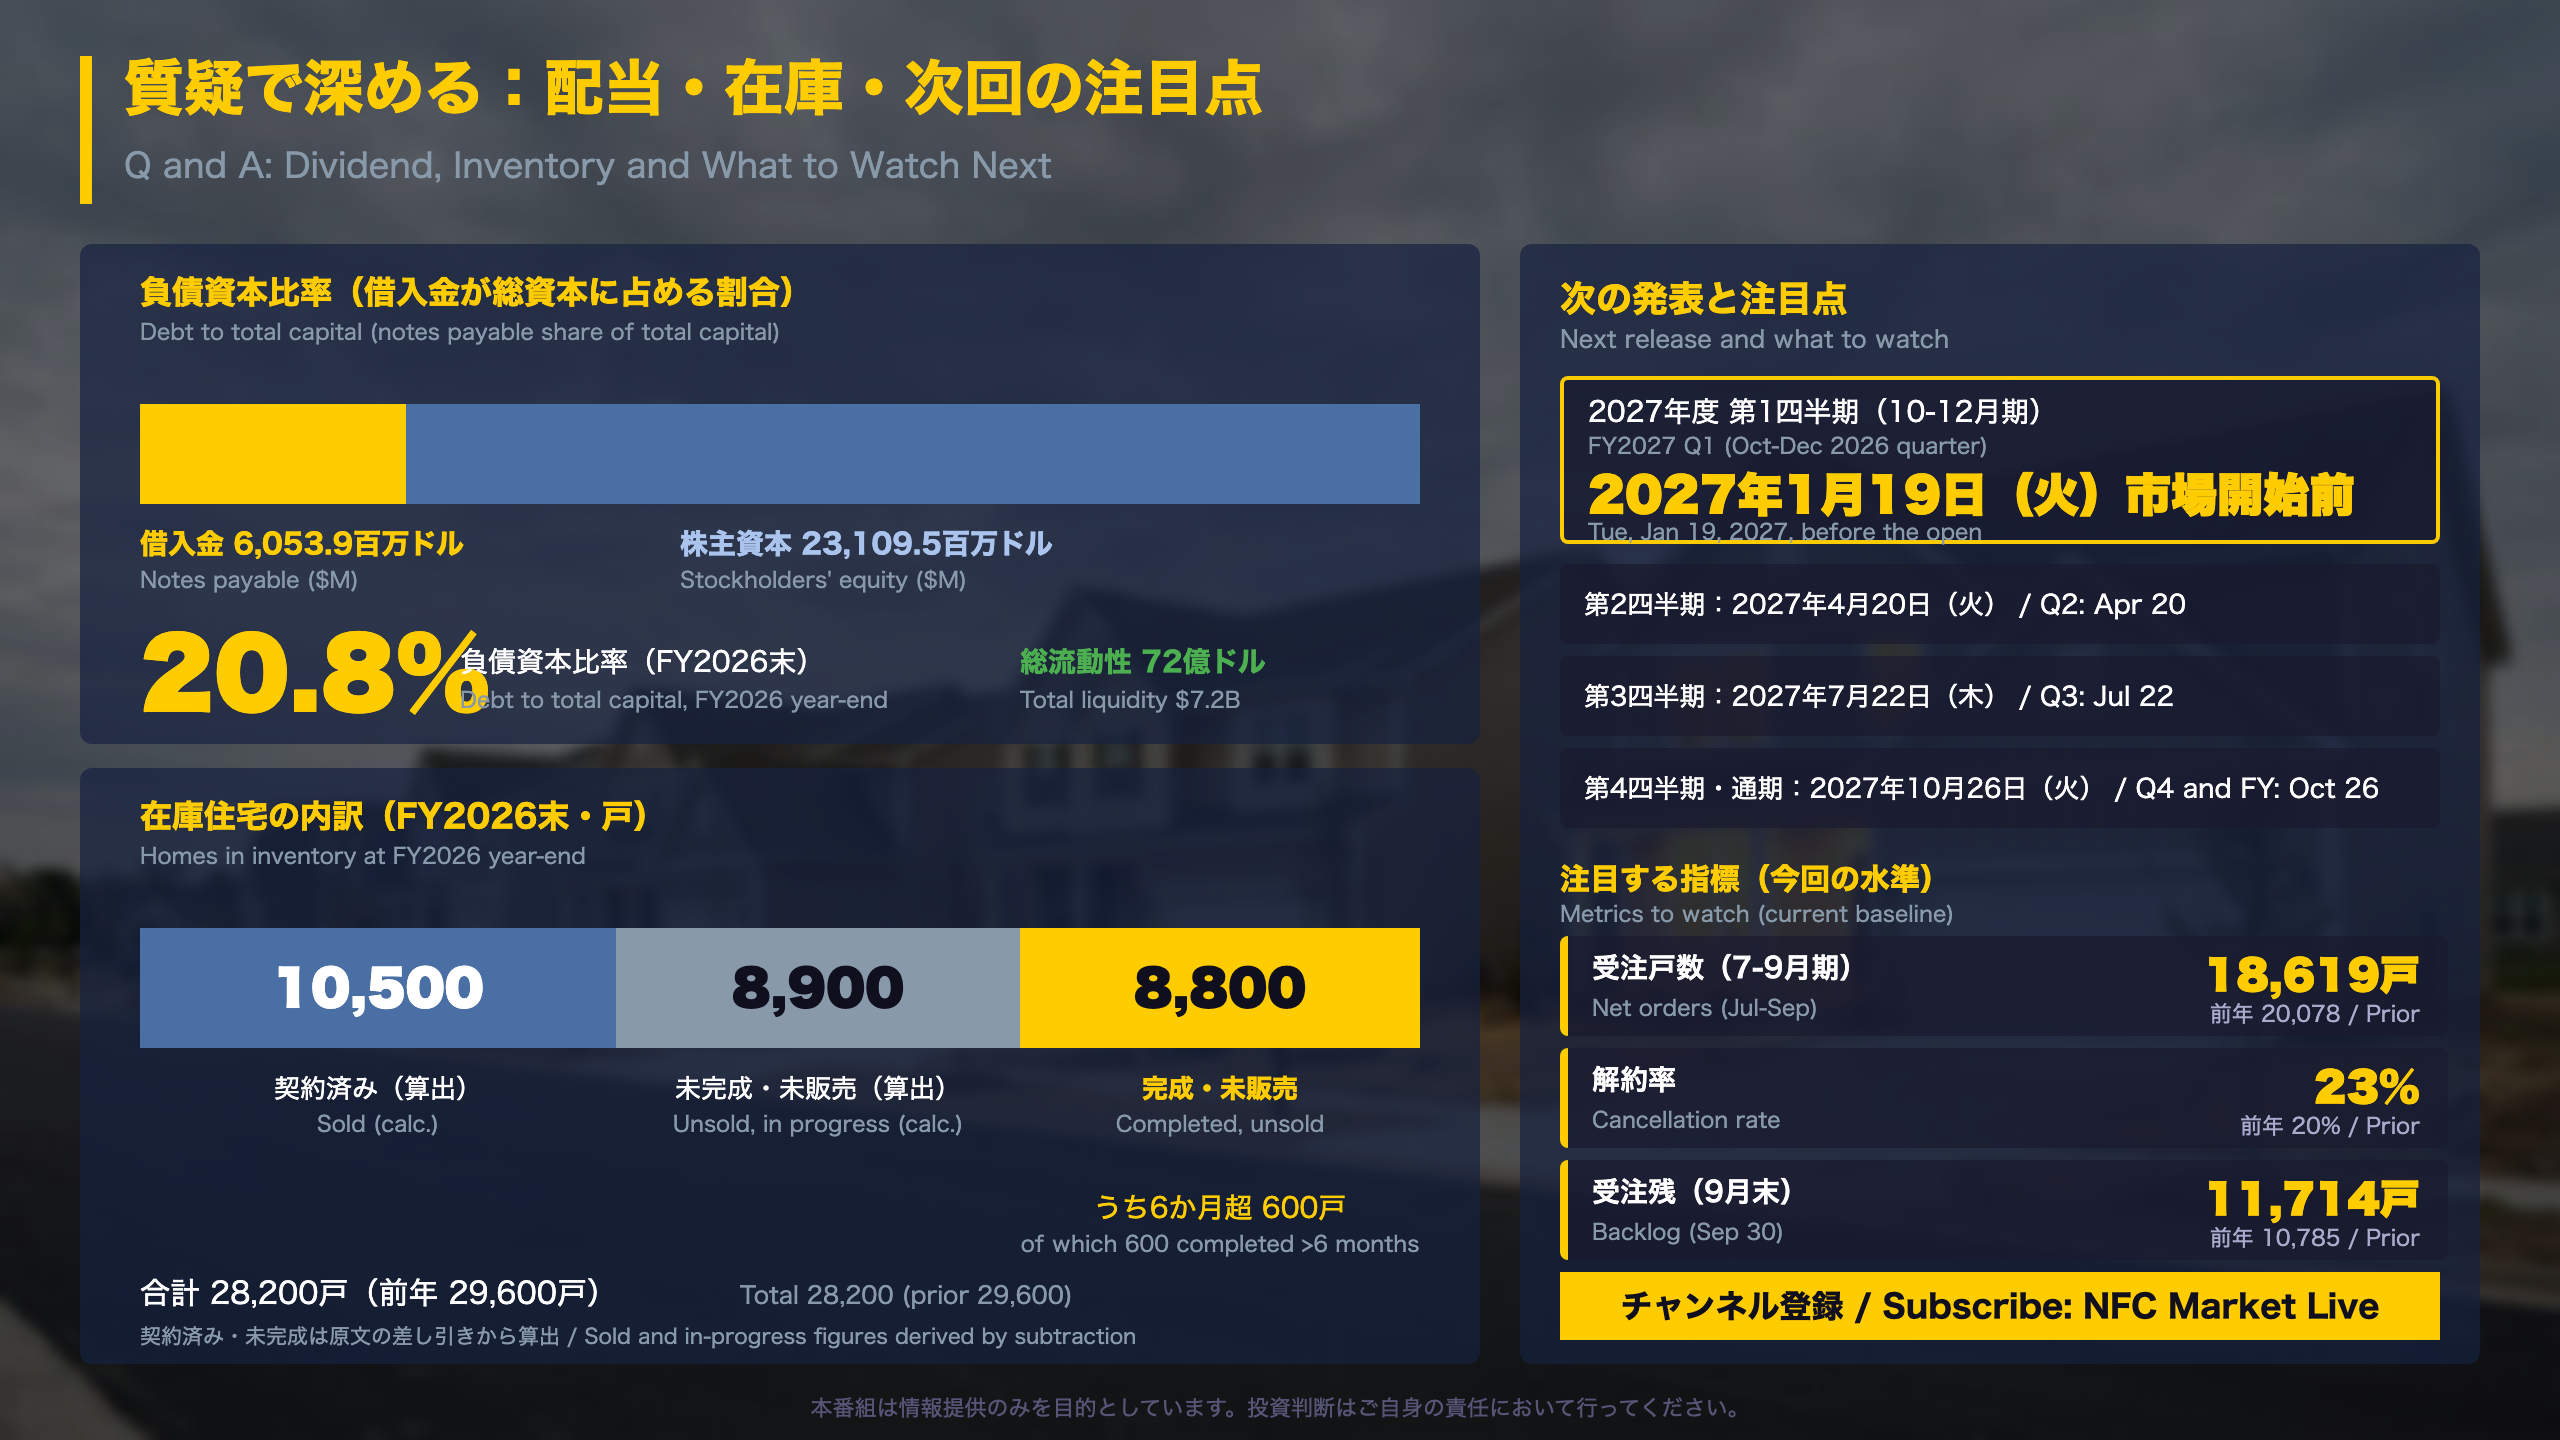
Balance sheet strength and what to watch next
| Item | Sep 30, 2026 | Sep 30, 2025 |
|---|---|---|
| Cash and equivalents | $2,060.4M | $2,985.4M |
| Notes payable | $6,053.9M | $5,965.5M |
| Stockholders’ equity | $23,109.5M | $24,190.4M |
| Total inventory | $25,065.8M | $25,287.3M |
Cash fell, but total liquidity was $7.2B at year-end. The company repaid $600M of 1.3% senior notes at maturity in October 2026 and says it has no other senior note maturities in fiscal 2027. Debt to total capital (notes payable divided by equity plus notes payable) is 20.8%.
Inventory mix
The release gives 28,200 homes in inventory (vs. 29,600), of which 17,700 are unsold and 8,800 of those are completed, including 600 completed for more than six months. By subtraction, about 10,500 are already sold and about 8,900 are unsold and still in progress. Management says it is adjusting incentives, pricing and starts community by community.
Capital returns
The company returned $4.1B in fiscal 2026 through buybacks and dividends, and over five years says it returned all $14.0B of operating cash flow. The Board raised the quarterly dividend 11% to $0.50, making fiscal 2027 the thirteenth consecutive year of dividend growth.
Calendar and baselines for the next print
Q1 FY2027 is due January 19, 2027, before the open (call at 8:30 a.m. ET). Baselines: orders 18,619 homes, cancellation rate 23%, backlog 11,714 homes. Later dates: April 20, July 22 and October 26, 2027.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.