📺 Watch the Full Video Analysis
This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-11-03 06:31 JST)
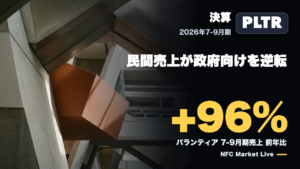
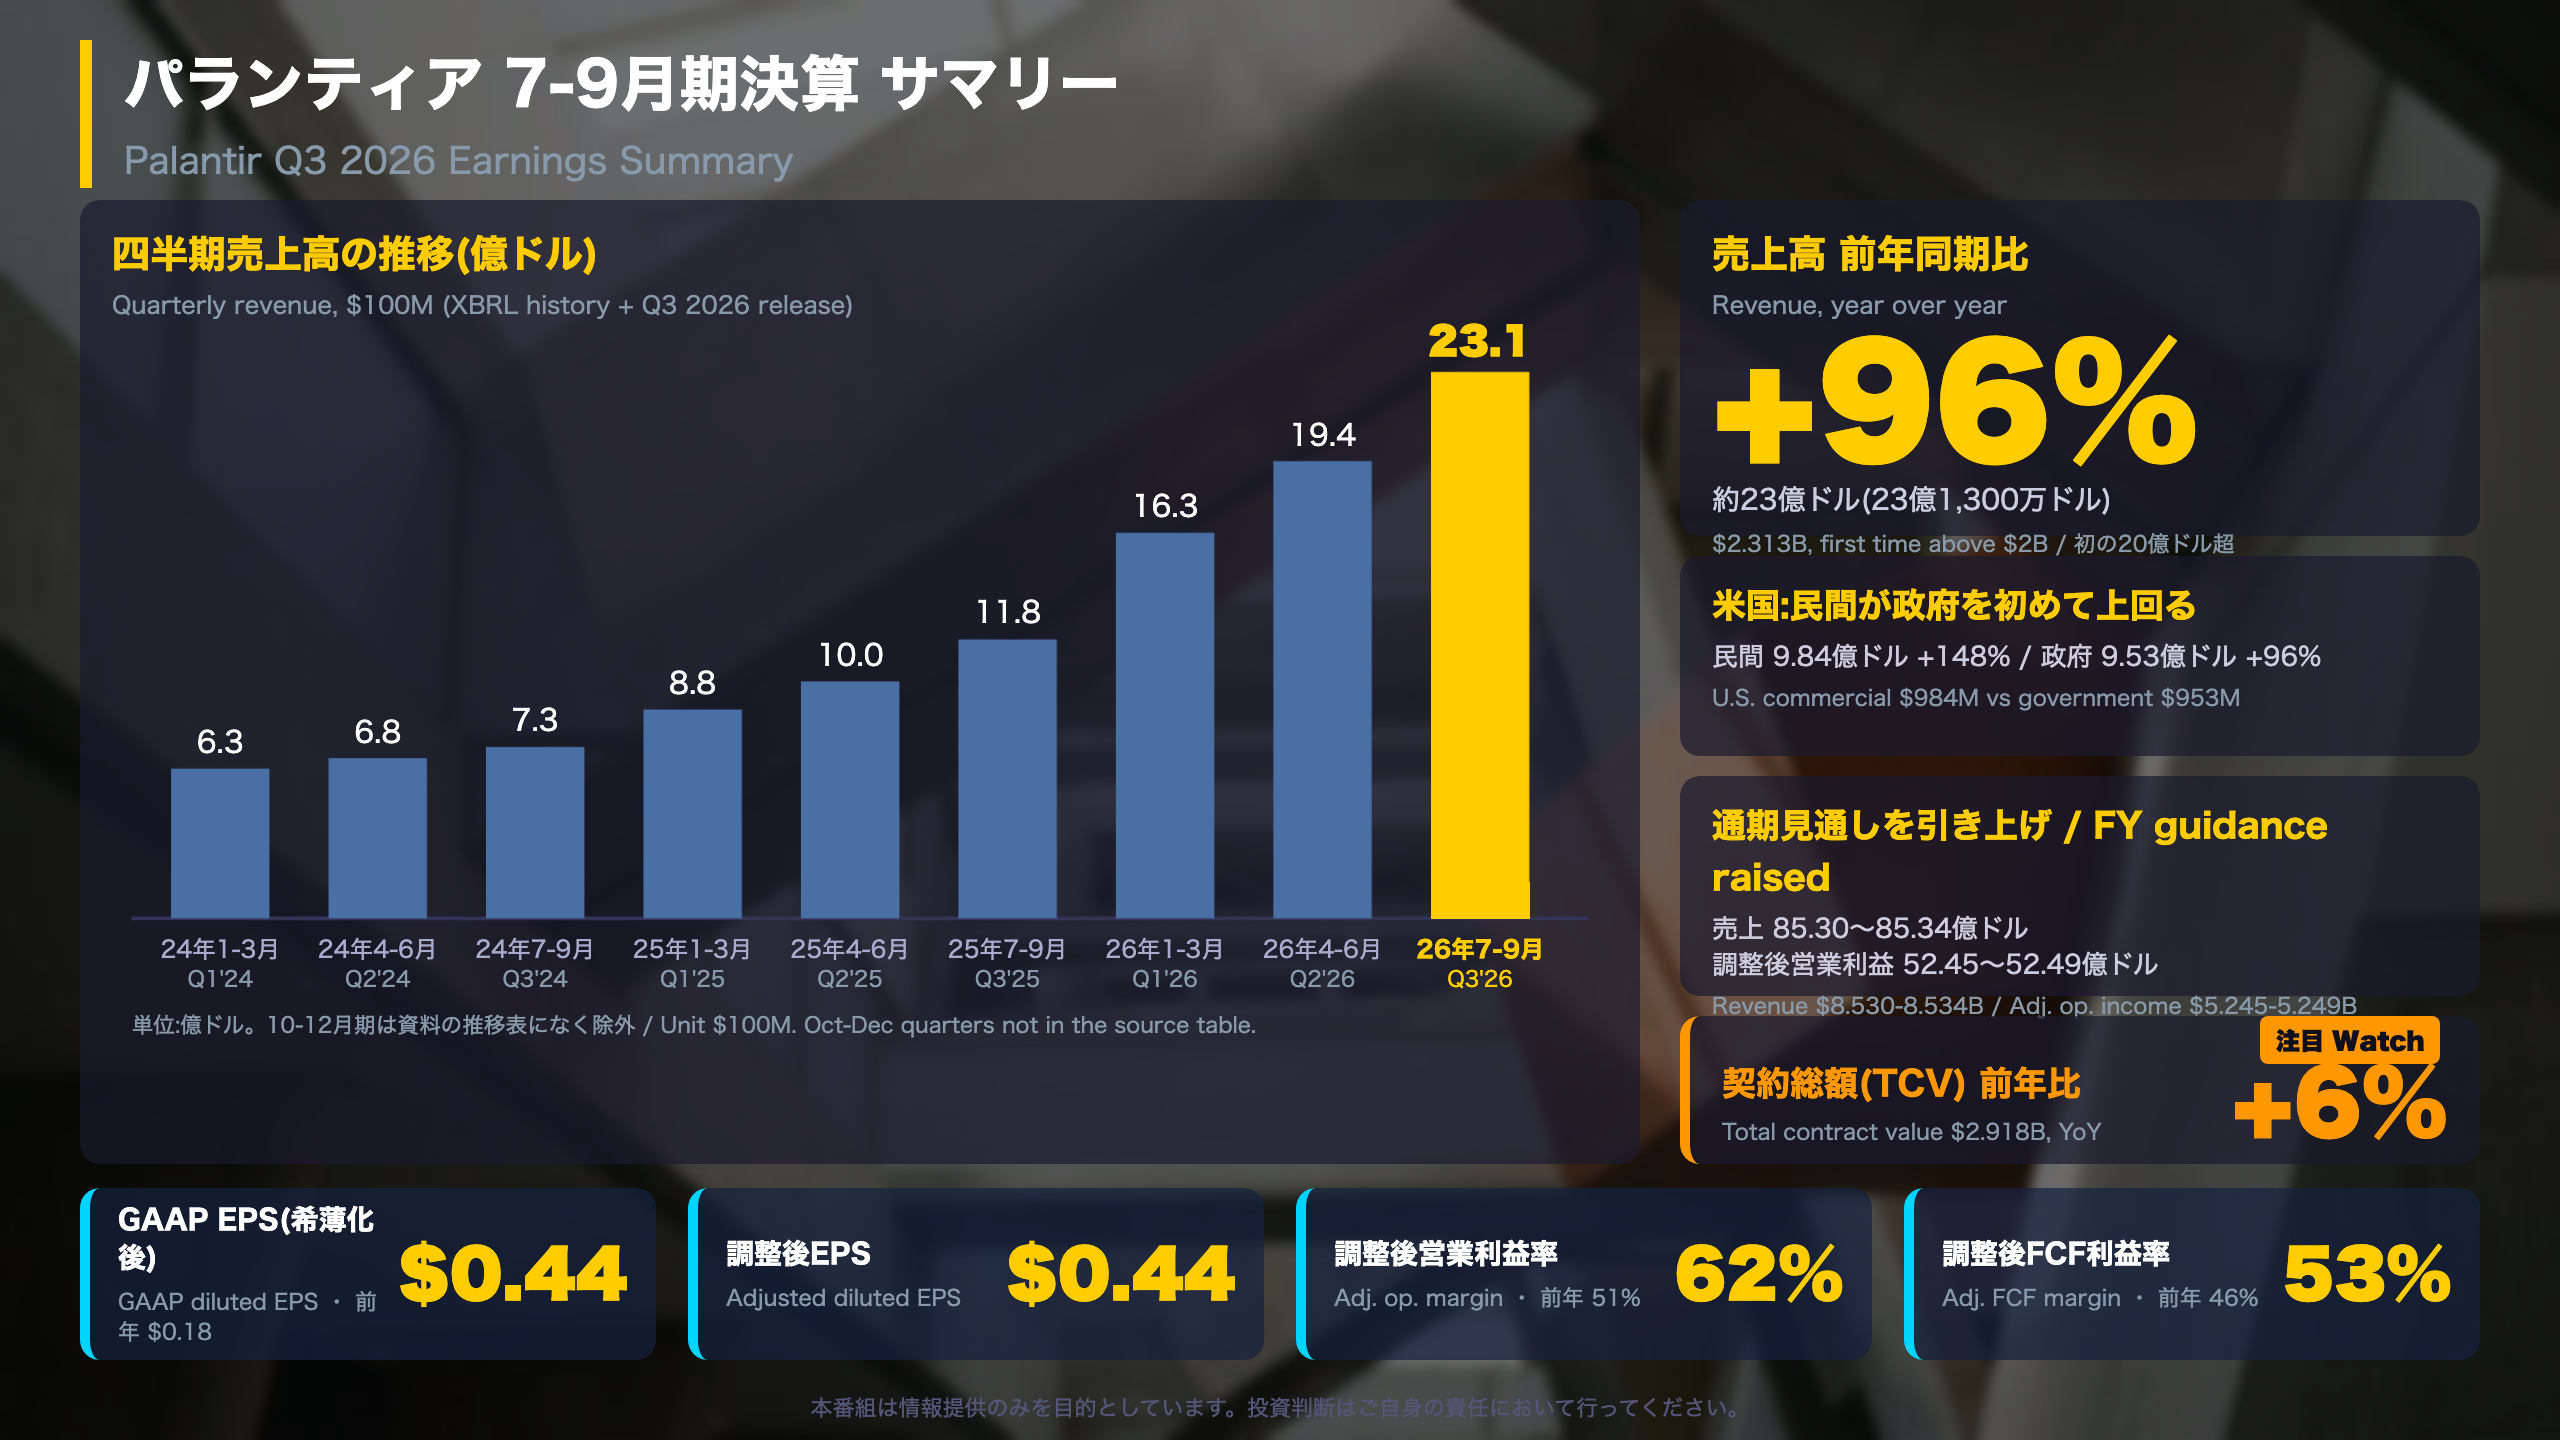
📊 Palantir (PLTR) reported Q3 2026 results on Nov 2. Revenue was $2.313B, up 96% year over year, topping $2B in a quarter for the first time.
📈 U.S. commercial revenue rose 148% to $984M, passing U.S. government revenue ($953M, +96%) for the first time. GAAP operating margin was 47%, adjusted 62%. Full-year revenue guidance was raised to $8.530-8.534B.
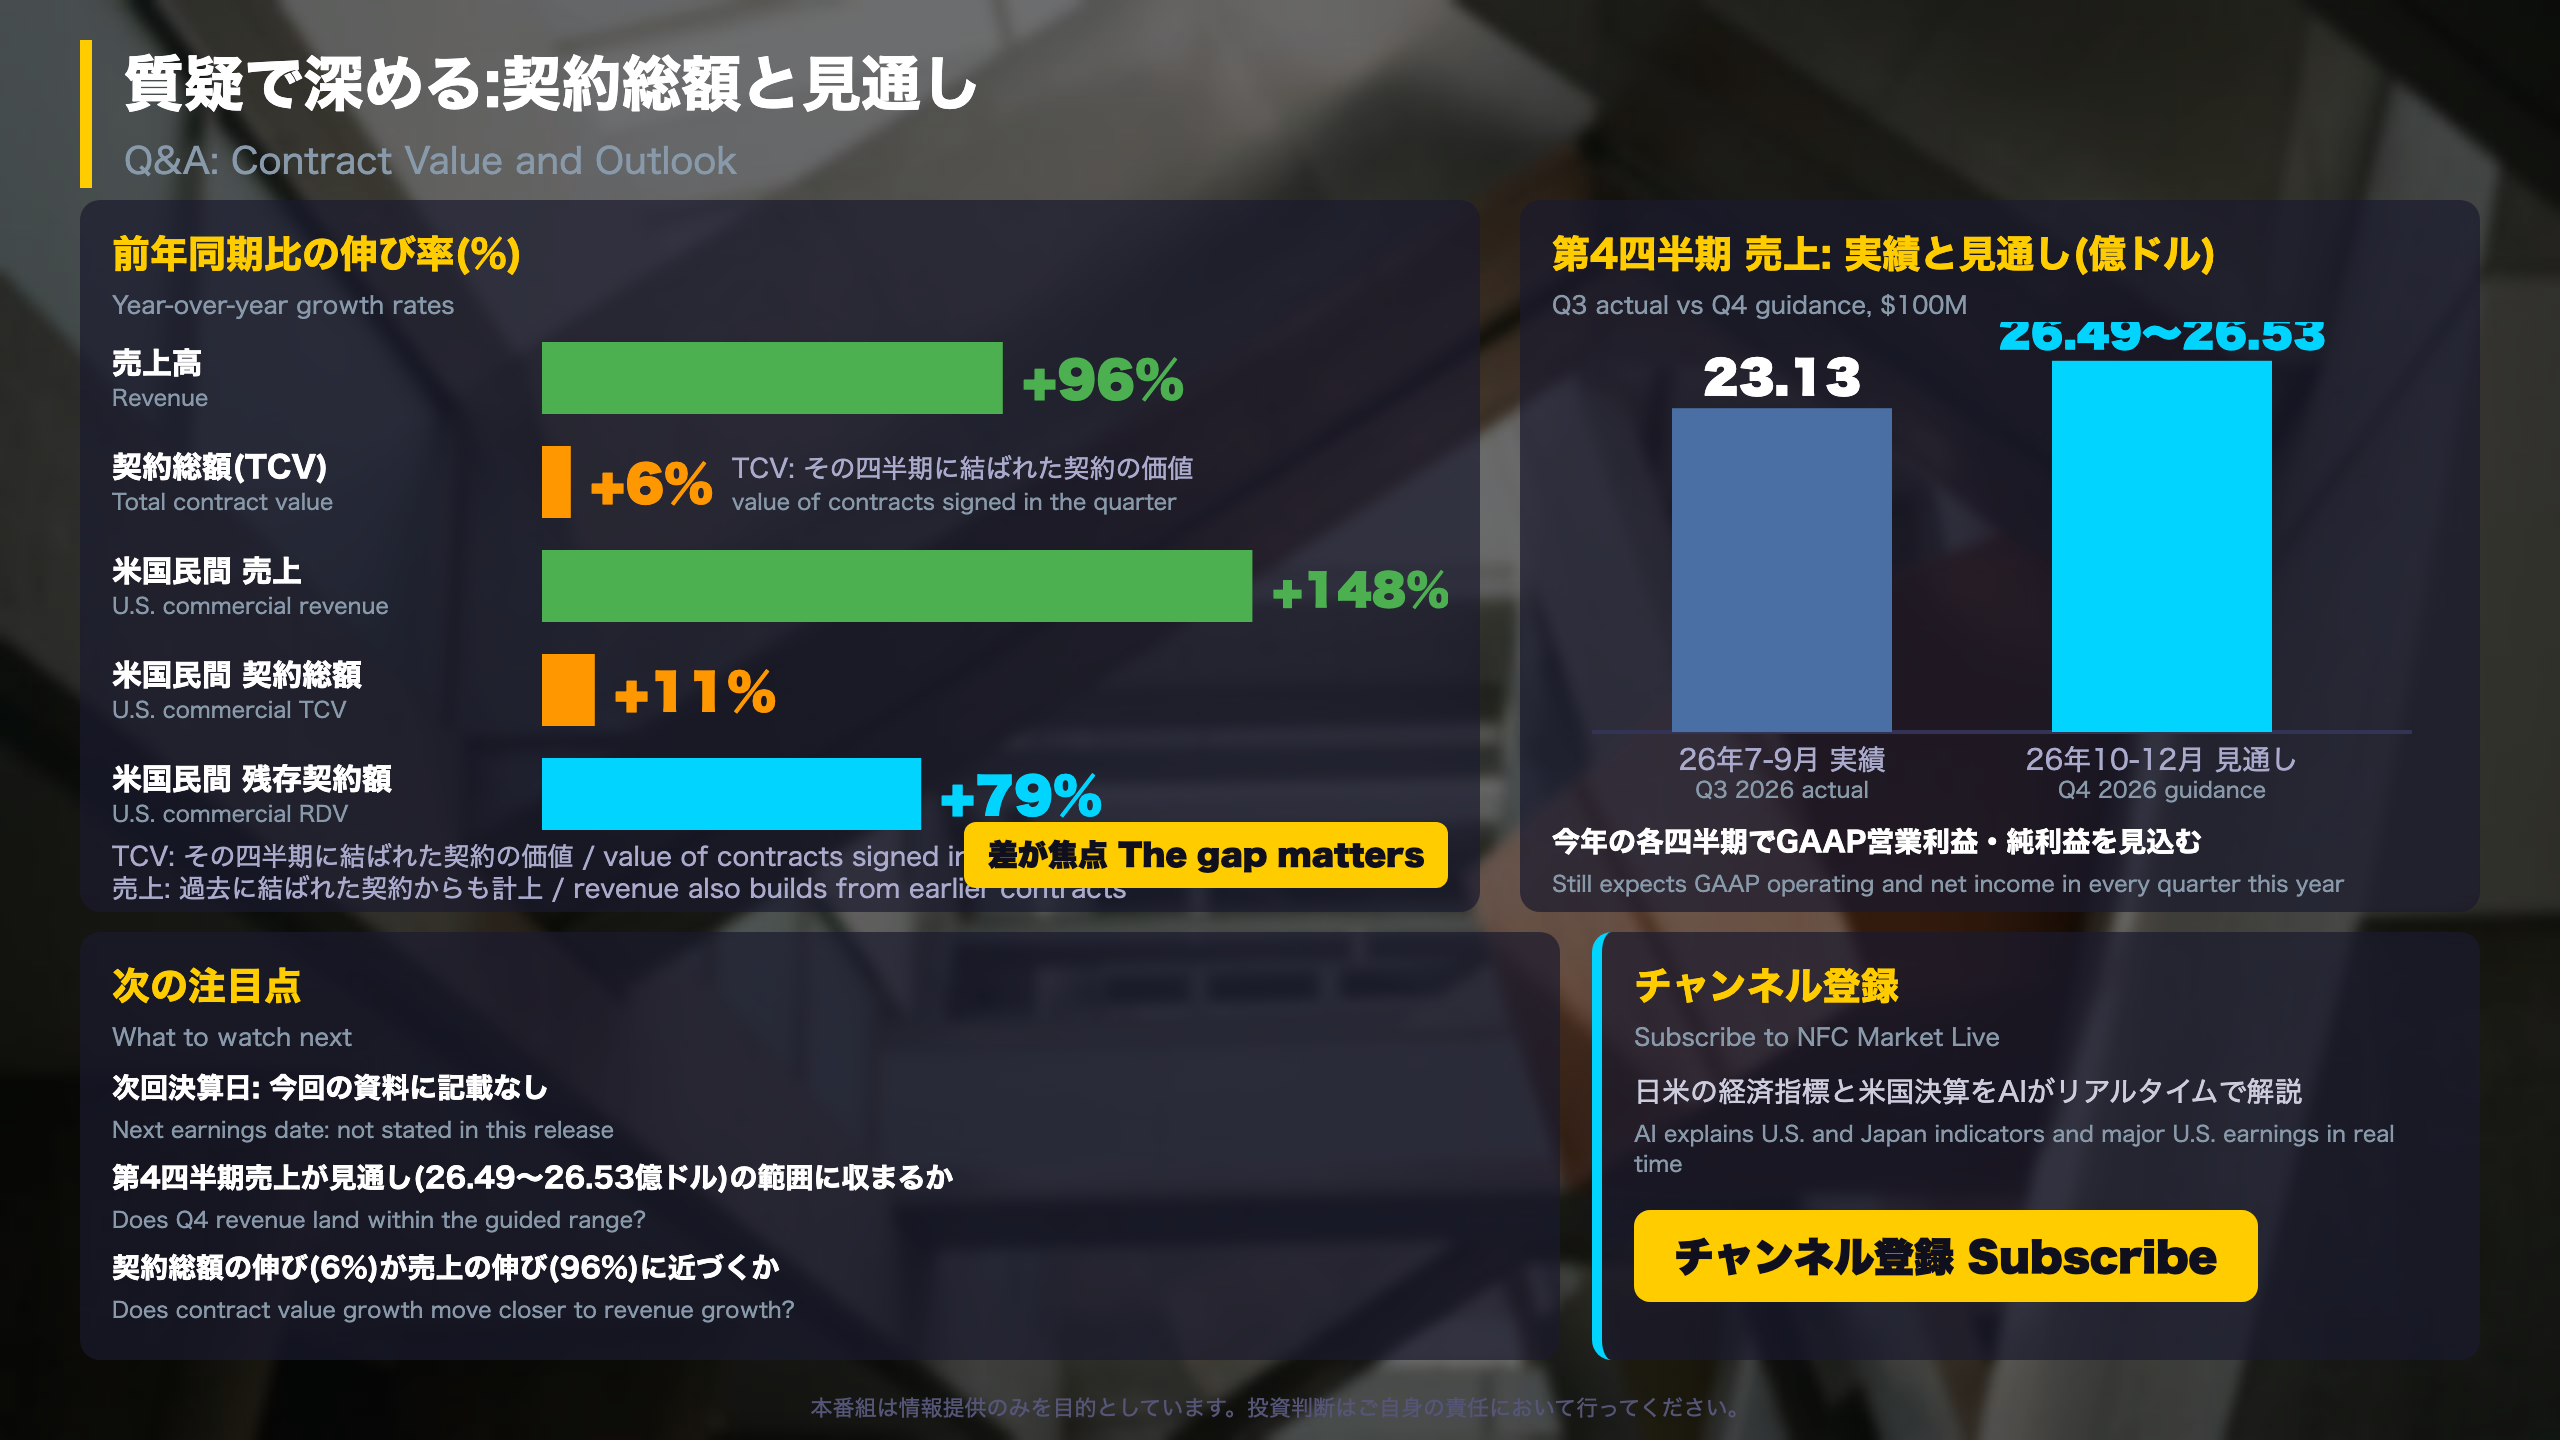
⚠️ Total contract value rose only 6% to $2.918B, a gap versus revenue growth.
💡 Next: whether Q4 revenue lands near the roughly $2.65B outlook, and whether contract value growth moves closer to revenue growth.
パランティア 7-9月期決算サマリー
Palantir Q3 2026 at a glance
Palantir Technologies (NASDAQ: PLTR) reported third-quarter 2026 results on November 2. It is a U.S. software company known for data-integration and AI platforms (Foundry, Ontology and AIP) sold to governments and large corporations. It is widely followed by Japanese investors as one of the fastest-growing names in U.S. enterprise software.
The numbers
- Revenue: $2.313B, up 96% year over year (Q3 2025: $1.181B). This is the first quarter above $2B.
- GAAP operating income: $1.085B (47% margin) vs $393M a year earlier.
- GAAP diluted EPS: $0.44 vs $0.18. Adjusted diluted EPS is also $0.44.
- Rule of 40: 158%, which is 96% revenue growth plus a 62% adjusted operating margin. The rule of thumb treats 40 as a healthy level.
What the release does not say
The release contains no analyst-consensus comparison, and we do not use one. Nine-month revenue is $5.881B, so full-year guidance of $8.530-8.534B implies roughly $2.65B in Q4. Management also states that most contracts can be terminated for convenience.
Two readings
The constructive view: growth, margins and cash conversion (adjusted free cash flow margin of 53%) are improving together. The cautious view: bookings are growing more slowly than revenue, with total contract value up just 6%. One quarter cannot settle which view dominates.
What to watch
The Q4 report, and the 10-Q for the quarter ended September 30, 2026. The release does not state the date of the next earnings announcement.
米国民間売上が政府向けを初めて上回る
U.S. revenue split: commercial vs government
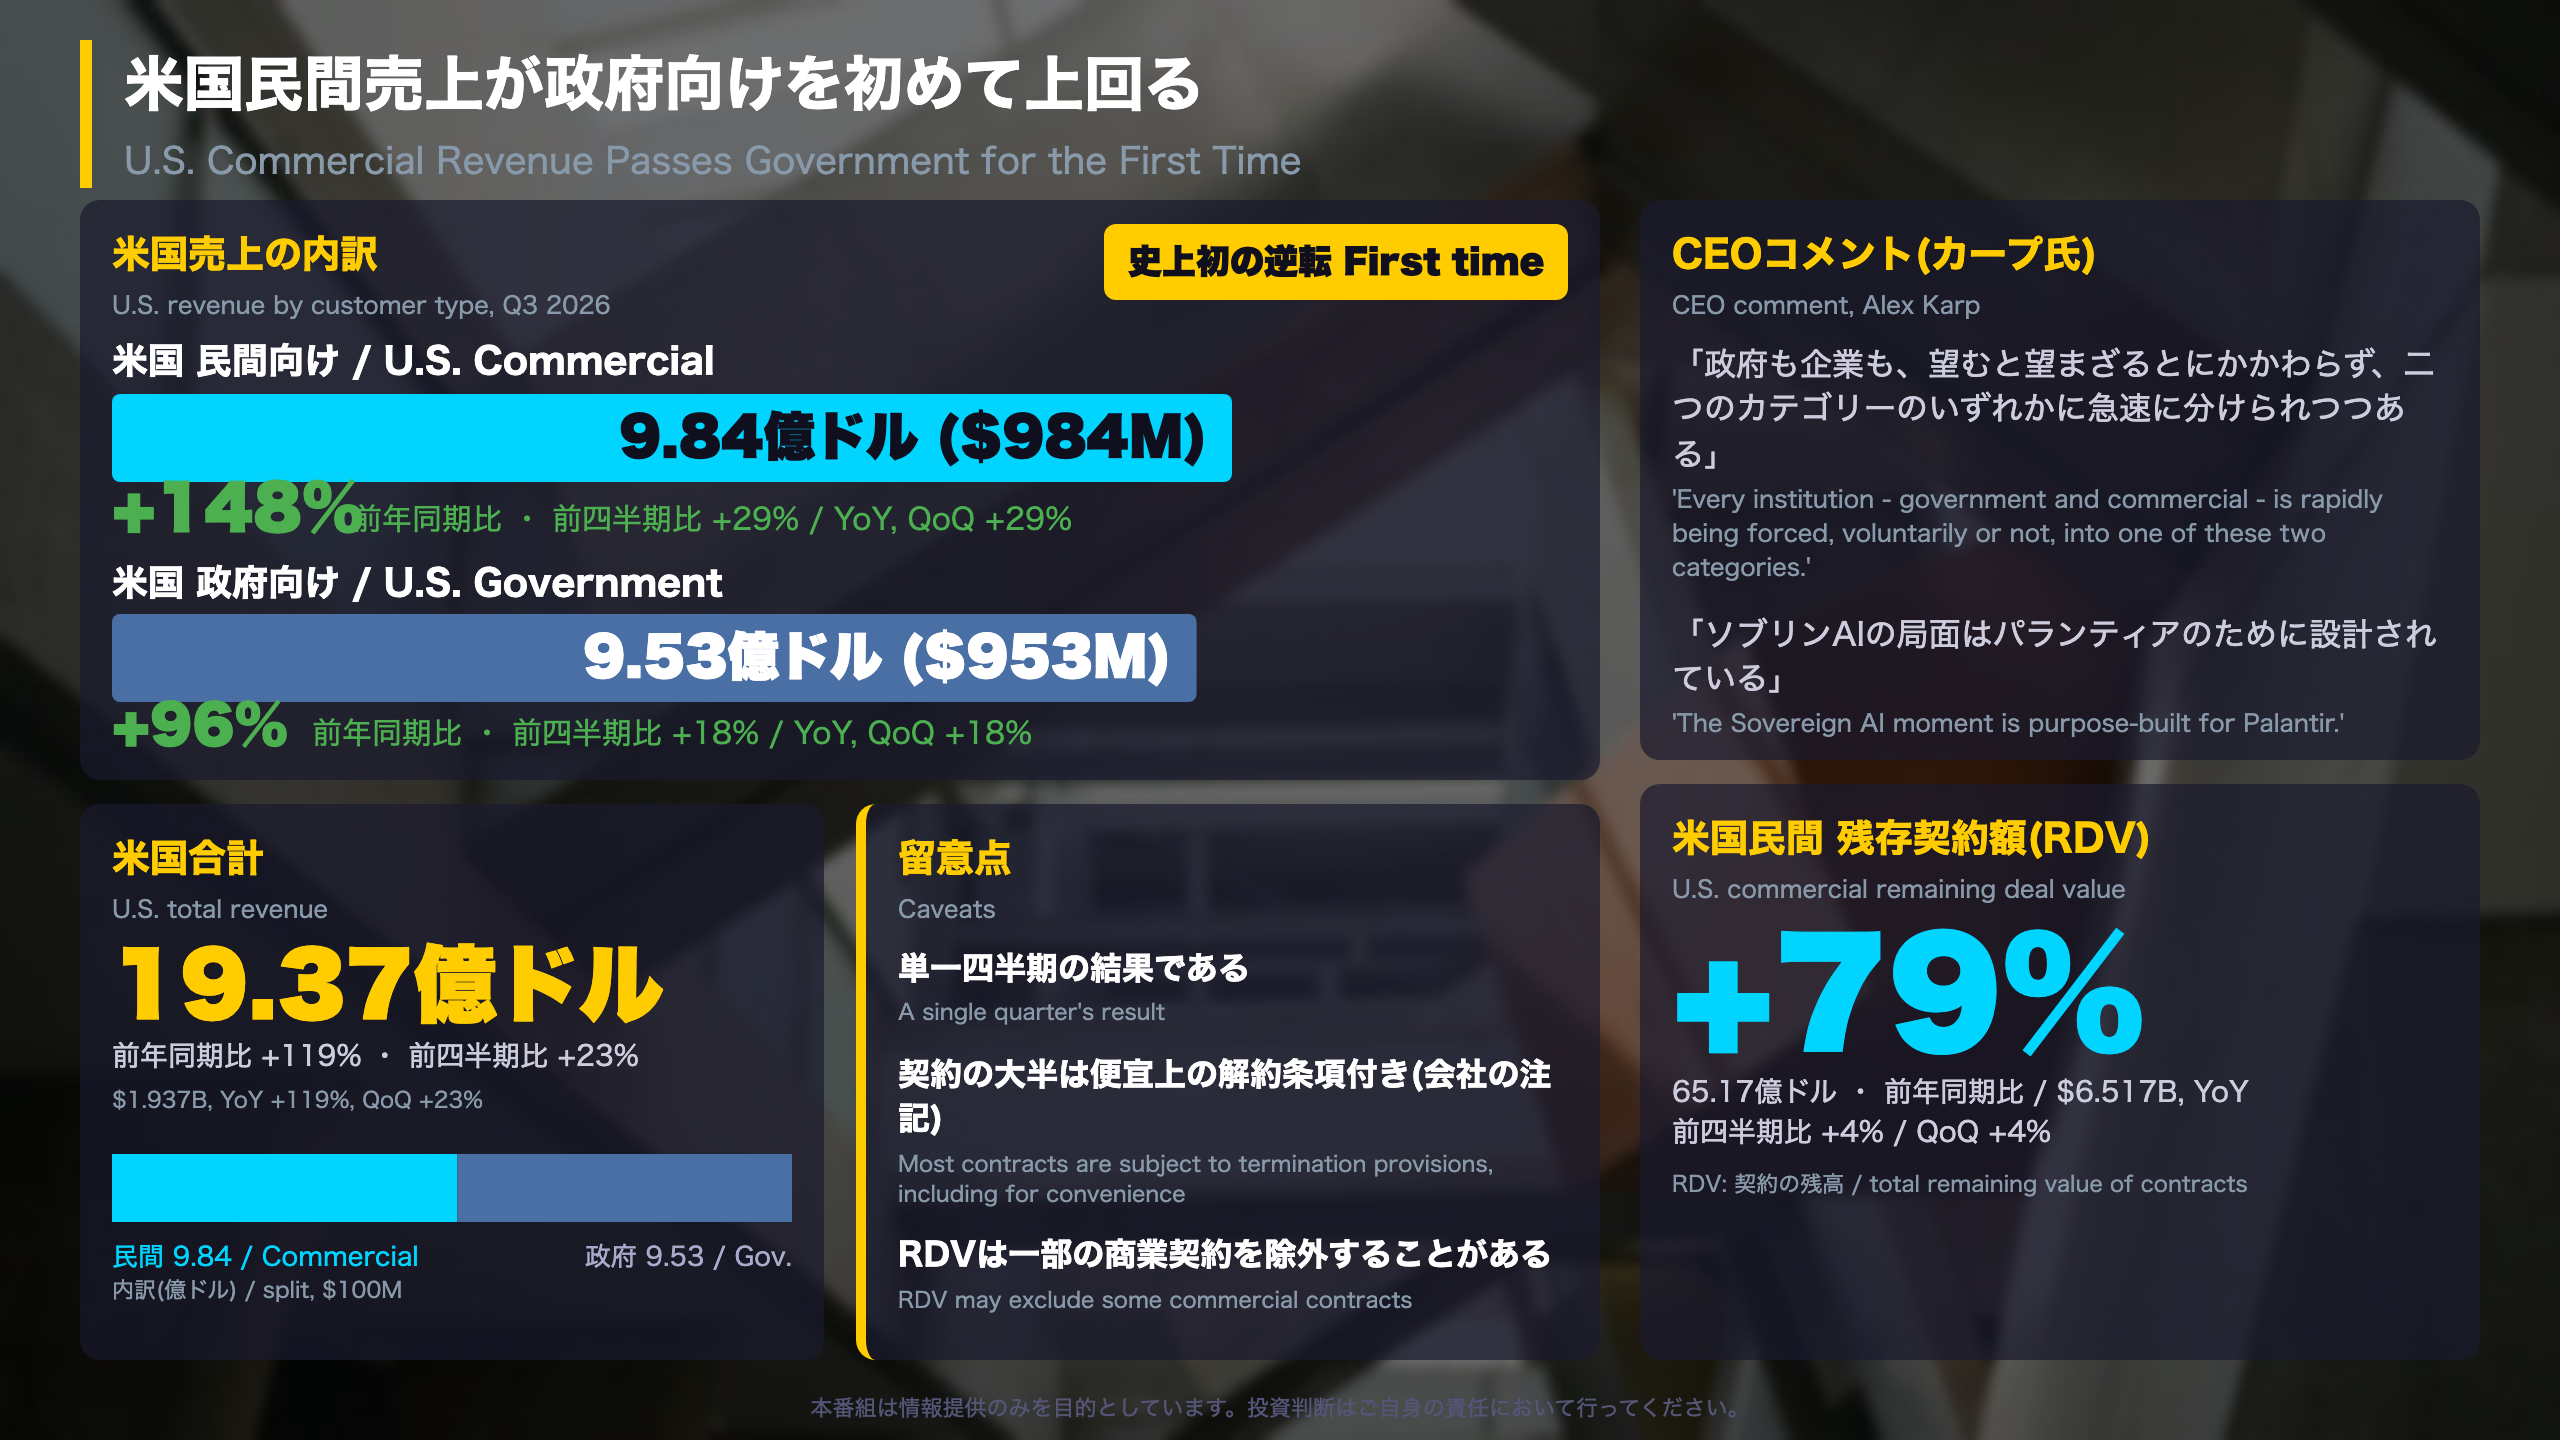
Palantir sells to two broad customer groups: government agencies, historically its anchor, and commercial firms. In Q3 2026, U.S. commercial revenue reached $984M (+148% YoY, +29% QoQ), edging past U.S. government revenue of $953M (+96% YoY, +18% QoQ). Combined U.S. revenue was $1.937B, up 119%.
Why the distinction matters
U.S. government work is often tied to multi-year programs with defense and civilian agencies. Commercial growth is typically driven by enterprise adoption of its AIP platform. The crossover therefore says something about customer mix, not only about size. Government revenue still grew 96%, so this is not a story of decline.
Contract-based indicators
- U.S. commercial remaining deal value (RDV): $6.517B, +79% YoY and +4% QoQ.
- U.S. commercial total contract value (TCV) closed: $1.463B, +11% YoY.
- Deals closed: 212 at $1M or more, 107 at $5M or more, 64 at $10M or more.
Reading the fine print
The company defines TCV and RDV assuming customers exercise all options and never terminate, yet it states that the majority of contracts include termination provisions, including for convenience. RDV may also exclude commercial contracts where payment ability is in question. Receivables rose to $1.883B from $1.042B at year-end, which is consistent with fast billing growth but is worth tracking.
Two views
Constructive: commercial demand is broadening while government keeps growing. Cautious: commercial TCV growth (+11%) trails revenue growth (+148%), so future revenue depends on new bookings accelerating. This release alone does not settle the question.
売上急増が利益につながった
Anatomy of the profit jump
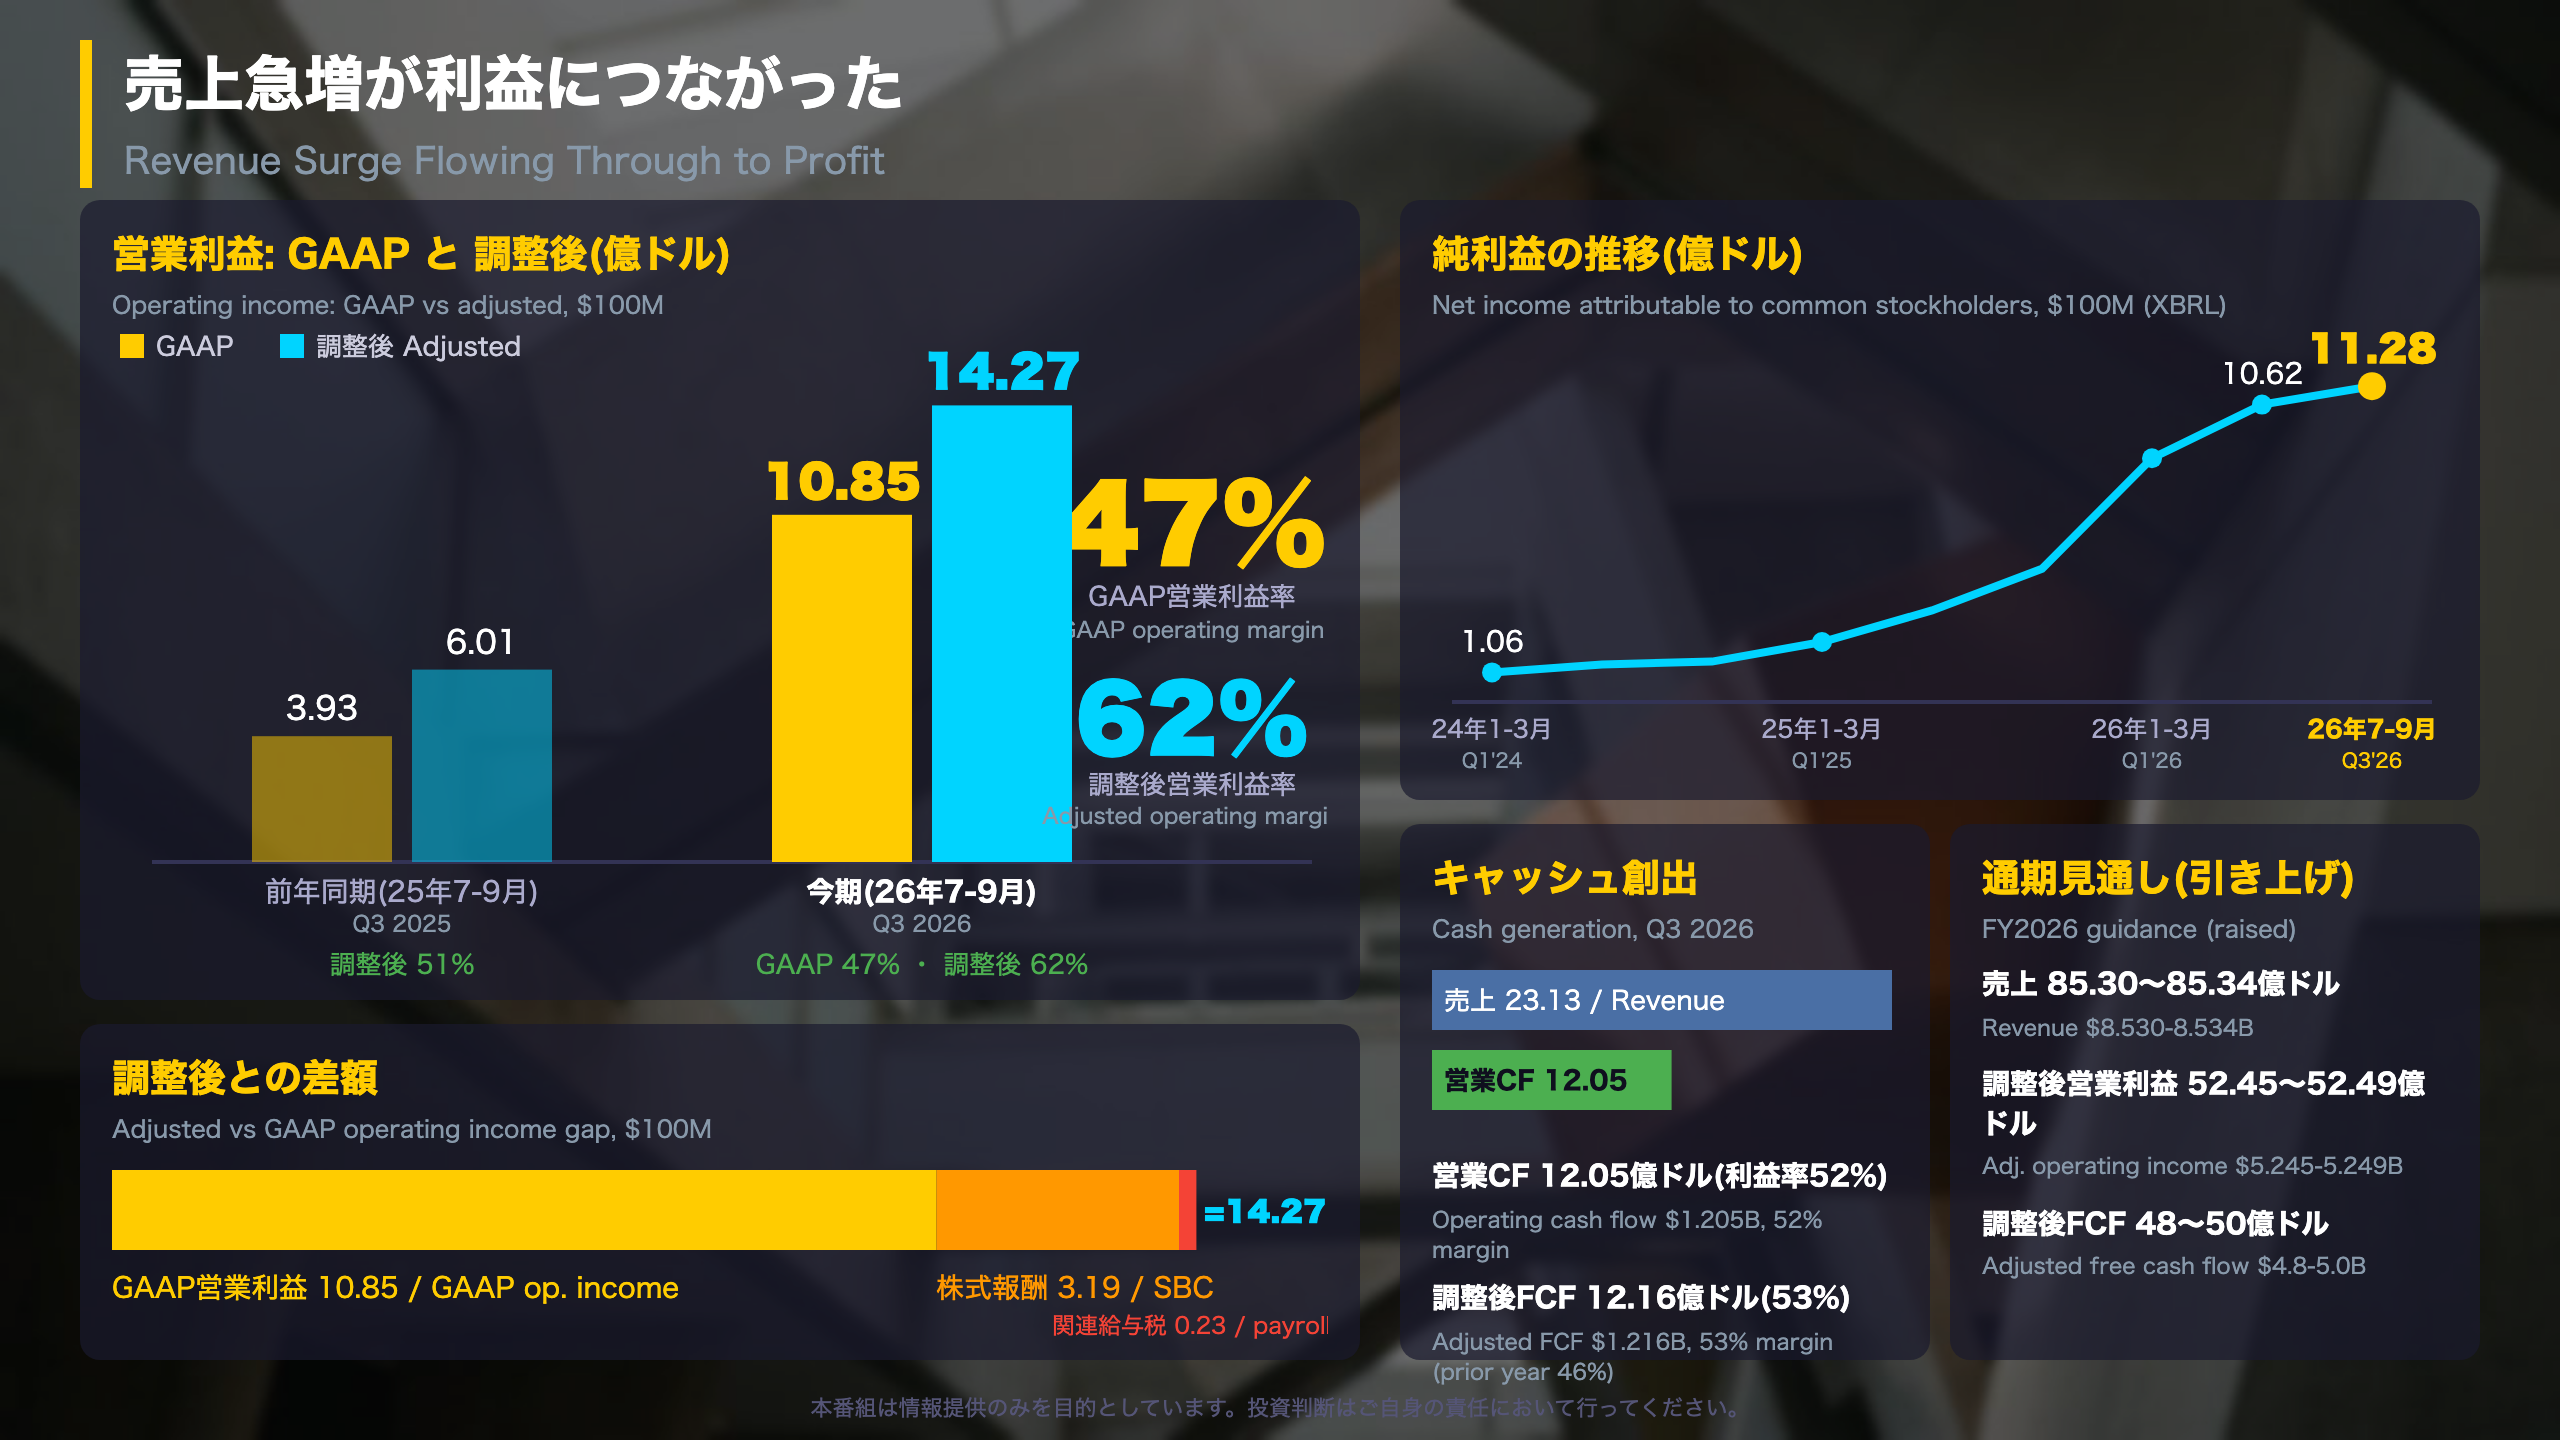
Operating income on a GAAP basis was $1.085B on revenue of $2.313B (47% margin), versus $393M a year earlier. Gross profit was $1.930B vs $974M. Operating expenses rose to $845M from $581M, a smaller percentage increase than revenue, which is what lifted margins.
GAAP vs adjusted
Palantir’s adjusted operating income ($1.427B, 62% margin) adds back stock-based compensation ($318.9M, up from $172.3M) and related employer payroll taxes ($23.1M). Adjusted measures are non-GAAP and defined by the company, so comparability with other firms may be limited, as the release itself says. The same add-back logic applies to adjusted EPS, which equals GAAP EPS at $0.44 this quarter.
Below the operating line
Interest income was $88.9M, while other income swung to an expense of $25.8M from income of $27.5M. Income tax was only $13.6M. Net income attributable to common holders was $1.128B.
Cash conversion
Adjusted free cash flow was $1.216B (53% margin vs 46% a year ago). Nine-month operating cash flow was $3.320B, partly offset by an $843M increase in receivables. The company cautions that adjusted FCF does not reflect future contractual commitments.
Two readings
Constructive: operating leverage is visible and cash generation is strong. Cautious: profit depends partly on non-cash stock compensation, and receivables are growing alongside revenue. Full-year guidance now calls for adjusted operating income of $5.245-5.249B and adjusted FCF of $4.8-5.0B.
質疑で深める:契約総額と見通し
Checking the guidance arithmetic
Palantir’s outlook is internally consistent with reported results. Nine-month revenue is $5.881B; adding Q4 guidance of $2.649-2.653B gives $8.530-8.534B, exactly the raised full-year range. Likewise, nine-month adjusted operating income of $3.605B plus Q4 guidance of $1.640-1.644B equals the $5.245-5.249B full-year range. The release does not explain the basis for the outlook, so this check confirms arithmetic, not assumptions.
Bookings vs revenue
Total contract value (TCV) of $2.918B grew 6% YoY, and U.S. commercial TCV of $1.463B grew 11%, against revenue growth of 96% and U.S. commercial revenue growth of 148%. TCV measures the potential lifetime value of contracts signed in a quarter, so it can be lumpy; revenue also draws on earlier contracts. Remaining deal value (RDV) for U.S. commercial, $6.517B, rose 79%.
Risk language in the filing
The company lists a long and unpredictable sales cycle and termination-for-convenience provisions among its risk factors. TCV, ACV and RDV assume all options are exercised and no terminations, which is not guaranteed.
Global context
For readers used to Japan’s fiscal-year reporting, note that Palantir follows a calendar year, so Q3 means July to September. The next report would be the Q4 and full-year release; the date is not given here.
What to watch
Whether Q4 revenue lands in the guided range, and whether TCV and RDV growth moves closer to revenue growth. We make no price forecast.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.