📺 Watch the Full Video Analysis
This article was automatically generated by the NFC Market Live AI analysis system. (Updated: 2026-10-01 08:58 JST)
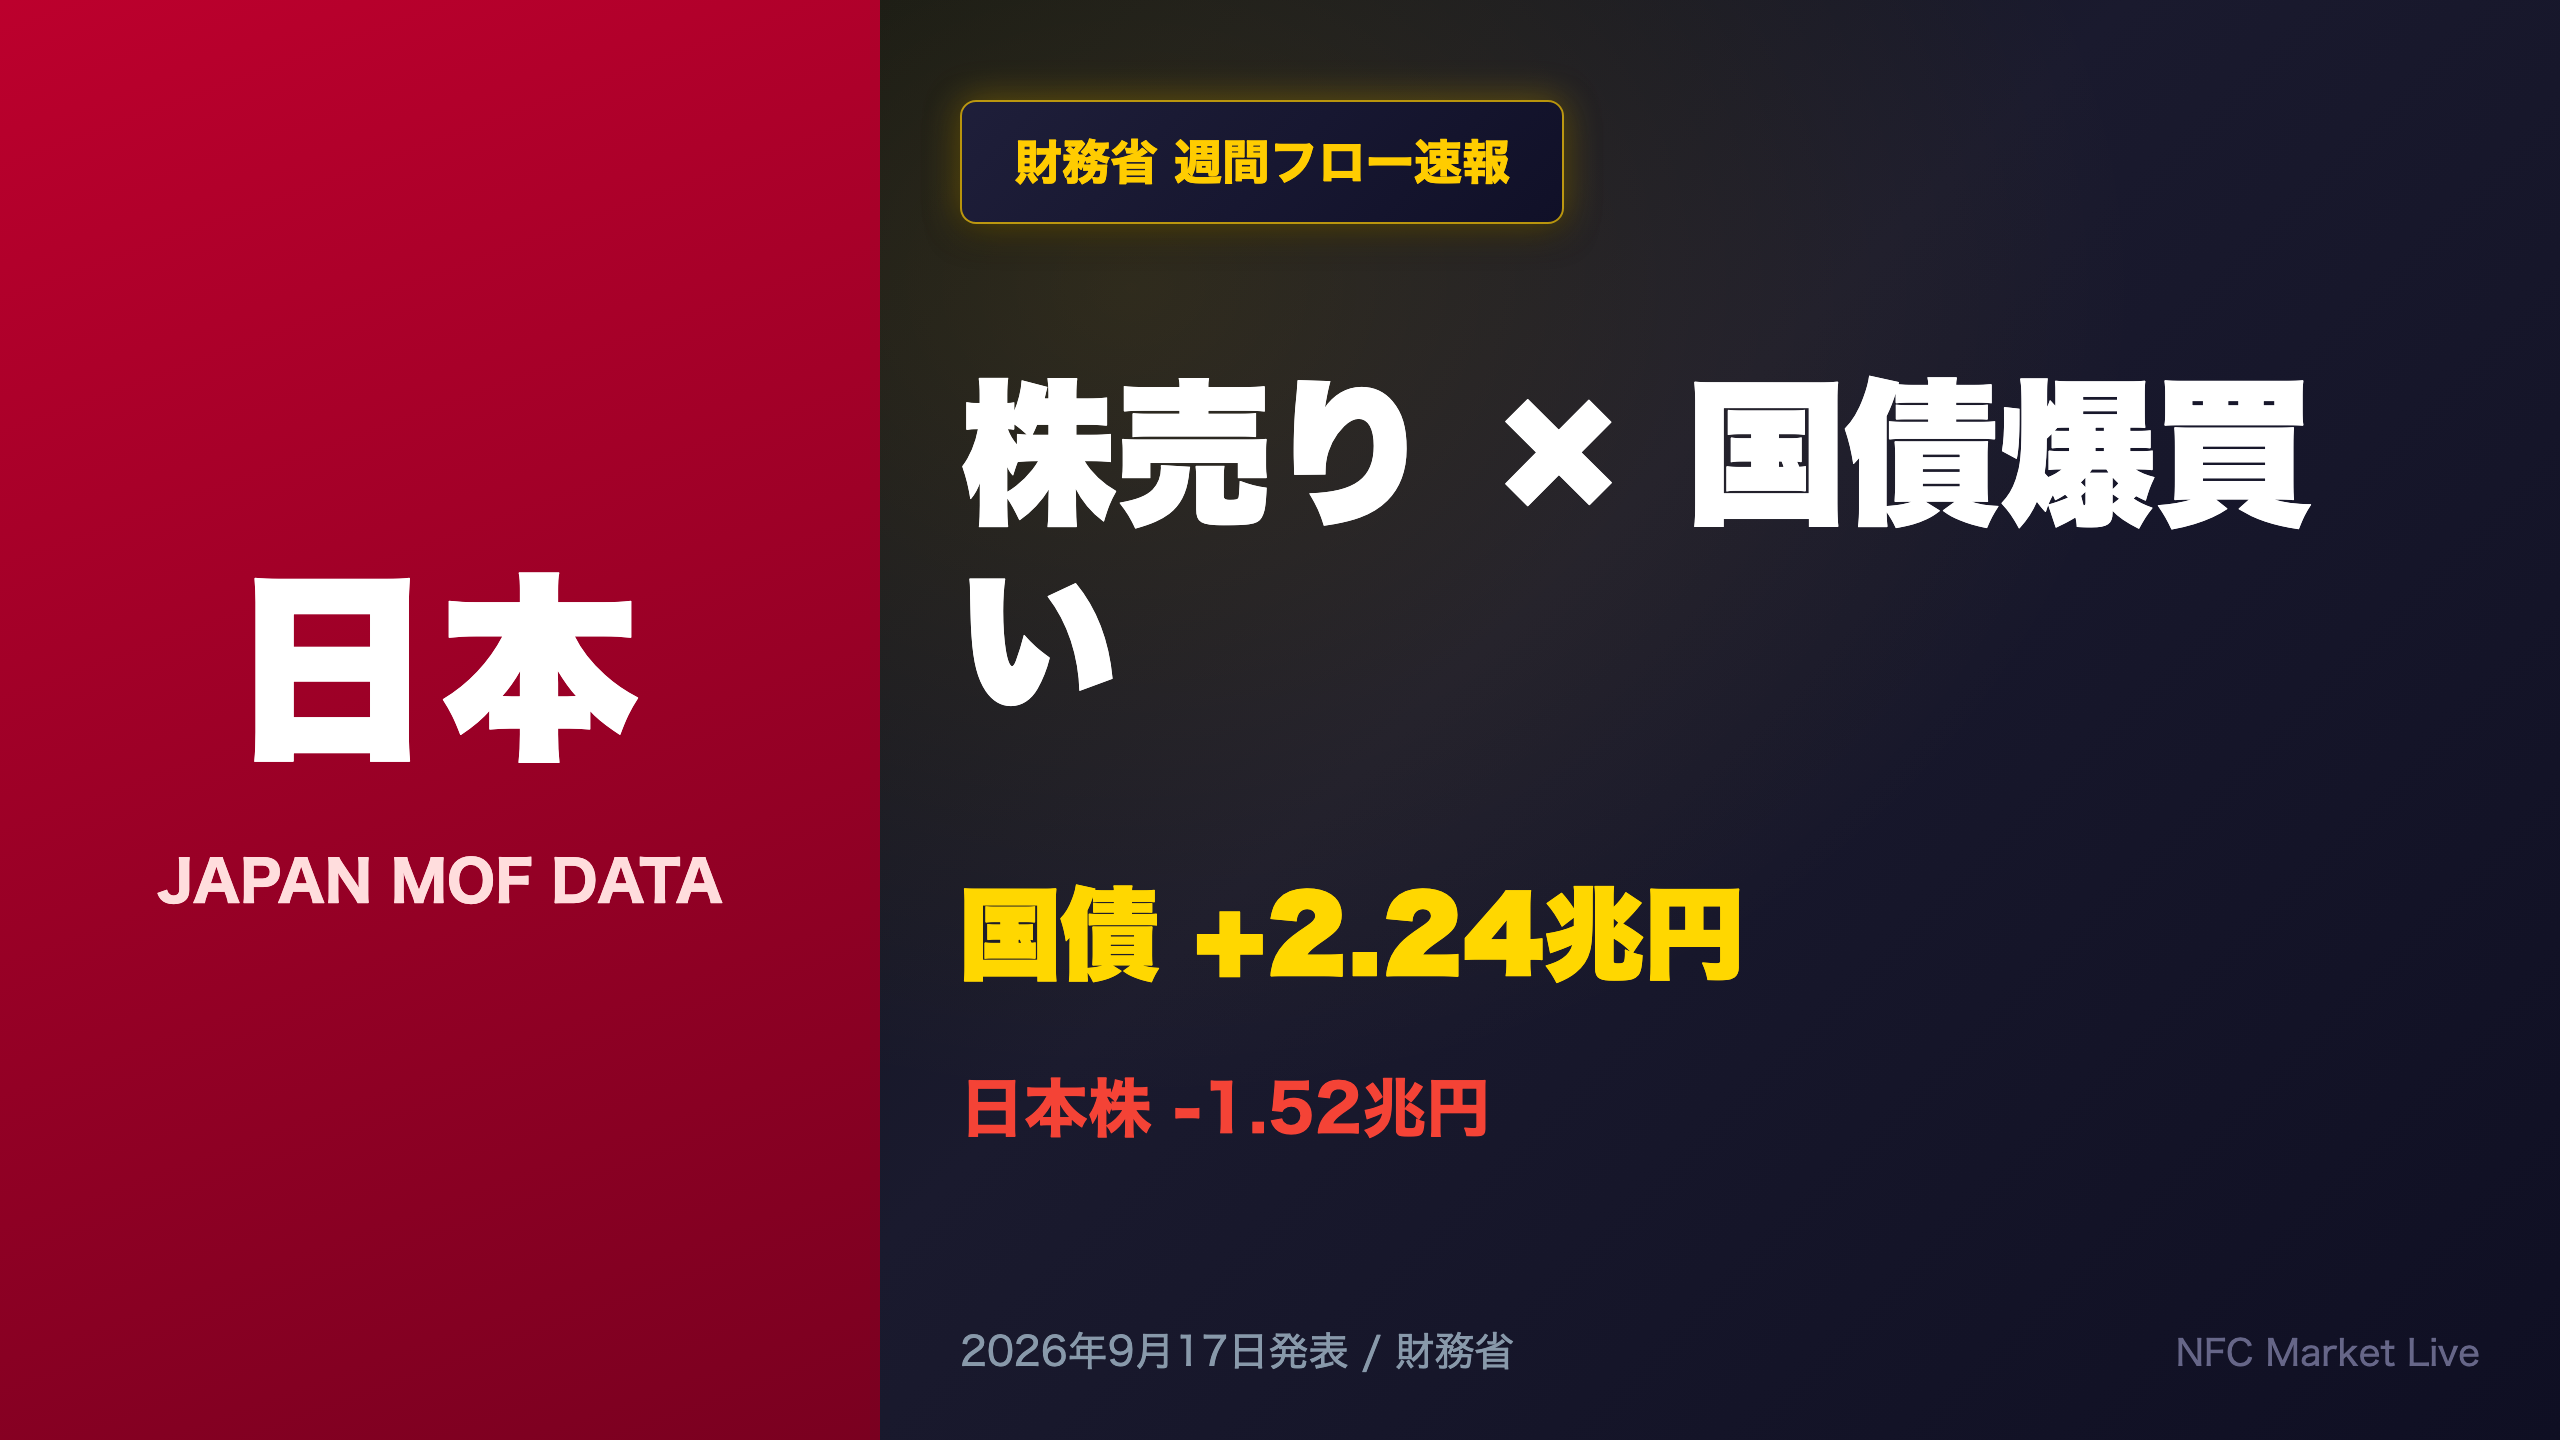
Japan’s Ministry of Finance released weekly capital flow data for Sep 6-12. 📊
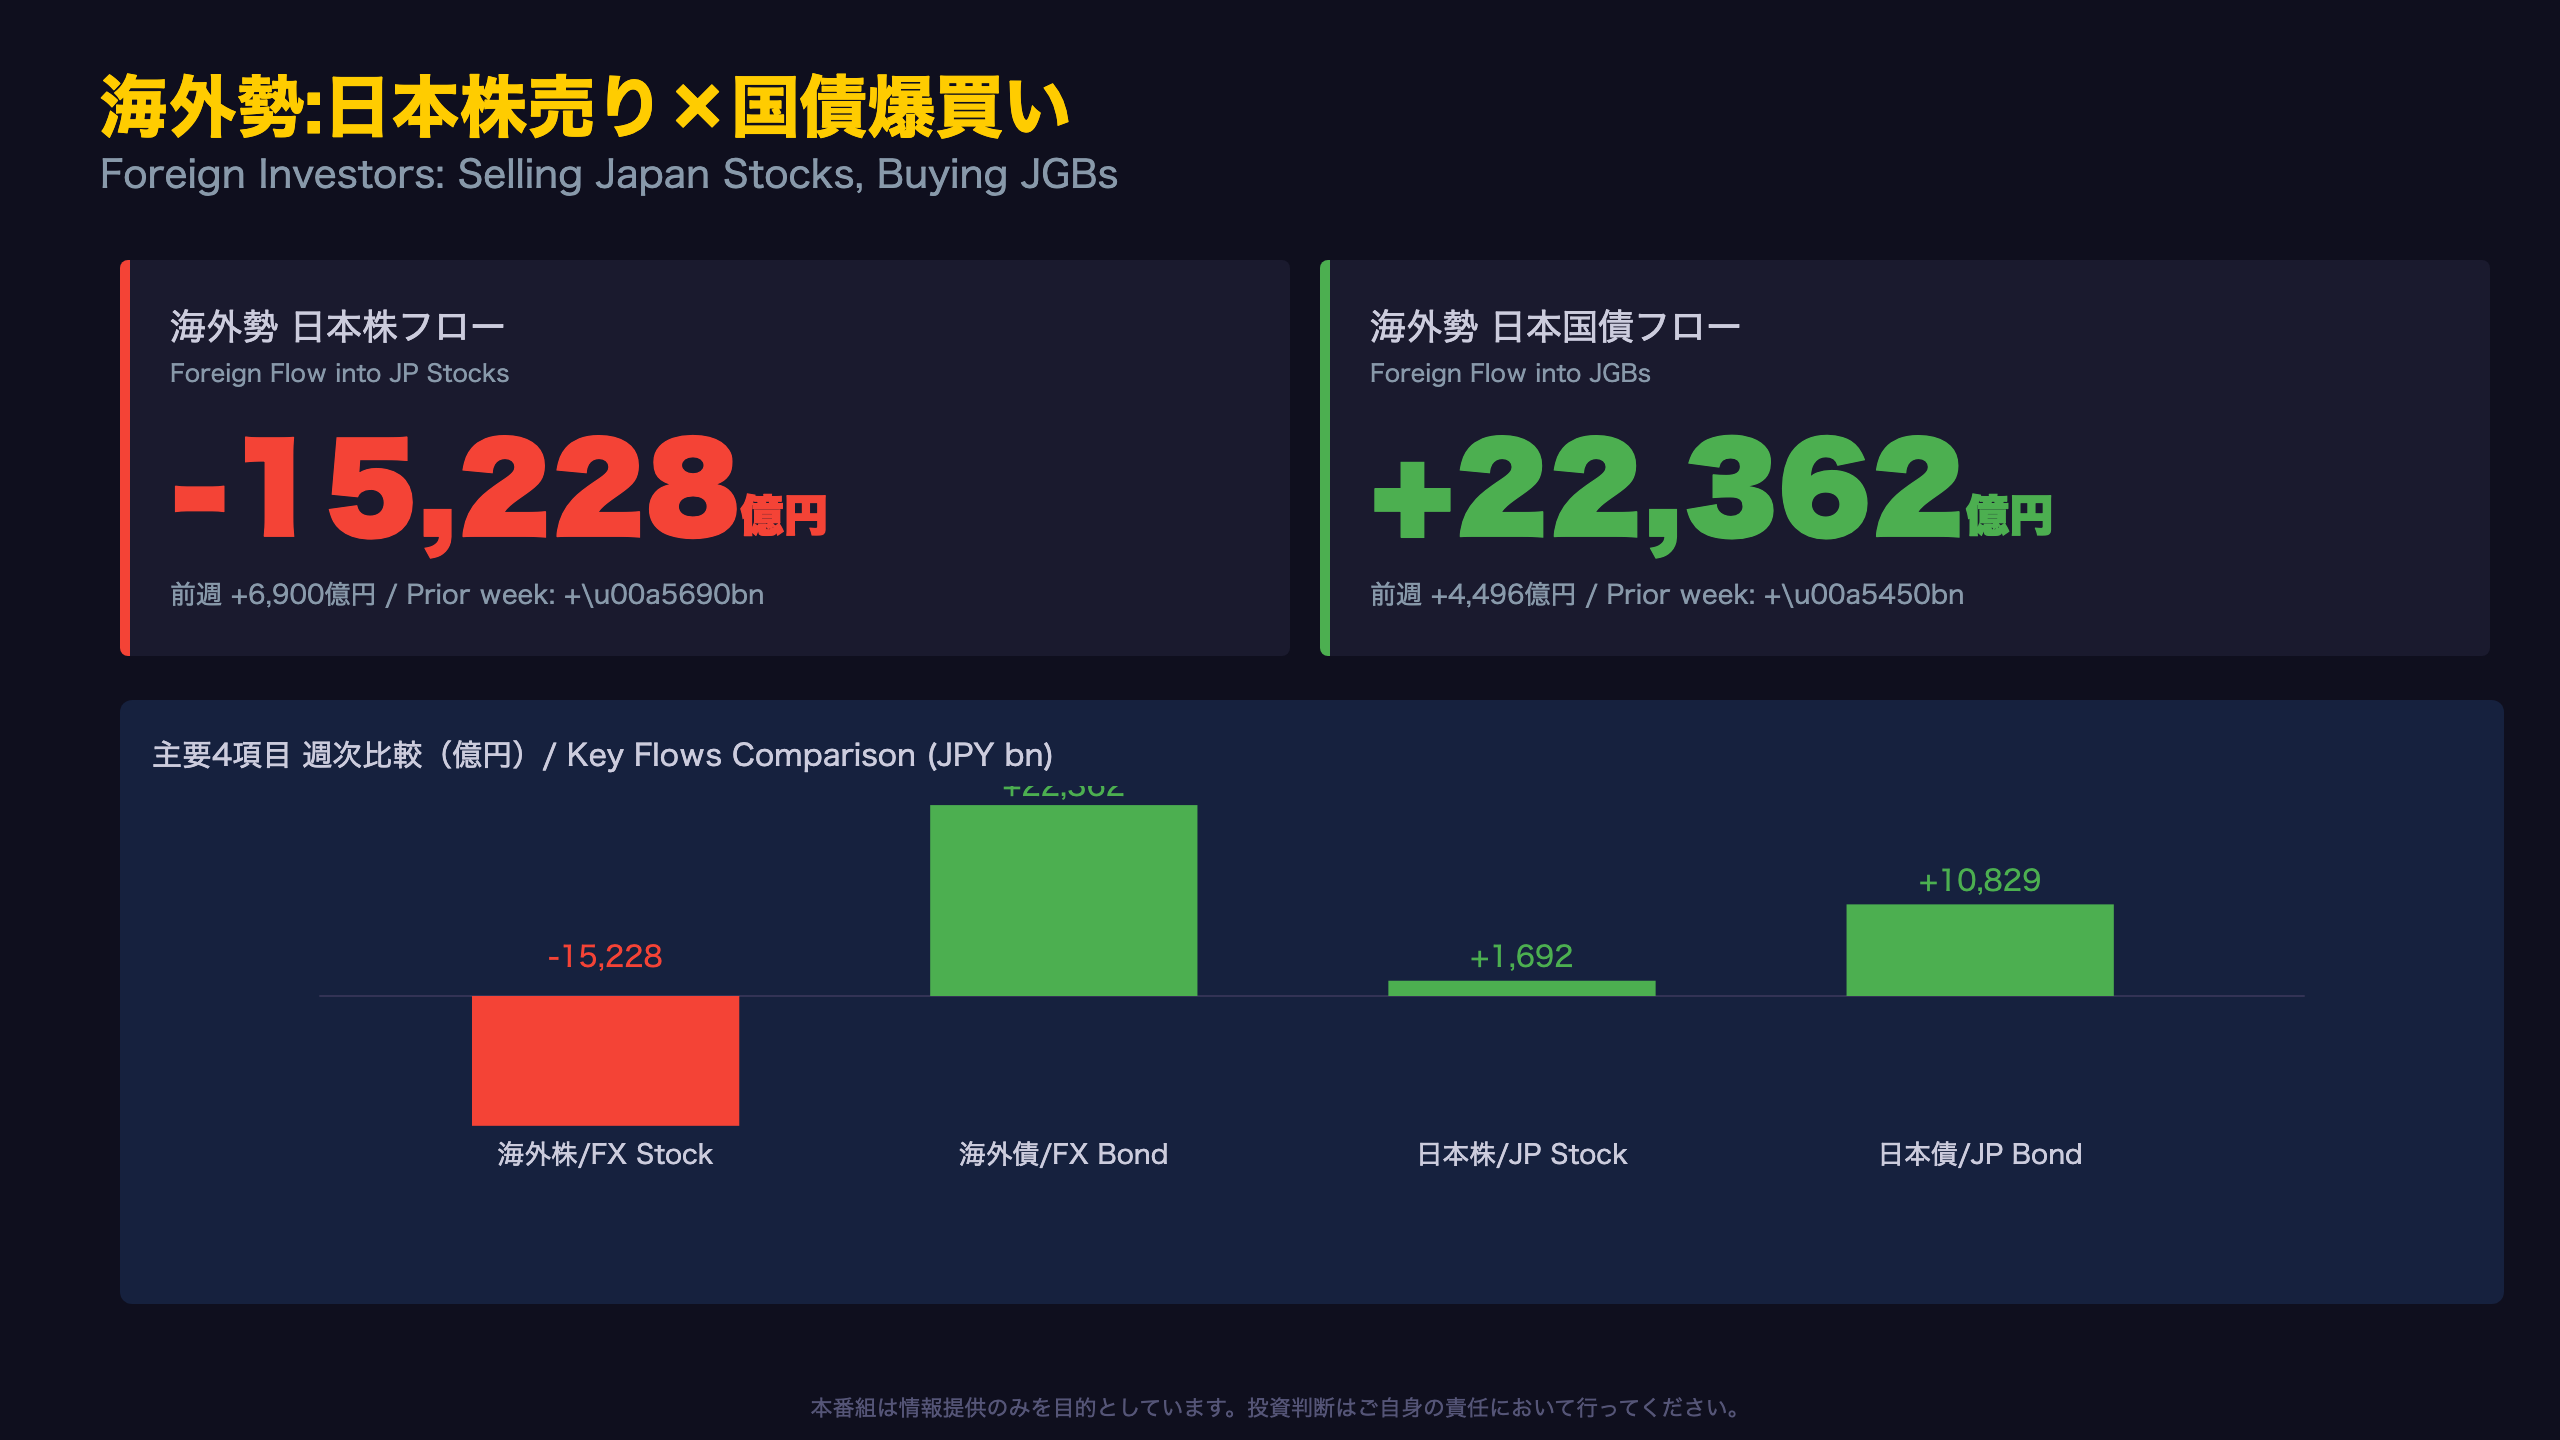
Foreign investors sold ¥1.52tn of Japanese stocks while buying ¥2.24tn of JGBs — the second-largest bond inflow in a year. ⚠️
The pattern is a complete reversal from the prior week, and USD/JPY fell from 156 to 153.71. 💹
We break down what this contradictory flow means for yields and the yen.
海外勢:日本株売り×国債爆買いの矛盾フロー
Weekly Capital Flow Snapshot
Japan’s Ministry of Finance (MOF) publishes the “Weekly Securities Flow Report” (対外及び対内証券売買契約等の状況) every week, capturing contracted purchases and sales of securities between Japanese residents and non-residents. It is one of the most closely watched high-frequency indicators for tracking foreign appetite for Japanese assets, comparable in spirit to the U.S. TIC data, though released far more frequently.
| Category | This Week | Prior Week |
|---|---|---|
| Foreign — JP Stocks | -\u00a51.52tn | +\u00a50.69tn |
| Foreign — JGBs | +\u00a52.24tn | +\u00a50.45tn |
| Resident — Foreign Stocks | +\u00a50.17tn | -\u00a50.48tn |
| Resident — Foreign Bonds | +\u00a51.08tn | +\u00a50.11tn |
| USD/JPY | 153.71 | 156.11 |
All four flow categories reversed direction versus the prior week, a rare simultaneous rotation. For investors accustomed to monthly TIC or EPFR fund-flow data, this weekly granularity offers an earlier read on cross-border positioning shifts, often before they show up in slower-moving datasets.
The following slides unpack why bonds and equities diverged so sharply, and what it implies for JGB yields and the yen.
海外勢 日本株フロー:底堅い買いから急反転
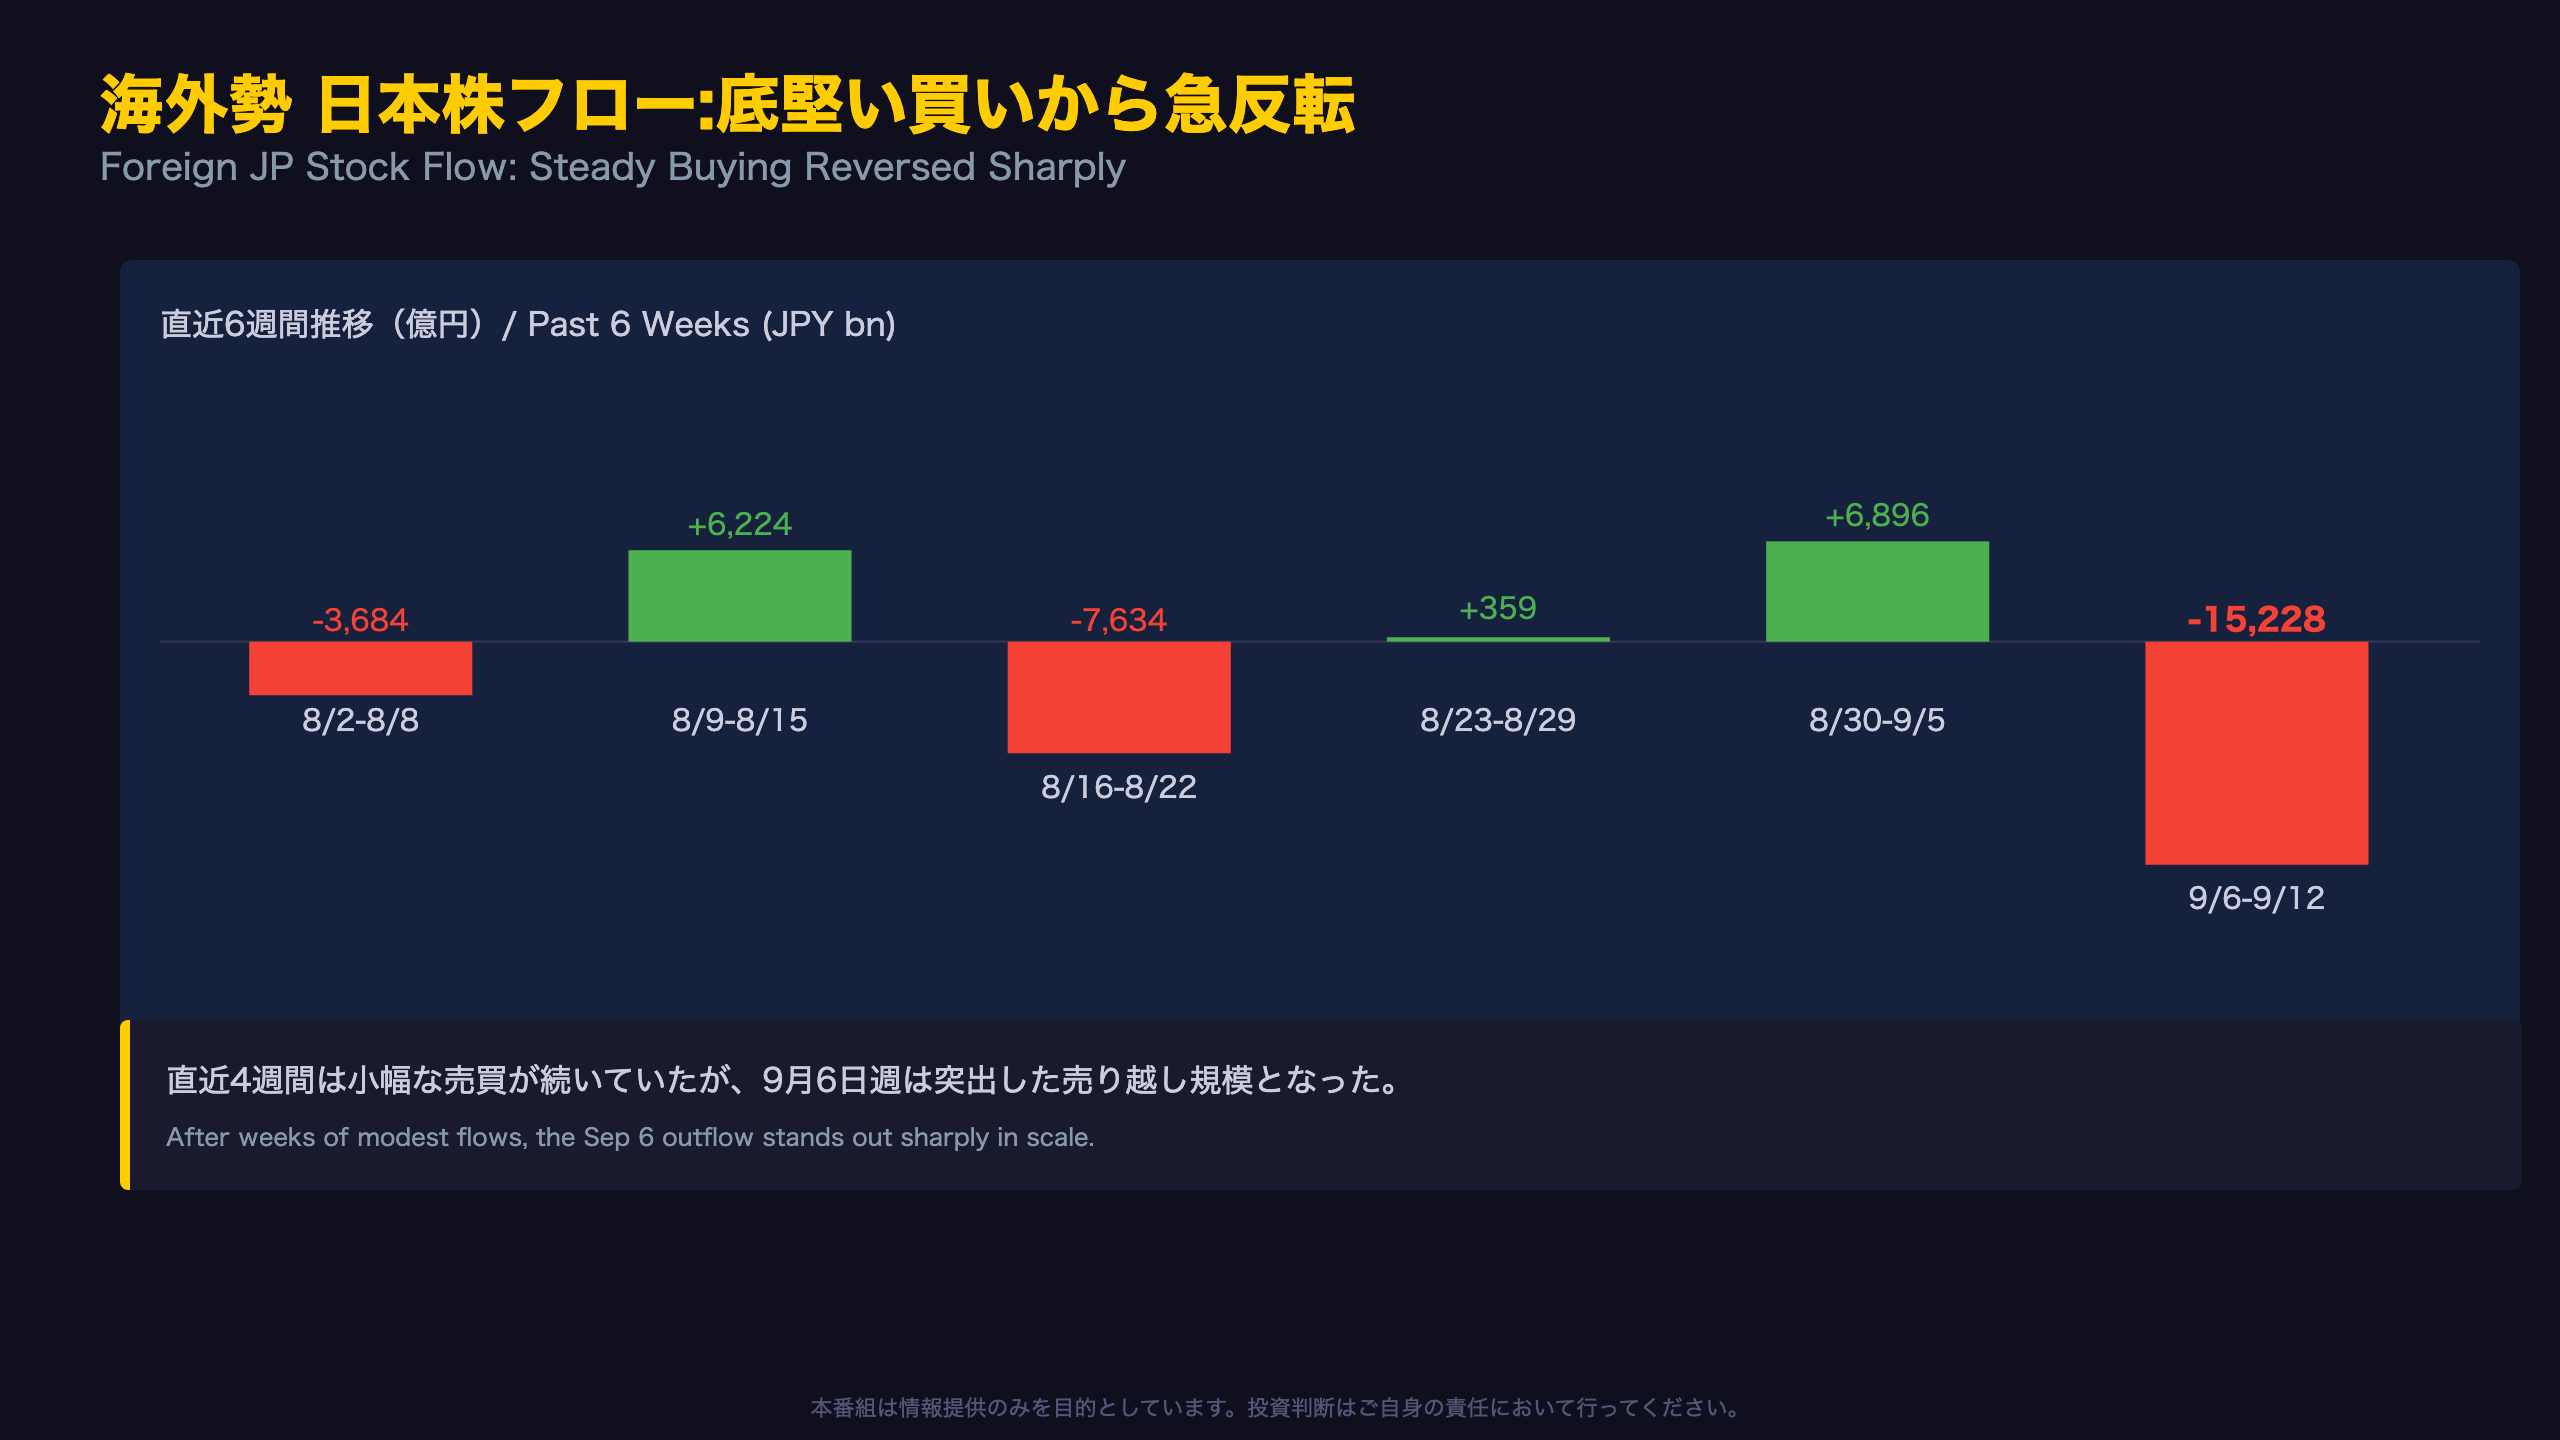
Six-Week Foreign Equity Flow Trend
| Week | Net Flow (\u00a5bn) |
|---|---|
| Aug 9-15 | +622 |
| Aug 16-22 | -763 |
| Aug 23-29 | +36 |
| Aug 30-Sep 5 | +690 |
| Sep 6-12 | -1,523 |
Foreign investors had been oscillating between small buy and sell weeks for roughly a month, a pattern consistent with a rangebound, low-conviction equity market. The September 6th week’s outflow, however, stands out as the largest single-week move in this run.
For context, Japan’s Tokyo Stock Exchange (JPX) publishes a complementary \”foreign investor trading trends\” series that some traders cross-check against this MOF release; the two can occasionally diverge due to differing settlement-date conventions.
It is worth noting this series has a history of large mean-reverting swings, a \u00a54.45tn single-week sell-off in late March was followed by a quick rebound in April. That precedent urges caution against over-interpreting a single week’s -\u00a51.52tn move as the start of a durable trend.
海外勢 日本国債買い越し:過去1年で2番目の規模
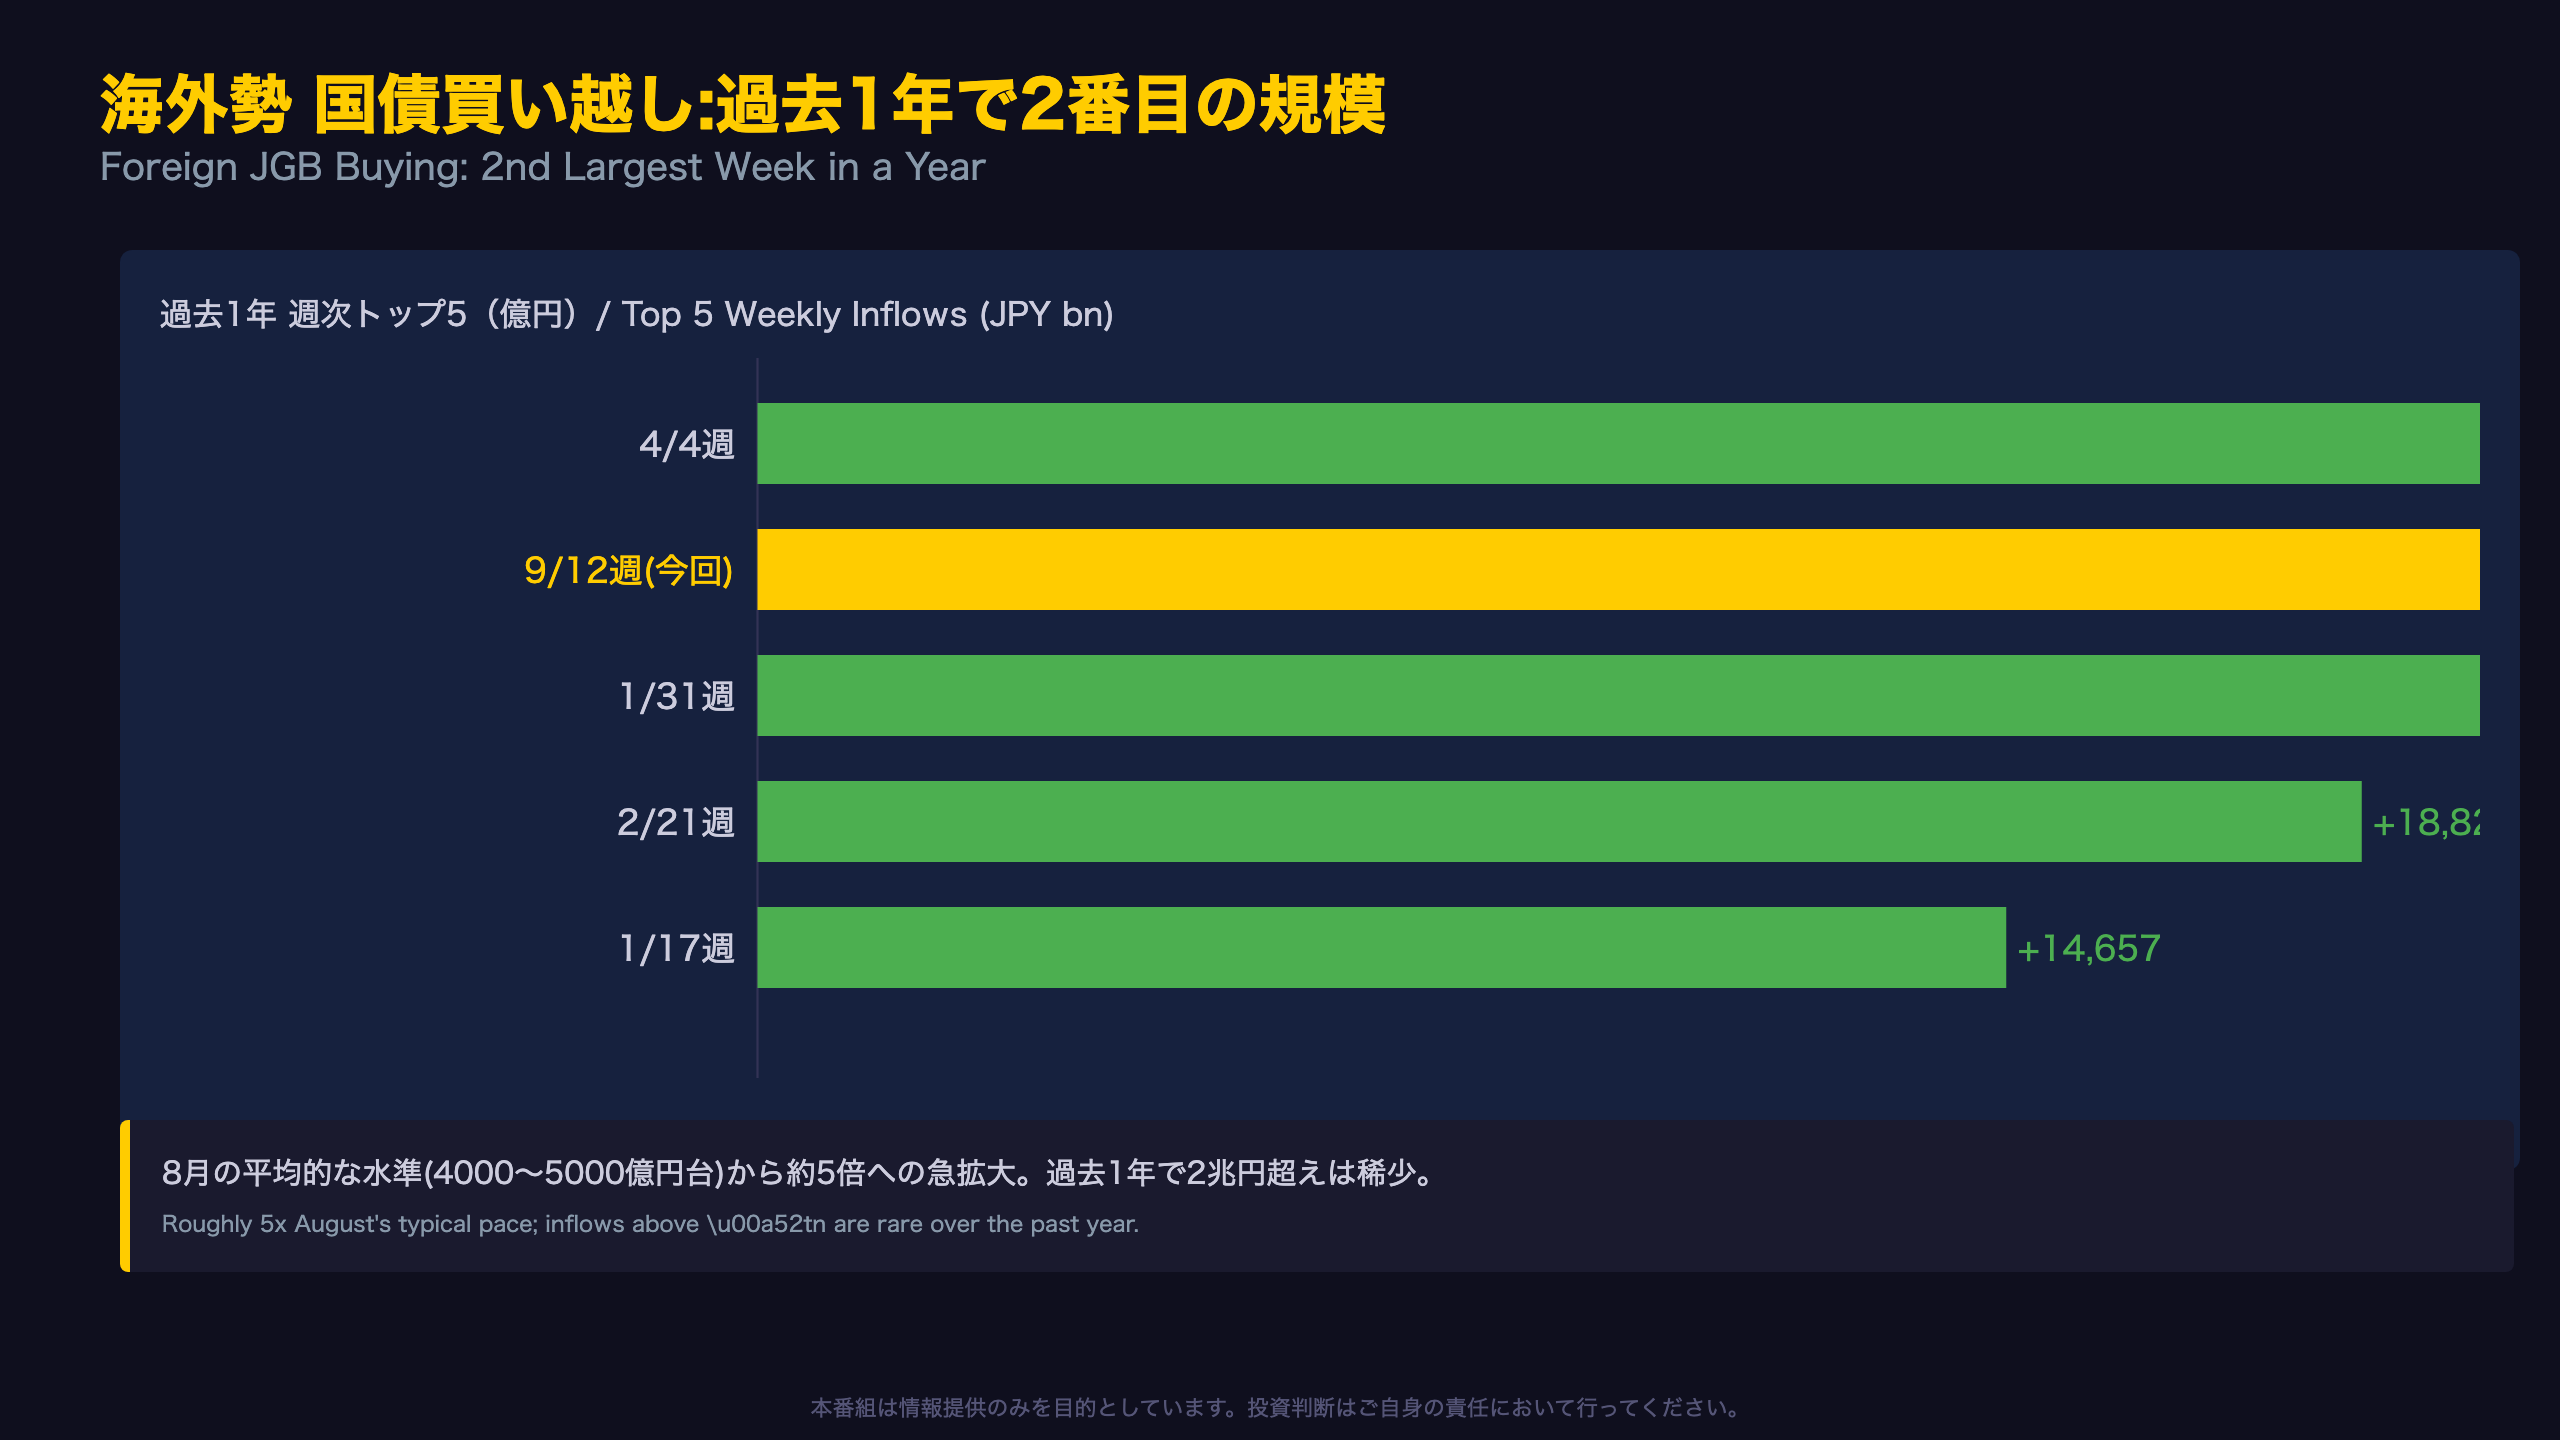
Top 5 Weekly Foreign JGB Inflows (Past Year)
| Rank | Week | Amount (\u00a5bn) |
|---|---|---|
| 1 | Apr 4, 2026 | +2,376 |
| 2 | Sep 12, 2026 (this week) | +2,236 |
| 3 | Jan 31, 2026 | +2,081 |
| 4 | Feb 21, 2026 | +1,883 |
| 5 | Jan 17, 2026 | +1,466 |
This week’s figure is comparable in scale to the buying surges seen around late January and late February, periods when speculation about Bank of Japan policy shifts was running high.
For readers unfamiliar with the series: this MOF report is Japan’s closest equivalent to the U.S. Treasury’s monthly TIC (Treasury International Capital) data, but published weekly and with a much shorter lag, giving markets a faster read on foreign JGB demand than the U.S. equivalent offers for Treasuries.
One caveat: single-week spikes in this series can reflect lumpy institutional rebalancing (pension funds, sovereign wealth vehicles) rather than a broad-based shift in sentiment. The next release, expected around September 24th, will be the key test of whether this pace of buying persists.
日本人投資家も動く:外債投資が前週の10倍に拡大
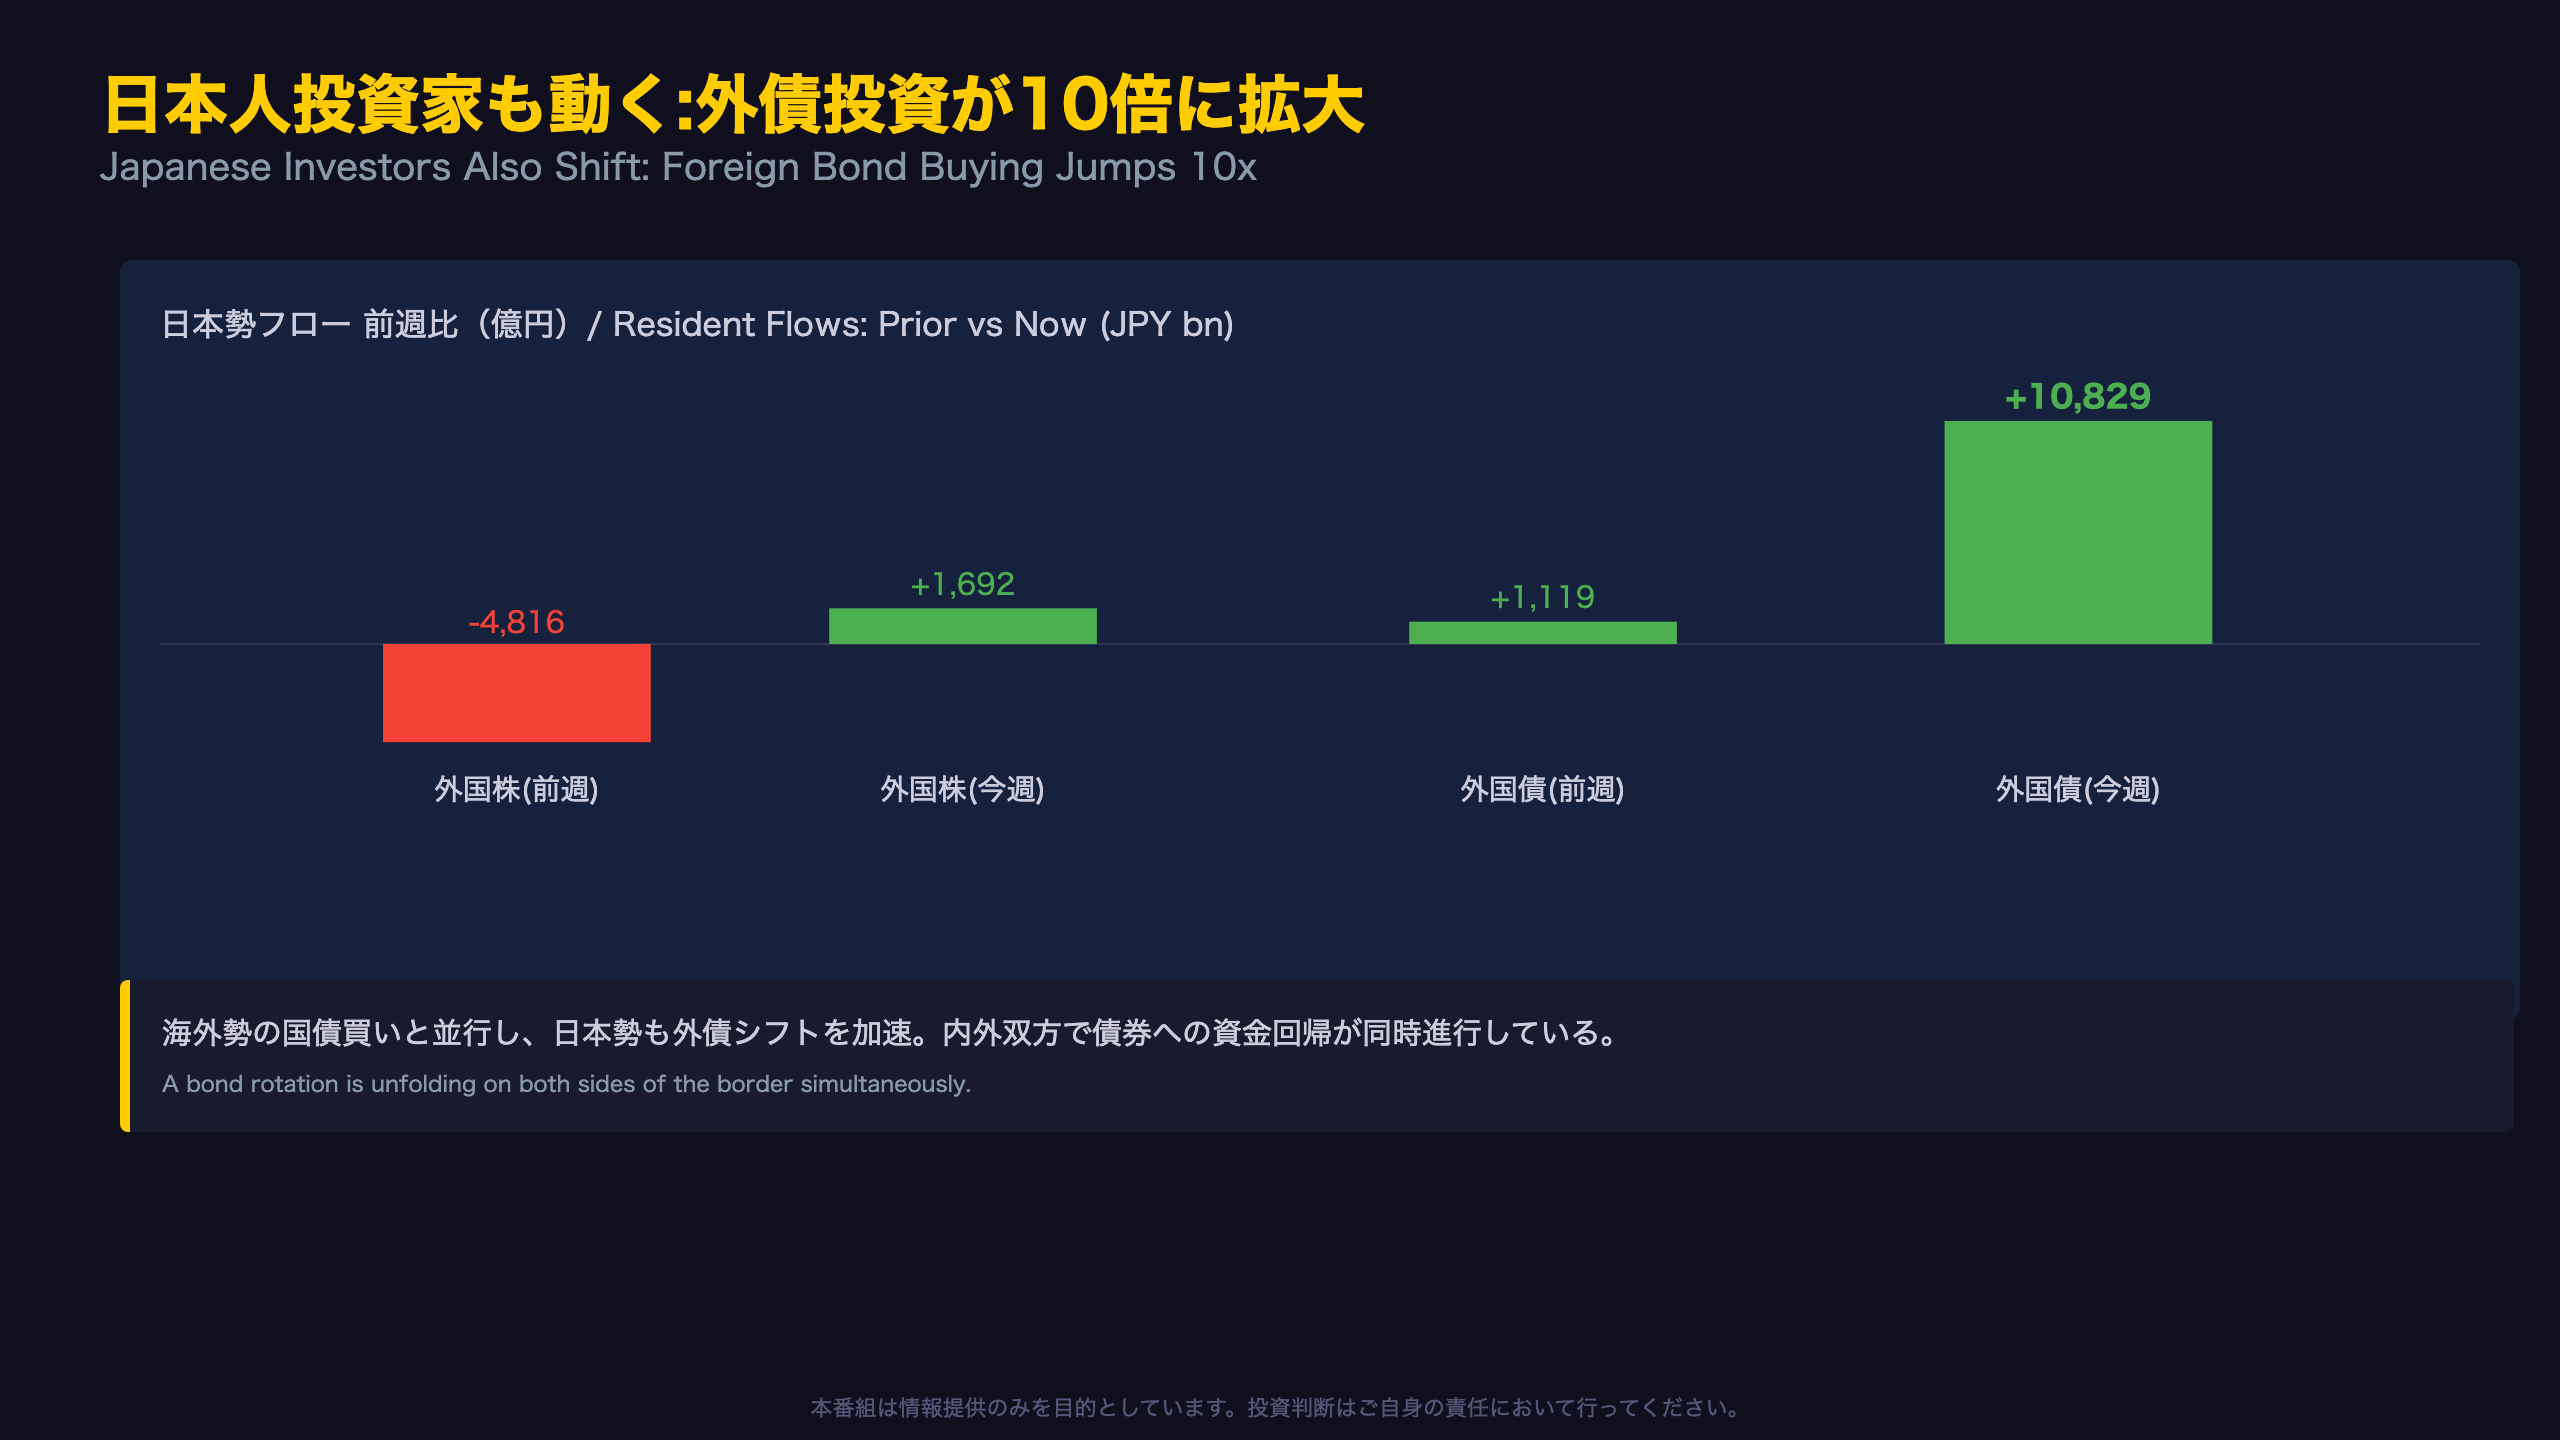
Japanese Investors’ Foreign Bond Buying Trend
| Week | Foreign Stocks (\u00a5bn) | Foreign Bonds (\u00a5bn) |
|---|---|---|
| Aug 23-29 | +36 | -824 |
| Aug 30-Sep 5 | -482 | +112 |
| Sep 6-12 | +169 | +1,083 |
Japanese foreign-bond buying had dipped into an \u00a5824bn net sale in late August, before swinging back to two consecutive weeks of net buying, this week’s figure ranks among the largest of the year so far.
One plausible, though unconfirmed, explanation is periodic rebalancing by large institutional investors such as pension funds near quarter-end or month-end. The underlying MOF data does not break down flows by investor type, so this remains a reasonable hypothesis (Level C) rather than a confirmed driver.
The next release will show whether this pace of outbound bond buying holds or proves to be a one-off. Watch for confirmation in the following week’s report, expected around September 24th.
円高進行と債券買いの同時発生:為替への含意
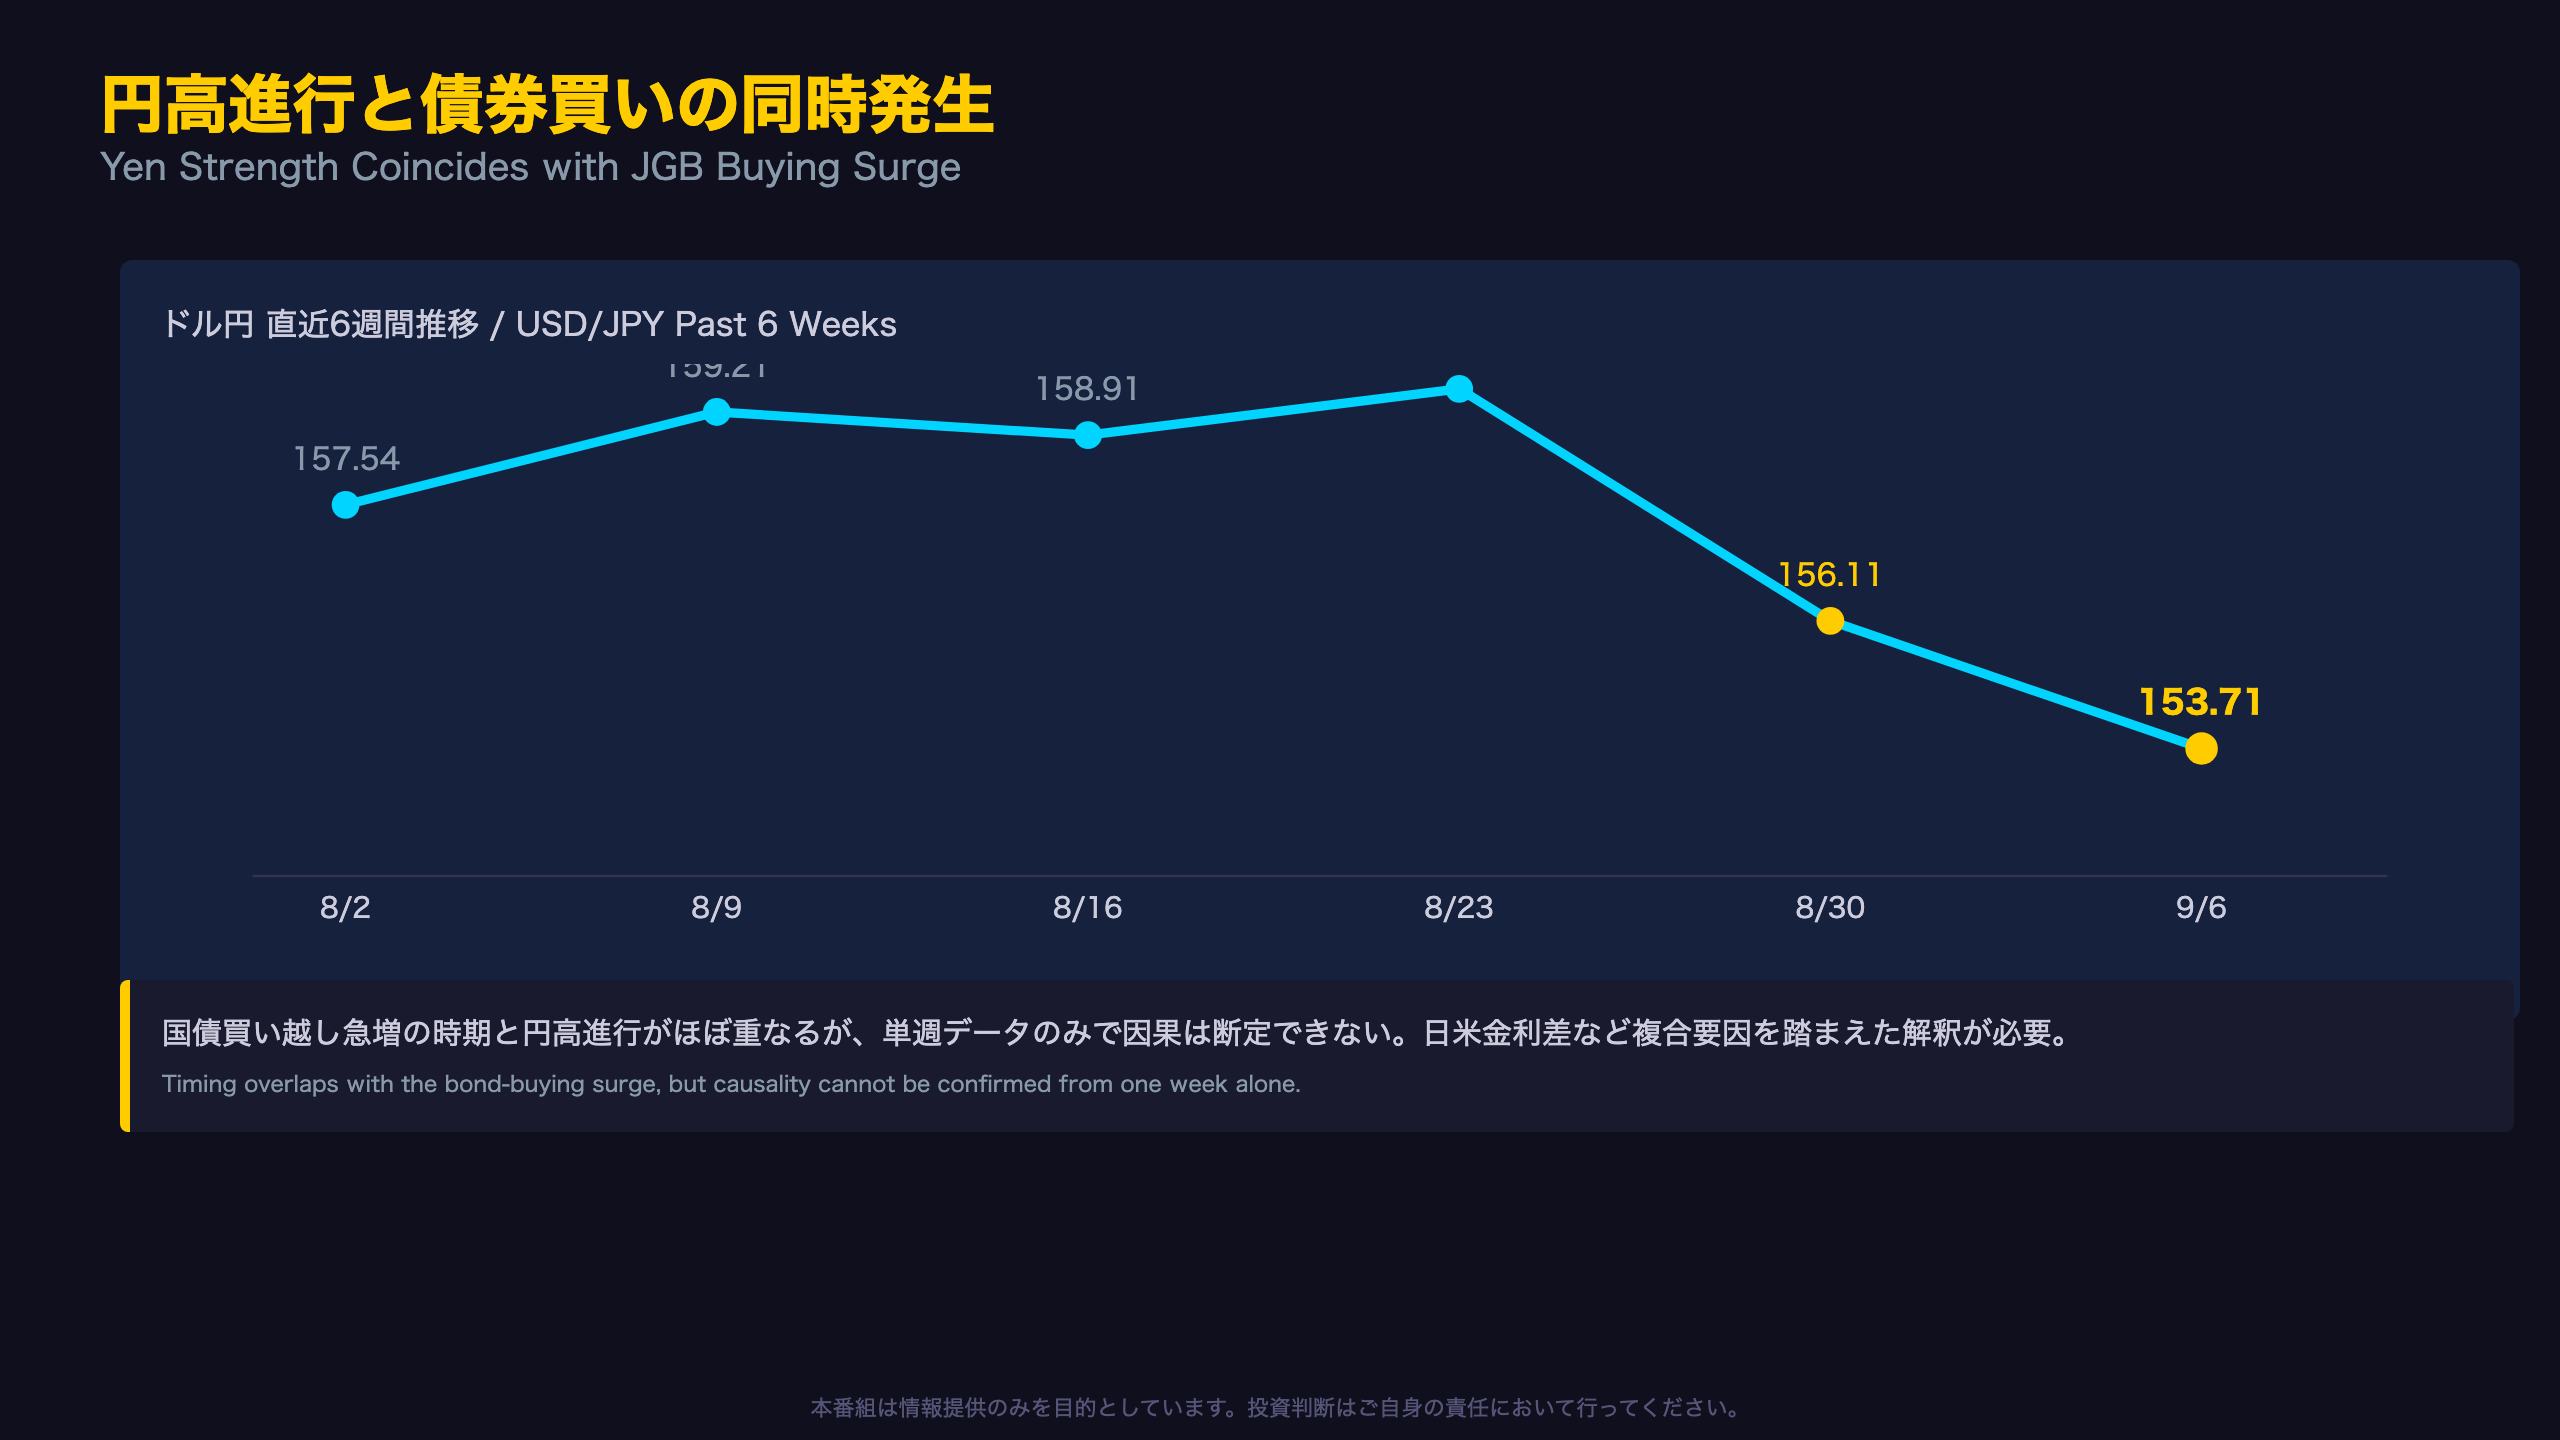
USD/JPY Recent Trend
| Week | USD/JPY |
|---|---|
| Aug 2-8 | 157.54 |
| Aug 9-15 | 159.21 |
| Aug 16-22 | 158.91 |
| Aug 23-29 | 159.97 |
| Aug 30-Sep 5 | 156.11 |
| Sep 6-12 | 153.71 |
After trading near the 160 handle through much of late August, USD/JPY has weakened for two straight weeks, moving over six yen lower in that span.
This period overlaps closely with the surge in foreign JGB buying (from +\u00a5444bn in the week of Aug 30 to +\u00a52.24tn in the week of Sep 6). For context, U.S. and European readers should note that Japan-U.S. rate differentials remain a dominant driver of USD/JPY, and the MOF flow data alone cannot isolate how much of this move is attributable to bond-related yen demand versus shifting expectations around the gap between Fed and BOJ policy rates.
The next weekly flow release, alongside any shifts in U.S.-Japan yield spreads, will help clarify whether this yen strength is a durable trend or a temporary retracement.
総括:債券シフトは一過性か、構造変化の始まりか
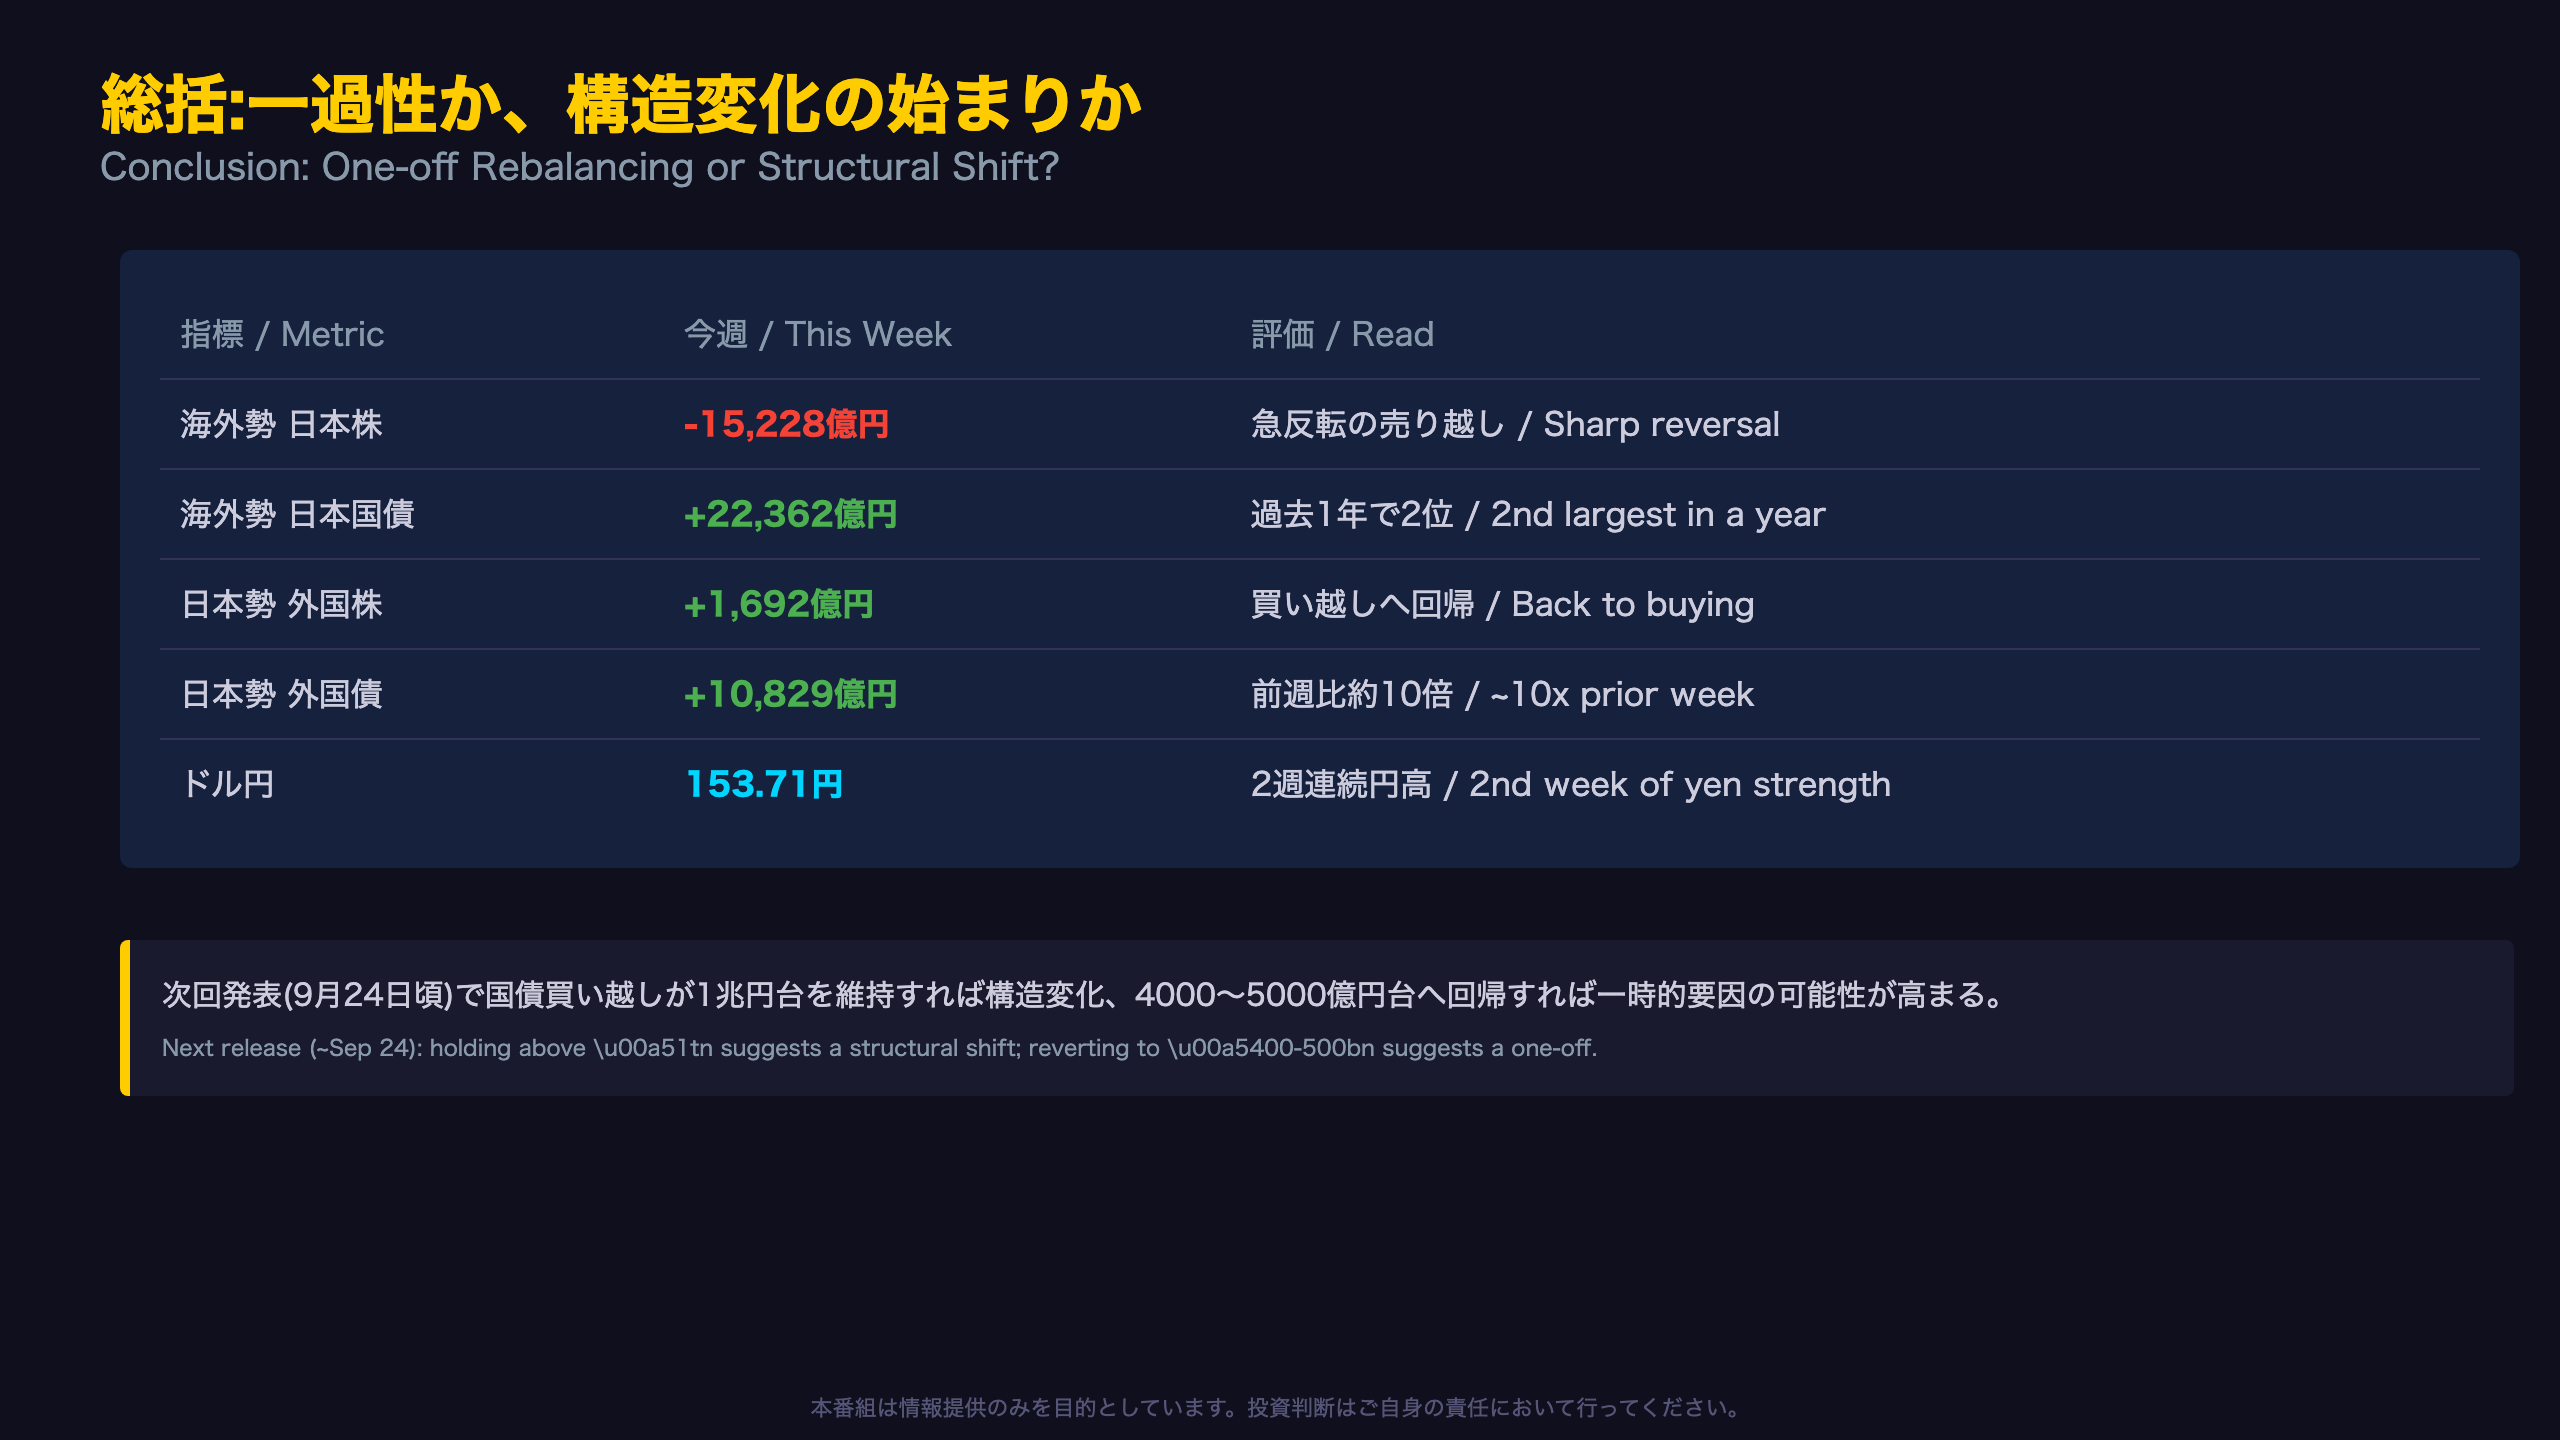
Summary and What to Watch Next
| Metric | This Week | Read |
|---|---|---|
| Foreign — JP Stocks | -\u00a51.52tn | Sharp reversal to selling |
| Foreign — JGBs | +\u00a52.24tn | 2nd-largest week in a year |
| Resident — Foreign Stocks | +\u00a50.17tn | Back to buying |
| Resident — Foreign Bonds | +\u00a51.08tn | ~10x prior week |
| USD/JPY | 153.71 | Second straight week of yen strength |
A useful threshold for next week: if foreign JGB buying holds above roughly \u00a51 trillion in the release expected around September 24th, it would strengthen the case for a structural rotation into Japanese bonds. A reversion to the more typical \u00a5400-500 billion range would instead point toward a one-off event, possibly tied to quarter-end or month-end institutional rebalancing.
On the equity side, the key question is whether foreign selling extends to a second consecutive week, a pattern that would raise concerns about weakening demand for Japanese stocks among overseas investors.
For readers unfamiliar with the series: this MOF report, published weekly, tracks contracted securities transactions between Japanese residents and non-residents, offering one of the fastest available reads on cross-border investment sentiment toward Japan.
Disclaimer: This article is for informational purposes only. All investment decisions are made solely at your own risk.